What is the scope and market significance of the Rheolytic Thrombectomy Market?
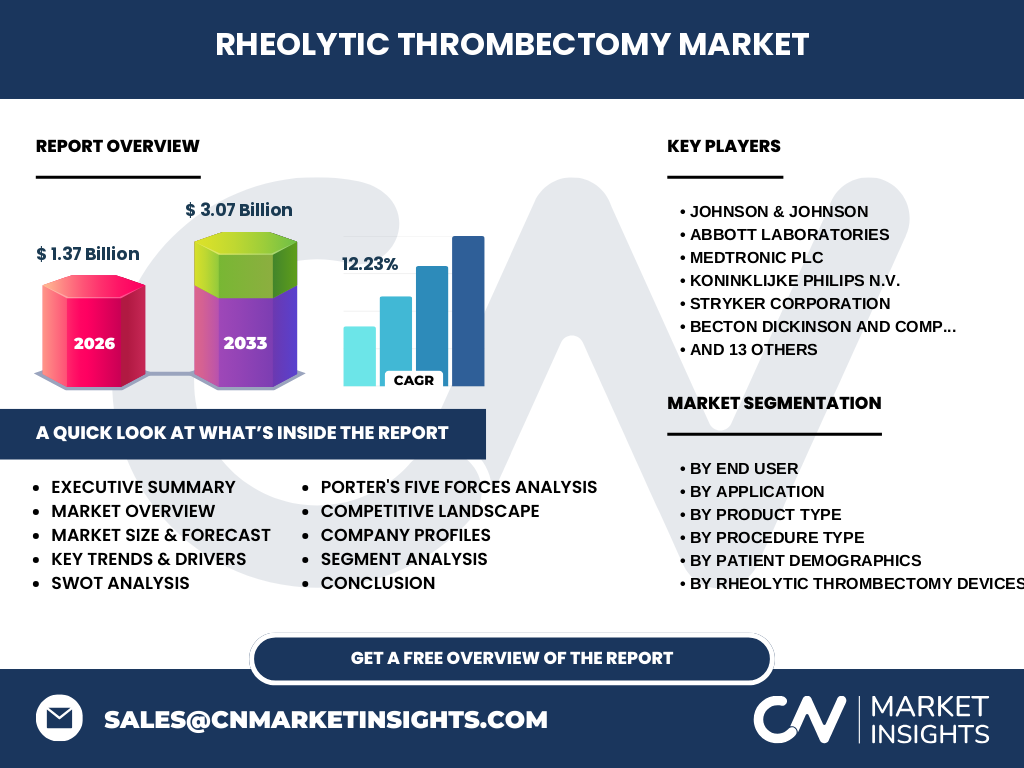
The Rheolytic Thrombectomy Market represents a highly specialized sector within endovascular interventions, valued at $1.37 Billion in 2026. This market encompasses advanced catheter-based hydrodynamic technologies utilized to dissolve and evacuate acute and chronic blood clots without damaging delicate vessel walls.
Key market drivers, restraints, challenges, and opportunities shaping the Rheolytic Thrombectomy Market
Structural growth is propelled by rising geriatric populations suffering from peripheral vascular diseases and pulmonary embolisms. However, strict clearance requirements from regulatory bodies like the FDA and stringent hospital capital expenditure budgets act as notable constraints for emerging device manufacturers.
Emerging trends and growth patterns in the Rheolytic Thrombectomy Market
A distinct clinical shift toward minimally invasive procedures is accelerating demand for multi-lumen rheolytic systems and high-pressure saline jet devices. Advanced imaging integration is becoming a baseline expectation for operators seeking real-time navigation inside complex vascular anatomies.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe elective surgery backlogs, temporarily depressing procedural volumes across acute and chronic limb ischemia cases. Vascular intervention centers have since rebounded aggressively, backed by elective procedure resurgences and robust supply chain adjustments across major medical ports.
Competitive landscape and strategic market dynamics
Industry leadership is fiercely contested among medtech giants like Boston Scientific Corporation, Medtronic plc, and Penumbra Inc. These players leverage expansive distribution networks and continuous R&D investments in aspiration and mechanical devices to capture high-margin hospital accounts.
Executive summary of key findings for the Rheolytic Thrombectomy Market
Our analysis indicates exceptional market momentum, projecting expansion from $1.37 Billion in 2026 to $3.07 Billion by 2033, driven by a compound annual growth rate of 12.23%. This robust trajectory rewards innovators specializing in cardiovascular and neurovascular applications.
Market forecast from 2027 to 2033
The sector is poised for exponential acceleration, scaling from its 2026 baseline to reach $3.07 Billion by 2033. This impressive 12.23% CAGR reflects accelerated clinical adoption in ambulatory surgical centers and specialized clinics globally.
Segmentation analysis across applications, products, and end-users
Market segmentation spans product types including rheolytic, aspiration, mechanical, and ultrasonic devices. End-user deployment is concentrated across hospitals and ambulatory surgical centers, while application categories target cardiovascular, peripheral vascular, neurovascular, and pulmonary embolism interventions.
Regional market analysis and geographic distribution performance
North America commands the primary revenue share due to well-established reimbursement codes and high concentrations of advanced catheter laboratories. Meanwhile, Asia-Pacific represents the fastest-growing frontier, fueled by expanding healthcare infrastructure and rising disposable incomes.
In-depth regional review of key geographic territories
U.S. hospitals drive high-value utilization of complex hydrodynamic systems, while Western European markets face stricter health technology assessments. Emerging markets in Latin America and Asia show promise despite localized logistics and reimbursement hurdles.
Company profiles and strategic positioning of leading participants
Major conglomerates like Johnson & Johnson and Abbott Laboratories focus on diversified cardiovascular portfolios, whereas specialized innovators like Inari Medical Inc. and AngioDynamics Inc. capture market share through dedicated clot-management technologies.
Porter's Five Forces analysis of the competitive environment
Bargaining power of buyers remains moderate due to consolidated hospital purchasing groups. Threat of new entrants is low given high regulatory barriers, intensive patent protection, and the capital-intensive nature of developing high-pressure saline jet and ultrasound devices.
SWOT analysis of the Rheolytic Thrombectomy Market
Strengths include superior clinical efficacy in treating acute limb ischemia. Weaknesses involve high device costs. Opportunities lie in underserved emerging economies, while threats persist from alternative pharmacological thrombolysis and stringent regulatory scrutiny.
Value chain analysis from raw materials to end-users
The value chain originates with medical-grade polymer and specialized alloy suppliers, flowing through precision device manufacturers, and culminating in sterilized distribution to hospital catheterization laboratories and ambulatory surgical centers.
Investment insights and high-potential areas for stakeholders
Venture capital and strategic acquirers should prioritize platforms featuring combined ultrasonic aspiration devices and multi-lumen rheolytic systems. These technologies command premium pricing and address critical unmet needs in complex stroke and pulmonary embolism treatments.
Conclusion and key takeaways for industry participants
The Rheolytic Thrombectomy Market offers compelling growth, backed by a projected 12.23% CAGR reaching $3.07 Billion by 2033. Success requires agile regulatory navigation, clinical differentiation, and targeted expansion into high-volume ambulatory centers.
Research methodology and baseline estimate triangulation
Baseline valuations are synthesized by cross-referencing trade registry data, import-export logs from major medical manufacturing hubs, and primary stakeholder interviews with vascular surgeons, combined with secondary macroeconomic indicators.
Scope of the report, coverage parameters, and limitations
This report evaluates global market performance across specific device classifications, procedure types, and patient demographics from 2026 through 2033. Limitations include localized reimbursement policy shifts and unpredicted macroeconomic supply chain disruptions.
Recent developments, product launches, and strategic industry moves
Recent market activity highlights increased M&A engagement, with major players acquiring specialized aspiration catheter startups. Regulatory clearances for next-generation acoustic pulse and vacuum-assisted devices continue to accelerate competitive positioning across global markets.