What is the defined scope and industry significance of the Military Aircraft Collision Avoidance Systems Market?
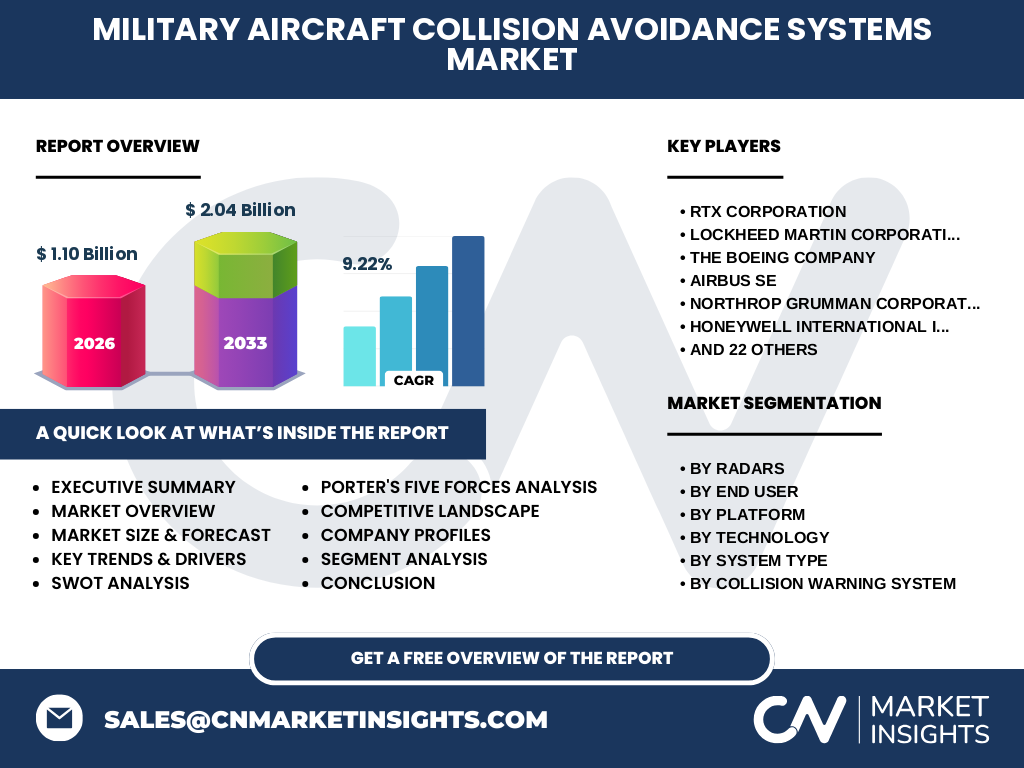
Our analysis indicates that the Military Aircraft Collision Avoidance Systems Market encompasses specialized avionics designed to prevent mid-air collisions and ground impacts across global defense fleets. Valued at $1.10 Billion in 2026, this sector is critical for safeguarding multi-million dollar assets and flight crews through advanced radar, synthetic vision, and terrain awareness architectures.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the Military Aircraft Collision Avoidance Systems Market?
Growth is heavily propelled by escalating defense budgets prioritizing pilot survivability and autonomous flight integration. However, severe supply chain bottlenecks for raw materials like beryllium and specialized semiconductors act as restraints. Technological complexity in integrating legacy platforms with modern predictive collision warning systems presents ongoing deployment challenges for prime contractors.
Emerging trends and growth patterns in the Military Aircraft Collision Avoidance Systems Market
The industry is witnessing an aggressive pivot toward computer vision systems and artificial intelligence-driven threat assessment tools. Based on our research, military modernization initiatives across Indo-Pacific and NATO member states are prioritizing unmanned aerial vehicles (UAV) safety architectures, driving substantial demand for low-altitude obstacle and cable detection systems.
How did the COVID-19 pandemic impact the Military Aircraft Collision Avoidance Systems Market and what is its recovery trajectory?
The pandemic severely disrupted component manufacturing and flight testing schedules, causing short-term revenue contractions. Nevertheless, the recovery trajectory has been robustly V-shaped, fueled by post-pandemic defense spending surges and accelerated digitalization mandates by regulatory authorities such as the FAA and international military aviation directorates.
Competitive landscape: major players, market concentration, and strategic dynamics
Market concentration is moderately high, dominated by aerospace giants like RTX Corporation, Lockheed Martin Corporation, and Northrop Grumman Corporation. Strategic dynamics involve aggressive mergers, acquisitions, and joint ventures aimed at securing proprietary sensor fusion technology and expanding footprint across OEM and aftermarket distribution channels.
Executive summary of key findings for the Military Aircraft Collision Avoidance Systems Market
Our comprehensive report reveals a thriving market projected to reach $2.04 Billion by 2033, expanding at a robust CAGR of 9.22% from 2027. Key value capture centers on SVS and advanced TCAS retrofits, with unmanned platforms acting as the primary catalyst for long-term valuation expansion.
What is the detailed market forecast for the Military Aircraft Collision Avoidance Systems Market from 2027 to 2033?
The market is poised for accelerated expansion, scaling from its 2026 baseline to $2.04 Billion by 2033 at a 9.22% CAGR. This trajectory is underpinned by scheduled fleet overhauls, rising geopolitical tensions, and mandatory mandates requiring advanced traffic alert and terrain awareness capabilities on all tactical aircraft.
Segmentation analysis of the Military Aircraft Collision Avoidance Systems Market
The market is segmented by radars (surveillance, ground proximity, weather, multifunction tracking), end users (OEM, aftermarket), platforms (manned, UAV), technology (laser, GPS, computer vision), and system types (radars, TCAS, TAWS, collision warning, obstacle avoidance, SVS). Each segment addresses specific operational requirements, with UAV platforms demonstrating the fastest adoption rates.
Regional market analysis and geographic distribution
North America dominates the global landscape due to massive defense outlays by the DoD and heavy investments by primes like The Boeing Company and General Atomics Aeronautical Systems Inc. Meanwhile, the Asia-Pacific region exhibits the highest growth velocity, driven by localized territorial disputes and aggressive fleet modernization programs in nations like India, Japan, and South Korea.
In-depth regional review of key defense markets
European markets are characterized by stringent interoperability standards enforced by the European Defence Agency, favoring advanced cooperative traffic alert systems developed by local leaders such as Thales S.A. and HENSOLDT AG. In contrast, the Middle East market prioritizes high-end electro-optical and laser-based solutions to counter asymmetric aerial threats.
Strategic positioning of leading companies in the Military Aircraft Collision Avoidance Systems Market
Industry leaders leverage distinct strategic advantages. BAE Systems plc and Leonardo S.p.A. focus on electronic warfare integration, while specialized innovators like Sagetech Avionics Inc. and uAvionix Corporation capture niche segments in micro-transponders for tactical UAVs, creating a balanced ecosystem of primes and agile tech providers.
Porter's Five Forces analysis of competitive intensity
Rivalry is intense among entrenched primes, while the threat of new entrants remains low due to prohibitive certification hurdles and high R&D thresholds. Bargaining power of suppliers is moderate, constrained by specialized defense-grade raw materials, whereas buyer power rests heavily with national ministries of defense exercising strict procurement oversight.
SWOT analysis of the Military Aircraft Collision Avoidance Systems Industry
Strengths include high system reliability and proprietary sensor fusion. Weaknesses involve long development cycles and exorbitant compliance costs. Opportunities lie in autonomous drone swarms and commercial-off-the-shelf (COTS) integration, while threats encompass cyber-vulnerabilities in GPS-based systems and unpredictable defense budget reallocations.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material providers supplying silicon wafers, rare earth magnets, and titanium alloys. Component manufacturers fabricate transceivers and processors, which integrators assemble into comprehensive systems like Enhanced Flight Vision Systems before final delivery to OEMs or direct military aftermarket depots.
Investment insights and strategic recommendations for stakeholders
Investors should target early-stage developers specializing in computer vision and machine learning collision avoidance algorithms. Strategic partnerships with established defense contractors offer the most reliable pathway to commercialization, bypassing complex procurement barriers and accelerating time-to-market for proprietary avionics.
Conclusion and key takeaways from our proprietary research report
The Military Aircraft Collision Avoidance Systems Market represents a high-barrier, lucrative sector poised to reach $2.04 Billion by 2033. Success hinges on mastering autonomous platform integration, maintaining strict adherence to military airworthiness standards, and leveraging advanced synthetic vision technologies to meet evolving global defense mandates.
Research methodology detailing data triangulation and baseline estimation
Our baseline estimates are derived through rigorous triangulation combining defense trade registry data, primary stakeholder interviews with chief engineers and procurement officers, and secondary macroeconomic defense expenditure indices. This multi-layered approach ensures precise sizing of both OEM and aftermarket segments across all tracked geographical regions.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing from 2026 to 2033 across specified technology, platform, and radar segments. Limitations include the exclusion of classified black-budget defense programs and unverified black-market military retrofits, focusing strictly on publicly disclosed contracts and authorized military procurement channels.
Recent developments, company announcements, and strategic industry moves
Recent industry momentum highlights major contract awards and technological partnerships, such as Elbit Systems Ltd. and Saab AB securing avionics upgrade contracts for tactical fleets. Concurrently, firms like Vigilant Aerospace Systems Inc. have advanced airspace integration trials for military-grade unmanned collision avoidance systems.