Market overview — definition, scope, and industry significance of Optical Biometers Market
Our analysis indicates the Optical Biometers Market reached 7.05 Billion in 2026, driven by precision requirements in intraocular lens power calculations. This sector encompasses advanced diagnostic devices utilizing technologies like Partial Coherence Interferometry and Swept Source Optical Coherence Tomography, which are critical for accurate axial length measurement prior to surgical interventions.
Key market drivers, restraints, challenges, and opportunities shaping Optical Biometers Market
The Optical Biometers Market industry trends are propelled by escalating cataract prevalence and rising demand for premium refractive outcomes. However, prohibitive device acquisition costs for ambulatory surgical centers act as a restraint. Opportunities flourish in developing integrated multi-parameter non-contact optical biometers that streamline clinical workflows and enhance diagnostic throughput.
Emerging trends and growth patterns in Optical Biometers Market
A definitive shift toward non-contact diagnostics is reshaping the Optical Biometers Market market size and trajectory. Devices leveraging Swept Source Optical Coherence Tomography are gaining dominance due to superior penetration in dense cataracts, allowing innovators like Carl Zeiss Meditec AG and Tomey Corporation to capture high-margin segments.
COVID-19 impact analysis — how the pandemic affected Optical Biometers Market and the recovery trajectory
The pandemic caused severe supply chain disruptions and deferred elective cataract procedures, temporarily compressing the Optical Biometers Market. Recovery materialized swiftly post-2021 as hospitals and ophthalmic clinics cleared surgical backlogs, accelerating capital equipment procurement for advanced optical coherence based non-contact optical biometers.
Competitive Benchmarking
The competitive ecosystem features established giants like Alcon Inc., Haag-Streit AG, and Topcon Healthcare Inc., alongside agile regional players such as TowardPi Medical Technology Co. Ltd. Market concentration remains moderately high, with legacy players leveraging global distribution networks while specialized manufacturers compete on proprietary optical resolution metrics.
Executive summary — high-level synthesis of key findings about Optical Biometers Market
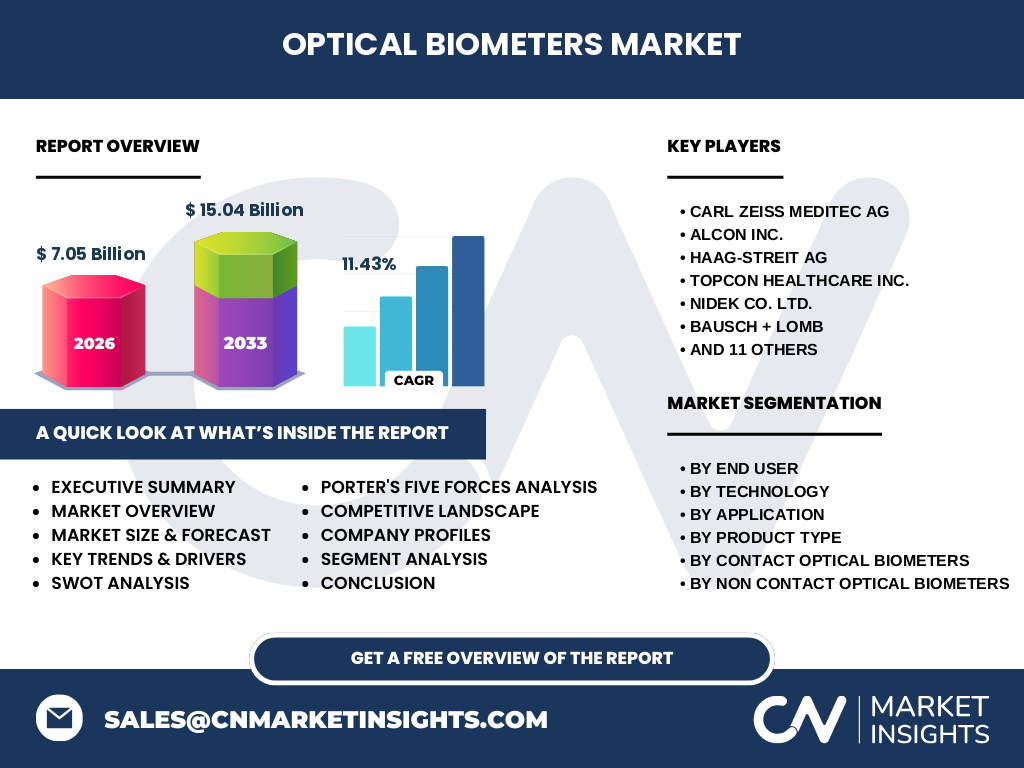
Our research confirms the Optical Biometers Market is projected to surge from 7.05 Billion in 2026 to 15.04 Billion by 2033, exhibiting a robust CAGR of 11.43%. Growth is anchored by technological convergence, demographic aging, and rising patient expectations for refractive precision following cataract surgery.
Market forecast — projected growth from 2027 to 2033
Driven by rising adoption across ophthalmic clinics and ambulatory surgical centers, the market will expand from 7.05 Billion in 2026 to reach 15.04 Billion by 2033. This expansion represents a steady 11.43% CAGR, reflecting sustained global demand for advanced biometry solutions.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The Optical Biometers Market industry trends are analyzed across four primary dimensions: End User (Hospitals, Ophthalmic Clinics, Ambulatory Surgical Centers), Technology (Partial Coherence Interferometry, Optical Low Coherence Reflectometry, Swept Source Optical Coherence Tomography), Application (Cataract, Refractive, Glaucoma Surgery), and Product Type (Contact versus Non-Contact Optical Biometers).
Regional market analysis — geographic distribution and performance across regions
Geographic performance highlights North America and Europe as traditional revenue powerhouses, sustained by high healthcare expenditure and rapid reimbursement adoption for premium IOL procedures. Meanwhile, Asia-Pacific emerges as the fastest-growing region, fueled by expanding healthcare infrastructure in China and India.
In-depth regional review — detailed examination of key regional markets
In North America, stringent FDA regulations favor established enterprises like Bausch + Lomb and Ziemer Ophthalmic Systems. Conversely, the Asia-Pacific market witnesses aggressive adoption of domestic innovations from Shanghai MediWorks and Tianjin Suowei Electronic Technology, challenging imported paradigms through cost-competitive clinical-grade contact and non-contact systems.
Company profiles — strategic positioning of leading companies in Optical Biometers Market
Industry leaders maintain distinct strategic moats: Carl Zeiss Meditec AG prioritizes optical precision integration, NIDEK Co. Ltd. focuses on ergonomic multi-parameter versatility, and Halma plc leverages decentralized subsidiary strengths. Emerging contenders like Huvitz Co. Ltd. and Lumibird Medical emphasize modular upgrading paths for budget-conscious clinics.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to specialized optical components, while buyer power is heightened by consolidated hospital procurement networks. Threat of new entrants is mitigated by high R&D thresholds and strict regulatory compliance mandates from bodies like the FDA and EMA.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths include unmatched measurement accuracy for complex eyes. Weaknesses involve high maintenance costs. Opportunities lie in artificial intelligence integration for automated lens calculations. Threats include macroeconomic pricing pressures and regulatory compliance delays for novel swept-source iterations.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with high-purity optical glass and semiconductor sensor suppliers, flowing through precision assembly by manufacturers like Optopol Technology Sp. z o.o. and Visionix Company, and culminating in clinical deployment across ambulatory surgical centers and hospital ophthalmic departments.
Investment insights — strategic recommendations and high-potential areas
Investors should target manufacturers specializing in swept-source optical coherence tomography and portable contact optical biometers. These segments align with decentralized healthcare delivery models, offering superior margin potential and rapid commercialization pathways in emerging markets.
Conclusion and key takeaways
The Optical Biometers Market represents a high-growth, technology-driven sector projected to hit 15.04 Billion by 2033. Stakeholders must prioritize R&D in non-contact, AI-assisted modalities to capture market share in an increasingly competitive global landscape.
Research methodology — detail how baseline estimates are triangulated
Our research methodology combines exhaustive primary stakeholder interviews with ophthalmic surgeons and procurement directors, triangulated against secondary trade registry data, import-export logs from major customs ports, and macroeconomic health expenditure indicators to establish baseline figures.
Scope of the report — coverage parameters and limitations
This report covers global revenue performance for the Optical Biometers Market from 2026 to 2033. Limitations include unforeseen geopolitical disruptions and varying regional reimbursement policies that may marginally shift projected adoption velocities across specific product tiers.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent industry momentum is defined by strategic product rollouts, including enhanced swept-source biometers by companies like Nanjing Redsun Optical and regional distribution partnerships forged by Haag-Streit AG to penetrate underserved emerging markets with advanced diagnostic infrastructure.