What is the scope and industry significance of the Carburizing Furnace Market?
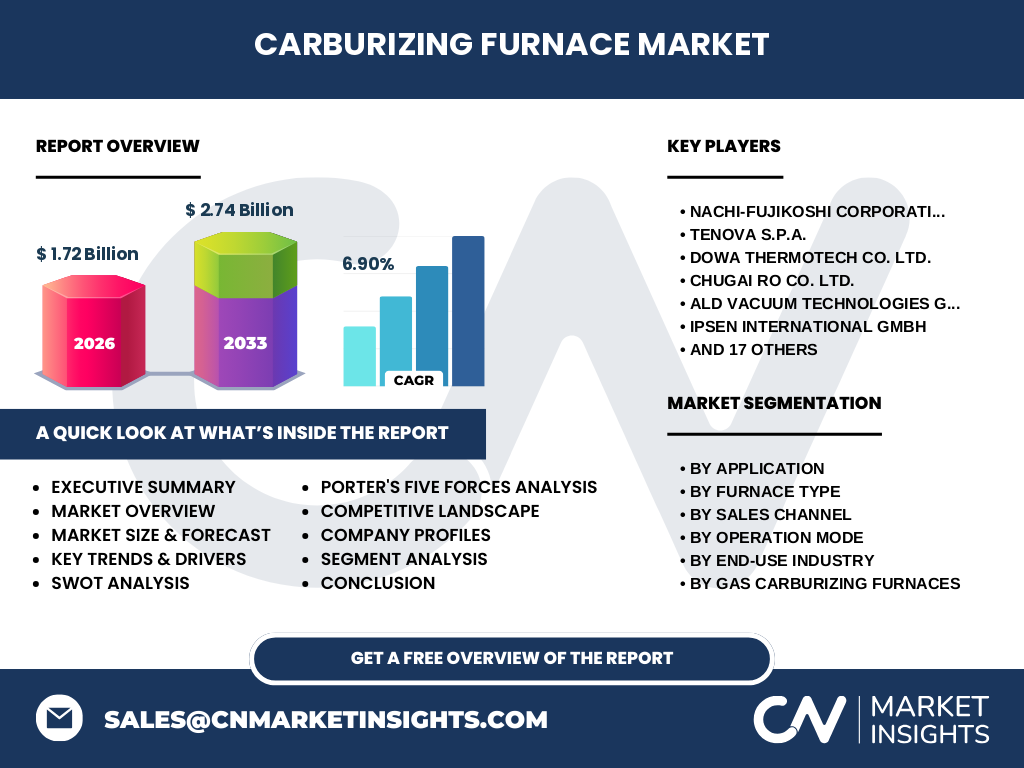
Our analysis indicates that the Carburizing Furnace Market stands at a robust valuation of 1.72 Billion in 2026. This foundational thermal processing sector enables critical surface hardening for high-stress components across aerospace, automotive, and heavy machinery industries, complying with stringent ISO and AMS metallurgical standards.
What are the structural growth drivers, restraints, challenges, and opportunities in the sector?
Market expansion is heavily anchored by rising global EV adoption and lightweighting demands in powertrain manufacturing. However, high capital expenditure for advanced vacuum units and volatile refractory material costs act as restraints. Opportunities lie in integrating IoT-enabled process controllers to optimize endothermic gas atmospheres and reduce carbon footprints.
Emerging trends and technological shifts in the industry
The transition from conventional atmosphere systems to low-pressure vacuum carburizing (LPVC) combined with high-pressure gas quenching (HPGQ) is revolutionizing heat treatment facilities. Key innovators like ALD Vacuum Technologies and ECM Technologies are driving this shift to eliminate intergranular oxidation and reduce cycle times.
How did the COVID-19 pandemic impact the market and its recovery trajectory?
Pandemic-induced supply chain disruptions and automotive plant shutdowns temporarily contracted equipment orders in 2020. Recovery has been robustly propelled by aggressive modernization initiatives in aftermarket services and retrofits, allowing manufacturers like SECO/WARWICK to capture pent-up demand for energy-efficient thermal upgrades.
Competitive benchmarking and strategic market dynamics
The Carburizing Furnace Market exhibits moderate consolidation, featuring global powerhouses alongside specialized regional engineering firms. Market leaders differentiate through proprietary low-distortion quenching technologies and turnkey automation integration, positioning established entities like Ipsen and Tenova at the forefront of high-precision metallurgical processing.
Executive summary of key findings and valuation metrics
Driven by compounding industrial automation demands, the market is projected to reach 2.74 Billion by 2033, expanding at a steady CAGR of 6.90% from 2027. Strategic focus is shifting decisively toward vacuum and plasma systems that offer superior metallurgical uniformity and environmental compliance.
Market forecast trajectory from 2027 to 2033
Our research forecasts accelerated momentum during the 2027 to 2033 timeframe, scaling from the 2026 baseline of 1.72 Billion to culminate at 2.74 Billion by 2033. This growth is underpinned by stringent quality mandates in the aerospace sector and massive infrastructure investments across emerging economies.
Segmentation analysis by application, furnace type, sales channel, operation mode, and end-use
Segmentation reveals critical demand concentrations: Gears and bearings dominate application requirements due to electrification trends; Vacuum and gas carburizing furnaces lead equipment choices; new equipment sales and aftermarket parts maintain balanced revenue flows across automotive and heavy industrial sectors.
Geographic distribution and regional market performance
Regional performance reflects localized manufacturing prowess, with the Asia-Pacific region leading volume consumption driven by automotive hubs in China, Japan, and India. North America and Europe maintain high-value demand focused on advanced aerospace alloys and strict environmental emissions standards overseen by bodies like the EPA.
In-depth regional review of manufacturing and industrial hotspots
Industrial clusters in Western Europe and the US Rust Belt prioritize energy efficiency and furnace retrofits to meet decarbonization targets. Meanwhile, rapid industrialization in Southeast Asia accelerates greenfield investments in commercial heat-treating facilities utilizing advanced sealed quench and pit-type furnaces.
Strategic positioning of leading enterprise profiles
Prominent participants such as Surface Combustion, Gasbarre Furnace Group, and Dowa Thermotech leverage deep engineering expertise and localized service networks. Their strategic focus centers on modular design flexibility and proprietary software for real-time carbon potential control.
Porter's Five Forces competitive intensity assessment
Competitive rivalry is intense, characterized by continuous technological patenting among major international players. Supplier power remains moderate due to specialized alloy and insulation requirements, while buyer power is balanced by the high switching costs associated with complex custom thermal processing lines.
SWOT analysis of the thermal processing sector
Strengths include advanced metallurgical precision and high automation levels. Weaknesses involve high initial capital outlays. Opportunities emerge from EV drivetrain component hardening, while threats stem from strict regulatory constraints on greenhouse gas emissions and volatile electricity tariffs impacting continuous-mode operations.
Value chain analysis from raw materials to end-user deployment
The value chain originates with specialty alloy steel and refractory brick producers, flowing through specialized furnace engineering design houses like Can-Eng Furnaces and Solar Manufacturing, and culminating in tier-1 automotive and aerospace component manufacturers requiring precision case hardening.
Strategic investment insights and high-potential growth pockets
Investors should target developers of multi-chamber vacuum and pulsed plasma systems. These technologies offer superior distortion control for complex geometries, aligning perfectly with next-generation electric vehicle transmission manufacturing and high-bypass turbine engine production.
Conclusion and critical industry takeaways
The Carburizing Furnace Market represents a technologically dynamic landscape poised for steady expansion to 2.74 Billion by 2033. Success relies heavily on proprietary vacuum innovations, digital transformation through IoT integration, and compliance with rigorous global energy standards.
Research methodology for baseline estimation and data triangulation
Our baseline estimates are triangulated using a rigorous mix of primary stakeholder interviews with chief metallurgists and plant operators, supplemented by cross-referencing trade registry data, customs import-export logs, and secondary macroeconomic indicators from industrial manufacturing associations.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance, unit shipments, and technological evaluations across five core segmentation vectors from 2026 to 2033. Limitations include localized pricing variances driven by regional raw material supply chains and proprietary pricing confidentiality among privately held furnace manufacturers.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is highlighted by strategic joint ventures focused on hydrogen-assisted low-pressure carburizing and automated loading robotics. Key market actors continue to invest heavily in R&D to reduce cycle times and integrate artificial intelligence for predictive maintenance of heating elements and quench systems.