What is the scope and industry significance of the Pipe Support Cradle Market?
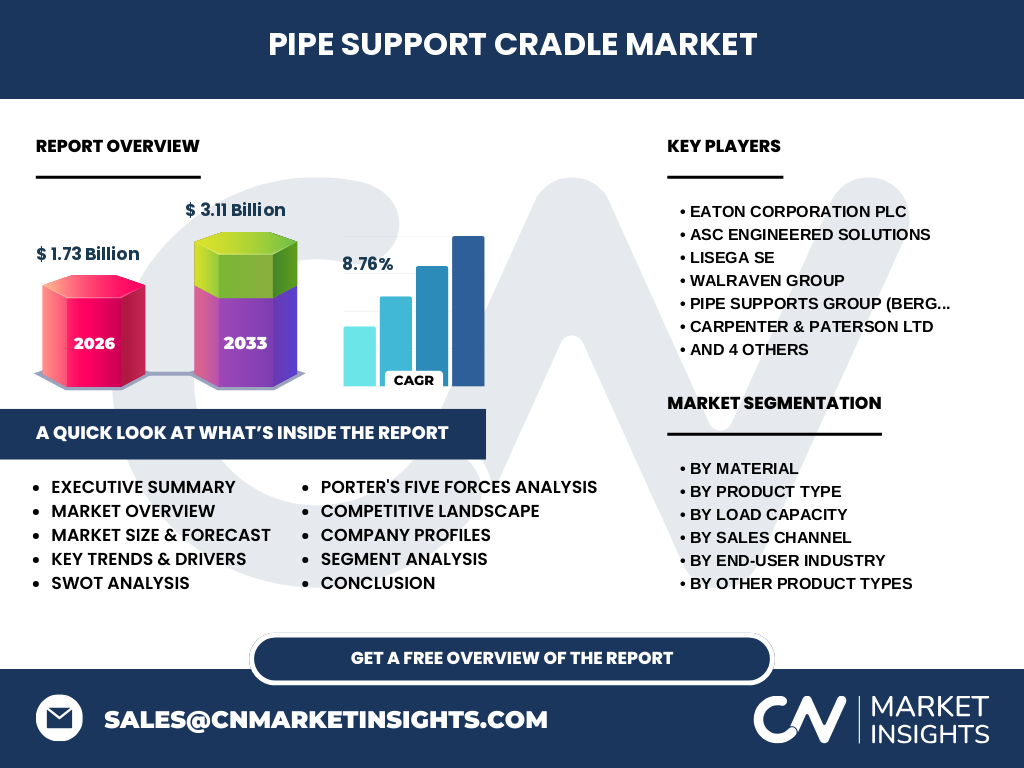
Our analysis indicates that the Pipe Support Cradle Market is foundational to heavy industrial piping architecture, preventing mechanical fatigue and thermal stress. Evaluated at 1.73 Billion in 2026, these engineered load-bearing devices protect critical fluid transmission networks across aggressive chemical processing, high-pressure hydrocarbon extraction, and power generation facilities globally.
Structural Growth Drivers, Restraints, and Opportunities
Based on our research, the sector is propelled by rapid infrastructure modernization and stringent safety codes set by agencies like ASME and ISO. However, supply chain volatility in raw materials such as alloy steel and specialized composites restrains high-volume fabrication. Opportunities abound in retrofitting aging municipal water systems with advanced corrosion-resistant cradles.
Emerging trends and growth patterns in Pipe Support Cradle Market
The data suggests a strong pivot toward advanced thermal and acoustic insulated assemblies to minimize heat loss in cryogenic LNG plants. Engineering firms increasingly demand custom-fabricated, vibration-dampening units, favoring manufacturers capable of tailoring solutions to severe seismic and thermal expansion stresses.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted project pipelines across the globe, halting non-essential industrial construction and delaying maintenance turnarounds in refineries. Nevertheless, the market has staged a robust recovery, buoyed by government-backed stimulus injections into critical utility infrastructure and resilient post-pandemic supply chains.
Competitive Benchmarking and Market Concentration
The landscape is characterized by strategic consolidation among tier-one equipment providers. Market concentration remains moderately high, with specialized heavyweights like LISEGA SE and ASC Engineered Solutions leveraging massive distribution footprints and proprietary engineering designs to command substantial pricing power over regional fabricators.
Executive Summary: Pipe Support Cradle Market Overview
Our comprehensive report reveals a thriving sector valued at 1.73 Billion in 2026, set to expand to 3.11 Billion by 2033. Driven by a robust 8.76% CAGR, this market presents exceptional profitability for agile manufacturers investing in composite materials and automated manufacturing workflows.
Market Forecast and Valuation Trajectory (2027 to 2033)
The market is projected to surge from its 2026 baseline to reach 3.11 Billion by 2033, expanding at a notable 8.76% CAGR. This accelerated growth is underwritten by massive capital expenditure allocations in Middle Eastern upstream oil extraction and North American shale infrastructure.
Segmentation Analysis: Material, Product, Load, Channel, and End-User
The ecosystem is meticulously segmented by material (steel, stainless steel, aluminum, composites), product type (adjustable, fixed, insulated), and load capacity (light, medium, heavy-duty). Sales operate through direct OEM supply, aftermarket channels, and distributors, serving critical verticals from power generation to mining.
Regional Market Analysis and Geographic Performance
Geographic performance mirrors heavy industrialization rates, with North America and Asia-Pacific leading deployment. North America benefits from extensive shale and pipeline renewals, while Asia-Pacific witnesses massive urbanization and chemical plant construction, heavily utilizing heavy-duty and corrosion-resistant variants.
In-Depth Regional Review of High-Growth Territories
Regional dynamics heavily favor economies with aggressive energy transitions. Asia-Pacific dominates volume consumption through massive power and water projects in coastal manufacturing hubs. Meanwhile, European markets enforce strict environmental mandates, driving rapid adoption of specialized thermal and acoustic insulated cradles.
Strategic Company Profiles and Market Positioning
Industry leaders employ distinct strategies to capture market share. Eaton Corporation plc and Walraven Group focus on broad commercial and industrial distribution, whereas Piping Technology & Products Inc. and Bergen Pipe Supports target extreme high-load petrochemical environments requiring bespoke engineering.
Porter's Five Forces Analysis of Competitive Pressures
Our analysis indicates moderate-to-high supplier bargaining power due to volatile raw material input costs. Threat of new entrants remains constrained by stringent quality certifications and high capital expenditure requirements for precision fabrication machinery, protecting established enterprise margins.
SWOT Analysis of the Pipe Support Cradle Industry
Key strengths include high structural durability and mandatory regulatory compliance. Weaknesses involve heavy reliance on volatile metal commodities. Opportunities lie in offshore wind energy infrastructure, while major threats stem from prolonged geopolitical trade disputes impacting global steel shipments.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw metal mills and polymer processors, moving through specialized engineering fabricators, then traversing global logistics networks via major industrial distributors, ultimately landing at EPC contractors managing mega-projects in oil, gas, and power generation.
Investment Insights and High-Potential Strategic Areas
High-potential capital allocation targets manufacturers pioneering lightweight composite and corrosion-resistant designs. Investors should prioritize firms with strong direct OEM channels in fast-growing renewable energy and green hydrogen transport sectors requiring specialized sliding and spring-supported cradles.
Conclusion and Strategic Takeaways
The Pipe Support Cradle Market represents a resilient, high-growth industrial sector primed for expansion through 2033. Success requires aligning product portfolios with advanced composite material demands and leveraging robust distributor networks to capture aftermarket replacement revenue.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with engineering executives, exhaustive trade registry data from global customs databases, and secondary macroeconomic indicators tracking global capital expenditures in heavy process industries.
Scope of the Report and Coverage Parameters
This report covers global revenue performance and volume shipments from 2026 to 2033, analyzing all major material variants, load classes, and end-user verticals. Exclusions apply to custom-built structural steel frameworks outside standard pipe support classifications.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features key players forming strategic distribution joint ventures and launching innovative modular, height-adjustable composite cradles designed to reduce installation time by up to forty percent in congested offshore platform modules.