Market overview and structural significance of the Reversed-Phase Chromatography Columns Market
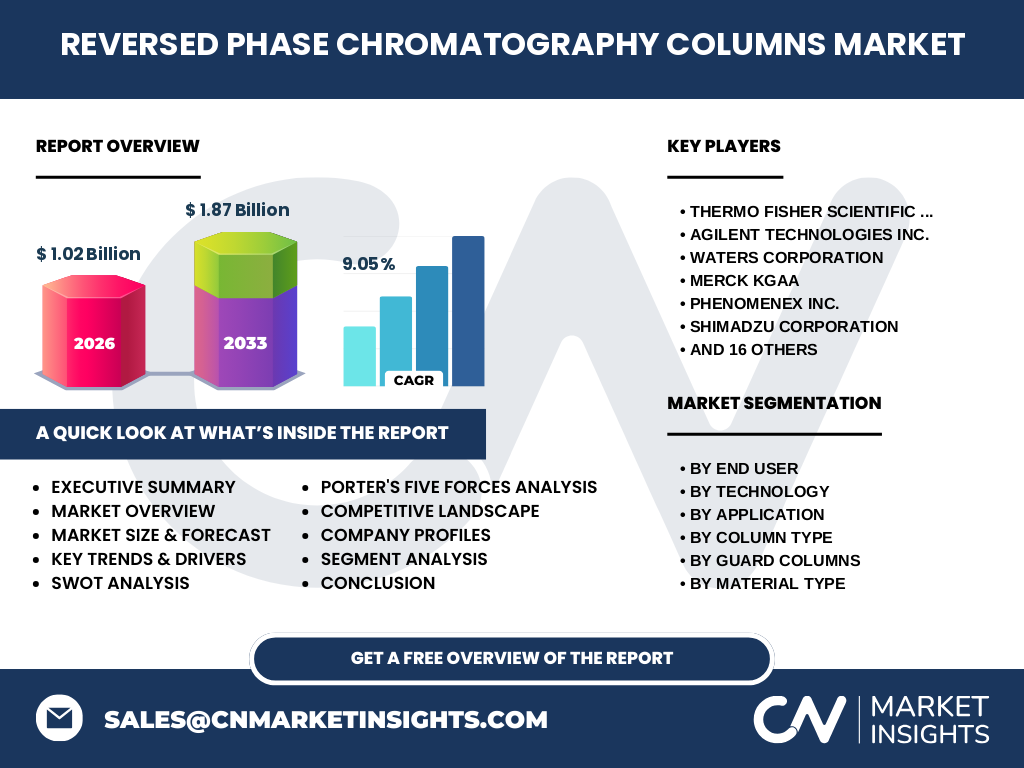
Our analysis indicates that the Reversed-Phase Chromatography Columns Market is valued at 1.02 Billion in 2026. This sector underpins biopharmaceutical purity testing and small-molecule drug discovery. Regulatory bodies like the US FDA mandate rigorous impurity profiling, driving laboratories to deploy advanced hydrophobic stationary phases to ensure compliance and patient safety.
Key market drivers, restraints, challenges, and opportunities shaping the industry
Growth is propelled by surging monoclonal antibody pipelines, yet supply chain bottlenecks for high-purity spherical silica raw materials create margin pressures. Strategic opportunities emerge in green solvent compatibility and automated column hardware. Companies like Waters Corporation and Agilent Technologies Inc. are investing heavily to overcome these operational constraints and capture surging demand.
Emerging trends and technological growth patterns
The transition toward sub-2-micron particle architectures and hybrid inorganic-organic stationary phases represents a major paradigm shift. Laboratories handling complex peptide maps rely on Ultra High Performance Liquid Chromatography setups to maximize resolution, favoring innovative column designs from Phenomenex Inc. and Restek Corporation that withstand extreme pH operational thresholds.
COVID-19 impact analysis and post-pandemic recovery trajectory
The pandemic initially disrupted raw material procurement and stretched logistics across major global ports, yet it ultimately accelerated vaccine and antiviral development. This catalyzed long-term structural investment in high-throughput purification equipment. The sector rebounded robustly, setting the stage for steady expansion toward a 2027-2033 valuation of 1.87 Billion.
Competitive benchmarking and strategic market concentration dynamics
The market features high consolidation among tier-one analytical instrument manufacturers. Industry leaders such as Thermo Fisher Scientific Inc., Shimadzu Corporation, and Merck KGaA leverage extensive global distribution networks and proprietary surface-modification chemistries. Smaller niche players survive by offering specialized silica-based or polymer-based sorbents tailored for demanding academic research applications.
Executive summary of key findings
Driven by a robust 9.05% CAGR, the market is scaling rapidly toward 1.87 Billion by 2033. High-performance liquid chromatography columns dominate biopharmaceutical quality control. Strategic positioning hinges on proprietary bonding chemistries, robust supply chain resilience, and alignment with stringent environmental testing and food safety regulations enforced by the EPA and EFSA.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the market will expand from its 2026 baseline of 1.02 Billion to reach 1.87 Billion by 2033 at a 9.05% CAGR. This acceleration reflects sustained R&D investments by biopharmaceutical innovators and environmental monitoring agencies requiring ultra-sensitive analytical columns for trace contaminant detection.
Segmentation analysis by end user, technology, application, and column type
The market segments into critical operational categories. By End User: Industry And Pharmaceuticals, Biotechnology, Academic Research, Environmental Testing, and Food And Beverage. By Technology: High Performance Liquid Chromatography, Ultra High Performance Liquid Chromatography, Fast Protein Liquid Chromatography, Capillary Liquid Chromatography, and Nano Liquid Chromatography. By Application: Protein Purification, Peptide Purification, Drug Discovery And Development, Quality Control And Analytical Testing, and Other Applications. By Column Type: Analytical Columns, Preparative Columns, Semi Preparative Columns, Guard Columns, and Microbore Columns.
Regional market analysis and geographic distribution performance
North America commands the largest revenue share, sustained by dense clusters of biopharmaceutical innovators and stringent FDA oversight. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, propelled by expanding contract manufacturing organizations in India and China, alongside substantial capital investments in life sciences infrastructure by firms like Tosoh Corporation and YMC Co. Ltd.
In-depth regional review of key geographic markets
European markets demonstrate steady expansion driven by European Medicines Agency compliance standards and advanced environmental testing protocols. Concurrently, North American laboratories prioritize high-throughput drug discovery platforms. Regional adoption rates heavily favor advanced hybrid and monolithic column materials to maximize analytical throughput and minimize solvent consumption.
Company profiles and strategic positioning of industry leaders
Market leaders combine consumable column manufacturing with proprietary instrumentation ecosystems. Waters Corporation and Agilent Technologies Inc. anchor their strategies in end-to-end workflow solutions. Concurrently, specialized Japanese innovators like Daicel Corporation and Osaka Soda Co. Ltd. dominate chiral and specialty stationary phase niches, while firms like Biotage AB focus on flash purification solutions.
Porter's Five Forces analysis of competitive pressures
Competitive rivalry remains intense among established consumables manufacturers, while the threat of substitute technologies like capillary electrophoresis is moderated by liquid chromatography's unmatched preparative scalability. Bargaining power of suppliers is moderate due to specialized silica sourcing requirements, whereas buyer power is diluted by strict analytical validation protocols that discourage frequent brand switching.
SWOT analysis of the industry landscape
Strengths include high separation efficiency and robust regulatory integration. Weaknesses involve high column costs and sensitivity to aggressive mobile phase conditions. Opportunities lie in emerging green chromatography protocols and monoclonal antibody scale-up. Threats encompass counterfeit consumables circulating in developing regions and stringent raw material trade tariffs.
Value chain analysis from raw materials to end-users
The value chain originates with high-purity silica, zirconia, and polymer resin synthesis. Chemical refiners supply these precursors to column manufacturers such as Phenomenex Inc. and Restek Corporation for bonding and packing. Finished columns flow through specialized distributors or direct sales channels to pharmaceutical quality control labs, environmental agencies, and academic institutions.
Investment insights and strategic high-potential growth areas
High-potential capital allocation targets manufacturers specializing in sub-2-micron hybrid materials and eco-friendly column recycling technologies. Investors should prioritize firms demonstrating strong partnerships with contract development and manufacturing organizations, as these entities represent high-volume recurring revenue streams for analytical and preparative columns.
Conclusion and key strategic takeaways
Reaching 1.87 Billion by 2033 at a 9.05% CAGR, this market offers robust expansion fueled by biopharmaceutical innovation. Success requires continuous material science R&D, stringent regulatory alignment, and agile manufacturing capabilities to serve diverse end-users ranging from environmental testing laboratories to global pharmaceutical enterprises.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with chief technology officers across top manufacturing firms, and secondary macroeconomic indicators. We cross-reference custom econometric models with historical shipment data from major port hubs to ensure high-fidelity market sizing.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance, volume shipments, and technological segmentation from 2026 to 2033. Scope parameters encompass analytical, preparative, semi-preparative, guard, and microbore columns across five primary end-user verticals. Limitations exclude bespoke custom-packed columns engineered exclusively for proprietary academic research applications outside commercial registries.
Recent developments, strategic partnerships, and product launches
Recent industry momentum highlights strategic acquisitions and advanced product rollouts. Major players such as Shimadzu Corporation and Thermo Fisher Scientific Inc. have launched green-solvent compatible column lines. Concurrently, regional partnerships between column manufacturers and contract research organizations aim to streamline regulatory filings and accelerate biotherapeutic drug discovery timelines globally.