Market Overview of the Laser-Based Defense Systems Market
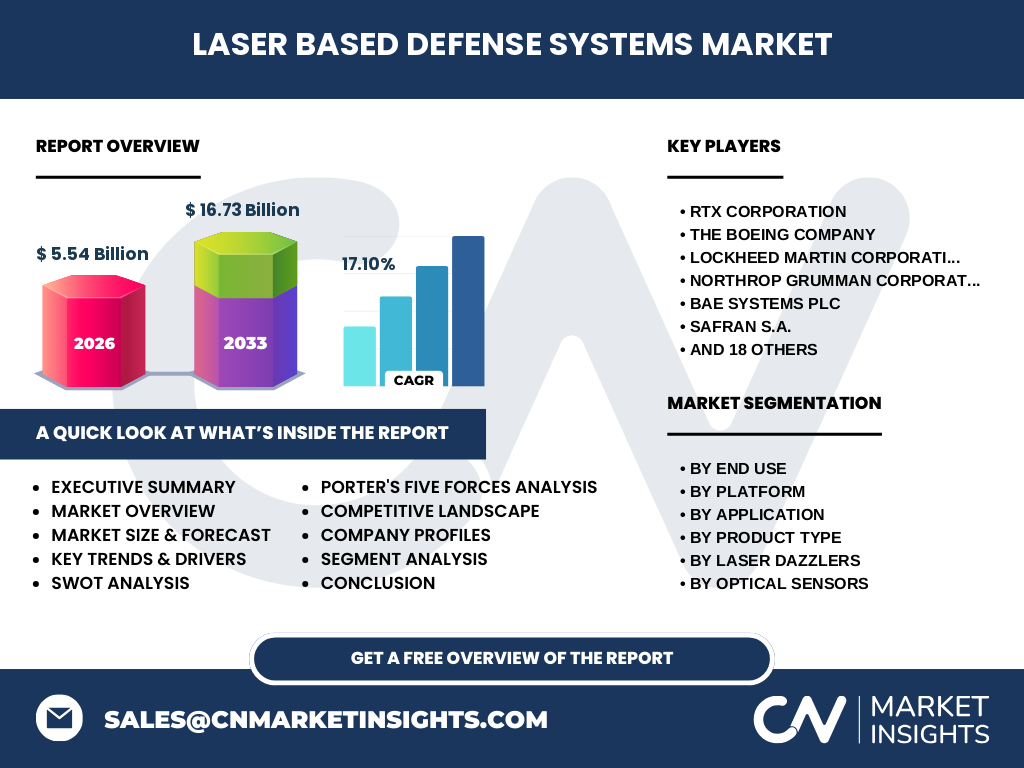
Our analysis indicates that the Laser-Based Defense Systems Market represents a pivotal segment in modern military technology, valued at $5.54 Billion in 2026. This sector encompasses advanced directed-energy capabilities managed by defense forces and homeland security agencies, utilizing critical components like rare-earth optical materials and high-voltage power supplies to counter evolving aerial and ground threats.
What are the primary market drivers, restraints, challenges, and opportunities in the Laser-Based Defense Systems Market?
Growth is accelerated by rising asymmetric threats and the imperative for cost-per-engagement reduction, though thermal management issues and stringent export controls by bodies like ITAR remain key constraints. Opportunities abound in integrating solid-state lasers and fiber lasers into mobile platforms, offering firms like Lockheed Martin and Rheinmetall AG prime expansion avenues.
Emerging Trends and Growth Patterns Shaping Industry Evolution
The data suggests a strong shift toward modular Tactical Laser Systems and adaptive beam steering, minimizing atmospheric distortion over contested operational theaters. Innovators are heavily prioritizing high-efficiency fiber lasers and compact power modules to reduce logistical footprints for deployed units, directly addressing modern battlefield power demands.
How did the COVID-19 pandemic impact the Laser-Based Defense Systems Market and shape its recovery trajectory?
Pandemic-induced supply chain bottlenecks for specialty optical sensors and semiconductor components temporarily delayed prototype testing across key defense contractors. However, accelerated post-pandemic modernization budgets and heightened geopolitical tensions rapidly restored momentum, steering the industry toward its robust $16.73 Billion valuation by 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains high among top-tier aerospace primes including RTX Corporation, Northrop Grumman Corporation, and The Boeing Company, who leverage extensive supply chains and defense contract access. These giants frequently partner with specialized laser innovators like IPG Photonics Corporation to integrate cutting-edge High Energy Laser Weapons into legacy platforms.
Executive Summary of the Laser-Based Defense Systems Market Research Report
Driven by an exceptional 17.10% CAGR from 2027 to 2033, the Laser-Based Defense Systems Market industry trends highlight an unprecedented technological transition toward directed-energy solutions. Our research underscores that stakeholders must prioritize R&D in thermal dissipation and beam control to capture high-value procurement contracts across naval, airborne, and land domains.
Market Forecast Analysis from 2027 to 2033
Starting from a baseline of $5.54 Billion in 2026, the market is projected to surge to $16.73 Billion by 2033, expanding at a remarkable 17.10% CAGR. This accelerated trajectory reflects massive defense spending shifts toward missile defense and counter-drone applications, supported by active procurement programs from major global military forces.
Segmentation Analysis Across Applications, Platforms, and Products
The market bifurcates across end-uses like Defense Forces and Homeland Security Agencies, deployed across Land, Naval, Airborne, and Space platforms. Product ecosystems range from Laser Weapon Systems and Laser Dazzlers to sophisticated Optical Sensors and Power Supply Units, tailored for specialized missile defense and border security missions.
Geographic Distribution and Regional Performance Overview
Regional performance is heavily anchored by North America, driven by extensive Department of Defense directed-energy initiatives, followed by rapid adoption in the Asia-Pacific region due to rising territorial disputes. European markets show steady growth, steered by collaborative European Defence Fund initiatives involving industry leaders like MBDA and Thales Group.
In-Depth Regional Review and Localized Market Constraints
North America dominates through substantial R&D funding allocated to companies like General Atomics Aeronautical Systems Inc. and L3Harris Technologies Inc. Meanwhile, the Middle East represents a high-demand zone for perimeter security dazzlers and counter-drone systems, navigating strict regional compliance frameworks and harsh desert environmental testing constraints.
Strategic Positioning of Leading Companies in the Ecosystem
Industry titans such as BAE Systems plc, Leonardo S.p.A., and Elbit Systems Ltd. maintain competitive moats through proprietary electro-optical targeting systems and robust intellectual property portfolios. Concurrently, specialized agile players like AeroVironment Inc. and Kratos Defense & Security Solutions focus on tactical counter-UAV integration to capture niche defense segments.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power is moderately high due to the specialized nature of rare-earth gain media and high-voltage power components, while threat of new entrants remains exceptionally low given prohibitive R&D costs and rigorous military certification barriers. Buyer power is concentrated among sovereign defense ministries, driving intense technological differentiation among prime contractors.
SWOT Analysis of the Laser-Based Defense Systems Sector
Strengths lie in precision engagement capabilities and drastically reduced ammunition costs per shot, whereas weaknesses include high initial capital expenditures and susceptibility to adverse atmospheric weather. Key opportunities involve miniaturizing systems for tactical vehicles, while threats stem from the rapid proliferation of low-cost drone swarms and competing electromagnetic jamming technologies.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying specialty optical fibers and semiconductor crystals, flowing through component manufacturers producing Beam Control Systems and Infrared Countermeasure Systems. Primes integrate these subsystems into final platforms deployed by end-users like Israel Aerospace Industries and Rafael Advanced Defense Systems Ltd. for operational defense.
Strategic Investment Insights and High-Potential Areas
Investors should target early-stage innovators specializing in Adaptive Beam Steering Systems and High Voltage Power Supply Units, as power management remains the primary bottleneck for mobile deployment. Partnerships with established defense contractors like Rheinmetall AG offer viable pathways to secure long-term military supply contracts.
Conclusion and Key Takeaways for Market Stakeholders
Reaching $16.73 Billion by 2033 at a 17.10% CAGR, the Laser-Based Defense Systems Market analysis confirms that directed energy is transitioning from experimental R&D to essential frontline capability. Organizations that master thermal management, beam stability, and multi-platform integration will dominate this high-growth defense landscape.
Research Methodology and Baseline Estimation Techniques
Our baseline estimates are rigorously triangulated by combining official defense budget registries, trade data from customs authorities on electro-optical components, and primary stakeholder interviews with chief technologists at firms like nLIGHT Inc. and CILAS. Macroeconomic defense expenditure indicators and historical program funding further validate our growth projections.
Scope of the Report, Coverage Parameters, and Limitations
This report evaluates the global Laser-Based Defense Systems Market market size across four major product categories, four platform types, and specific technological classifications from 2026 to 2033. Limitations include restricted access to classified military black-budget projects and rapid policy shifts within national defense procurement bodies like the U.S. DoD and European ministries.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum features major contract awards to Northrop Grumman Corporation and Lockheed Martin Corporation for high-energy tactical laser demonstrations. Furthermore, strategic collaborations between firms like Coherent Corp. and defense primes highlight a concerted industry push to scale up commercial production of ruggedized fiber laser modules for operational use.