What is the scope and definition of the Military Sensor Fusion Market?
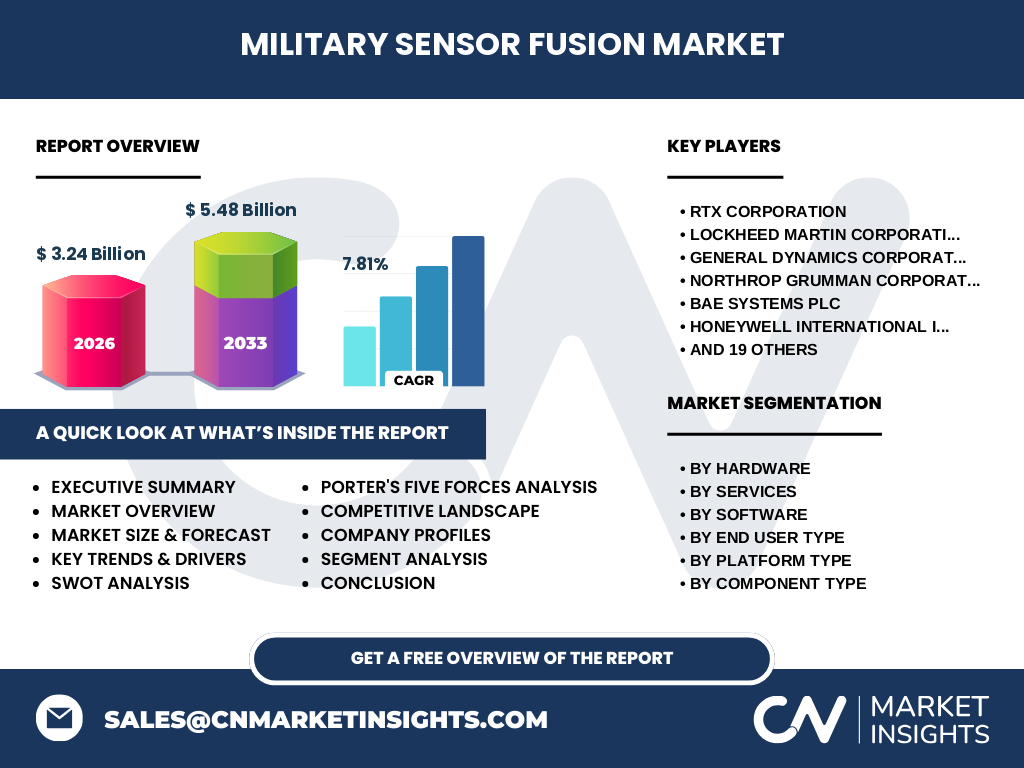
The Military Sensor Fusion Market encompasses the integration of data from disparate sources like radar, electro-optical, and LiDAR sensors to produce unified, timely tactical insights. Valued at 3.24 Billion in 2026, this sector is critical for modern defense architectures, enabling autonomous threat detection and accelerated decision-making across complex multi-domain operational theaters.
Structural Growth Drivers and Market Restraints
Growth is propelled by surging demand for real-time situational awareness and autonomous systems like unmanned aerial vehicles. However, our analysis indicates significant restraints, including stringent ITAR export controls, complex certification hurdles for safety-critical edge computing units, and the extreme logistical challenges of retrofitting legacy naval and ground combat platforms with modern data fusion software.
The Shift Toward AI-Driven Edge Computing in the Military Sensor Fusion Market
Defense forces are rapidly shifting toward artificial intelligence and machine learning analytics software embedded directly on platforms. Edge computing units are replacing centralized processing to minimize bandwidth bottlenecks in contested electromagnetic environments. This evolution favors technology innovators capable of delivering low-SWaP (Size, Weight, and Power) processing solutions for smart munitions and man-portable systems.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted semiconductor supply chains and delayed defense procurement schedules. Despite temporary halts in R&D and manufacturing, the recovery trajectory has been exceptionally robust, accelerated by geopolitical tensions that forced governments to prioritize modernization contracts for sensor integration and middleware platforms, reinforcing long-term market expansion.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high consolidation among tier-one primes like RTX Corporation, Lockheed Martin Corporation, and Northrop Grumman Corporation, who dominate large-scale platform integration. Meanwhile, specialized defense tech firms and research institutions capture niche value through advanced algorithmic development, forcing primes into strategic partnerships and acquisitions to maintain technological superiority.
Executive Summary of the Military Sensor Fusion Market Industry Trends
Our comprehensive analysis projects the Military Sensor Fusion Market to expand from 3.24 Billion in 2026 to 5.48 Billion by 2033, achieving a steady 7.81% CAGR. Accelerated digitization across military forces and rising adoption of unmanned systems serve as the core catalysts for this substantial valuation surge.
Market Forecast and Long-Term Trajectory through 2033
Driven by sustained defense budget allocations across NATO allies and Indo-Pacific nations, the market is poised for accelerated expansion. The trajectory from 2027 to 2033 reflects a compounding 7.81% CAGR, moving the sector from a 2026 baseline of 3.24 Billion toward the terminal forecast of 5.48 Billion as multi-domain battle management systems reach full operational capability.
Segmentation Analysis Across Hardware, Software, and Services
Market segmentation spans hardware (sensors, processors, communication links, storage), software (data fusion algorithms, AI analytics, middleware), and services (system integration, maintenance, training). Data fusion software and edge processors represent the highest-margin categories, driven by the intense computational demands of processing multispectral sensor inputs in real time.
Regional Market Analysis and Geographic Performance
Geographic performance is heavily concentrated in North America, anchored by major Department of Defense modernization initiatives. The Asia-Pacific region demonstrates the fastest growth rate due to escalating territorial disputes and naval fleet expansions. European markets are simultaneously prioritizing cross-border interoperability initiatives under frameworks managed by the European Defence Agency.
In-Depth Regional Review of Strategic Defense Hubs
North America retains the dominant market share, supported by dense clusters of defense contractors around key logistics hubs and R&D facilities. Concurrently, Asia-Pacific nations are rapidly upgrading their surveillance capabilities, integrating advanced acoustic, radar, and electro-optical sensors onto naval vessels and unmanned aerial vehicles to secure critical maritime choke points.
Company Profiles and Strategic Positioning
Industry leaders such as BAE Systems plc, Thales SA, and L3Harris Technologies Inc. leverage deep domain expertise to deliver turnkey sensor integration. European champions like Leonardo SpA and Saab AB focus on agile, modular avionics and naval combat management systems, positioning themselves favorably against US prime contractors in international export markets.
Porter's Five Forces Analysis of the Defense Sector
The Military Sensor Fusion Market exhibits moderate-to-high buyer power, as defense ministries dictate stringent specifications. However, threat of new entrants remains exceptionally low due to prohibitive capital expenditure requirements, classified security clearance mandates, and entrenched relationships between prime contractors and military procurement agencies.
SWOT Analysis of the Military Sensor Fusion Market
Strengths include unmatched situational awareness and high technological barriers to entry. Weaknesses involve vulnerability to supply chain shocks for rare earth materials used in sensors. Opportunities lie in expanding commercial dual-use applications, while threats stem from sophisticated cyber-attacks targeting proprietary data fusion algorithms and electronic warfare jamming.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing critical minerals for sensors, progressing through component manufacturers and software developers. Primes then integrate these elements into platforms before deployment by end-users like military forces and government bodies, with system integrators capturing substantial value during the testing and deployment phases.
Investment Insights and High-Potential Areas
Strategic investment should target firms specializing in artificial intelligence analytics software and resilient middleware platforms. Venture capital and private equity firms will find high-potential returns in scaling technologies that bridge legacy military hardware with next-generation edge computing capabilities, particularly in threat detection and autonomous navigation.
Conclusion and Key Takeaways for Market Stakeholders
The Military Sensor Fusion Market represents a vital pillar of modern defense transformation. With a projected valuation reaching 5.48 Billion by 2033, stakeholders must prioritize software-defined architectures and secure communication links to capitalize on accelerating procurement cycles and multi-domain operational mandates.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing public trade registries, defense budget appropriations documents, and primary stakeholder interviews with chief technology officers across top contractors. Secondary macroeconomic indicators and historical procurement cycles are modeled alongside expert panel consensus to ensure absolute market accuracy.
Scope of the Report and Coverage Parameters
This report covers global developments across hardware, software, and service segments within five primary end-user verticals from 2026 through 2033. Limitations include restricted access to classified black-budget military programs, focusing instead on publicly acknowledged defense modernization initiatives, export-approved technologies, and declared government procurement contracts.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity is characterized by strategic joint ventures between defense primes and pure-play AI firms aimed at accelerating sensor-to-shooter timelines. Notable announcements feature multi-million dollar contract awards for upgrading electronic warfare suites and deploying advanced middleware platforms across allied naval and air fleets.