What is the market overview and scope of the Military Cloud Computing Market?
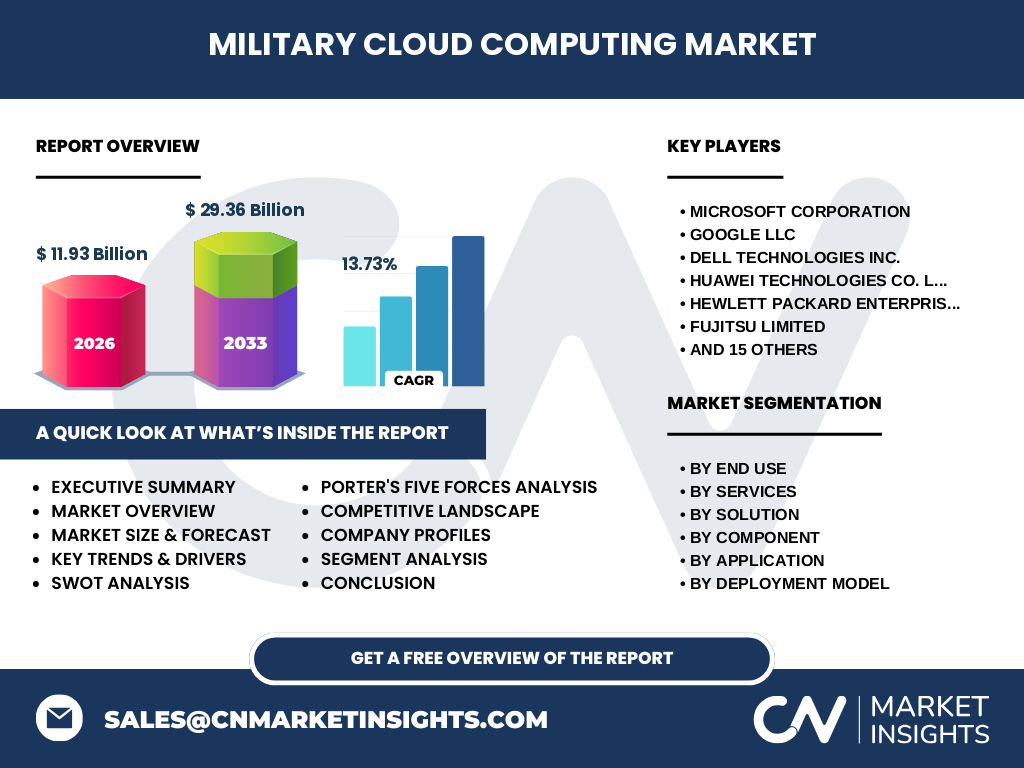
Our analysis indicates that the Military Cloud Computing Market reaches a valuation of 11.93 Billion in 2026. This sector encompasses tactical edge infrastructure, secure data storage, and artificial intelligence platforms utilized by defense agencies to modernize command and control operations.
What are the structural growth drivers and market restraints shaping the industry?
The market is driven by escalating demand for real-time threat intelligence and edge computing solutions. However, stringent compliance requirements and vulnerabilities to advanced cyberattacks serve as primary restraints, challenging system integration across legacy military hardware.
Emerging trends and growth patterns in the sector
The shift toward multi-cloud architectures and tactical containerization is accelerating across defense branches. Edge and tactical cloud solutions are gaining prominence, allowing troops to process data locally in disconnected environments without relying solely on centralized data centers.
How did the COVID-19 pandemic impact the industry and recovery trajectory?
The pandemic exposed vulnerabilities in legacy defense logistics, forcing an accelerated transition to remote collaboration tools and secure cloud infrastructure. Recovery has been robust, backed by urgent defense digitalization budgets aimed at securing supply chains and remote operational readiness.
Competitive benchmarking and strategic market dynamics
The landscape features intense rivalry among tech giants and defense contractors. Companies like Microsoft Corporation and Amazon Web Services AWS dominate hyperscale deployments, while Palantir Technologies Inc. and Booz Allen Hamilton Holding Corporation specialize in mission-critical analytics.
Executive summary of key findings
The Military Cloud Computing Market industry trends highlight rapid modernization, expanding at a robust CAGR of 13.73%. Driven by demand for advanced cybersecurity and data analytics, total market value is projected to surge significantly through the forecast period.
Market forecast from 2027 to 2033
Our research forecasts the market to expand from 2027 to 2033, reaching a projected valuation of 29.36 Billion by the end of the period. This trajectory reflects sustained long-term defense budget allocations toward cloud migration and AI integration.
Segmentation analysis across end use, services, and solutions
Segmentation spans end-use branches like the Army, Navy, Air Force, Space Force, and Defense Agencies. Offerings are categorized by solutions like Infrastructure As A Service and services such as Cloud Security Services, ensuring tailored tactical execution.
Geographic distribution and regional market performance
Regional performance is heavily concentrated in North America due to massive defense expenditure and early adoption of hyperscale cloud architectures. Meanwhile, the Asia-Pacific region displays high growth rates driven by rising geopolitical tensions and localized defense tech investments.
In-depth regional review of defense cloud deployments
North America maintains the largest market share, anchored by Department of Defense modernization initiatives. European nations are increasingly prioritizing sovereign cloud solutions, fostering partnerships with local defense primes to secure sensitive military intelligence.
Strategic positioning of leading enterprise profiles
Industry leaders leverage distinct strategic advantages. Google LLC and Oracle Corporation provide secure cloud environments, whereas General Dynamics Information Technology GDIT and Leidos Holdings Inc. integrate these platforms directly into defense contractor workflows.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate due to strict government procurement standards. Threat of new entrants remains low owing to high security clearance barriers, intense regulatory compliance, and the massive capital required for secure defense cloud infrastructure.
SWOT analysis of the defense cloud sector
Key strengths lie in unmatched data scalability and advanced AI analytics. Weaknesses involve complex migration paths for legacy systems. Opportunities emerge in tactical edge computing, while severe threats stem from sophisticated state-sponsored cyber espionage campaigns.
Value chain analysis from raw materials to end-users
The value chain flows from semiconductor silicon manufacturers and hardware component providers to hyperscale cloud builders and defense integrators. Ultimate end-users include operational commanders across the Navy and Air Force utilizing real-time intelligence feeds.
Investment insights and high-potential areas
High-potential investment areas center on Cybersecurity And Threat Intelligence Solutions and Edge And Tactical Cloud Solutions. Stakeholders should prioritize funding firms with proprietary zero-trust architectures tailored for austere operational environments.
Conclusion and key takeaways for market participants
The Military Cloud Computing Market analysis confirms that cloud integration is no longer optional for modern defense forces. Companies combining robust cybersecurity with scalable Platform As A Service solutions are best positioned to capture long-term military contracts.
Research methodology for baseline estimates
Our baseline estimates are triangulated by combining trade registry data, primary stakeholder interviews with defense procurement officers, and secondary macroeconomic indicators from defense ministries and global aerospace databases to ensure rigorous accuracy.
Scope of the report and coverage parameters
This report covers global military cloud adoption across public, private, and hybrid deployment models from 2026 to 2033. Excluded from this scope are commercial aviation IT systems and non-defense governmental cloud deployments.
Recent developments, partnerships, and strategic moves
Recent industry dynamics feature major cloud providers securing multi-billion-dollar defense contracts. Strategic partnerships between firms like Thales S.A., L3Harris Technologies Inc., and hyperscalers aim to deliver sovereign, resilient tactical clouds for allied military forces.