Market overview and structural significance of the Cold Chain Micro-Fulfillment Hub Networks Market
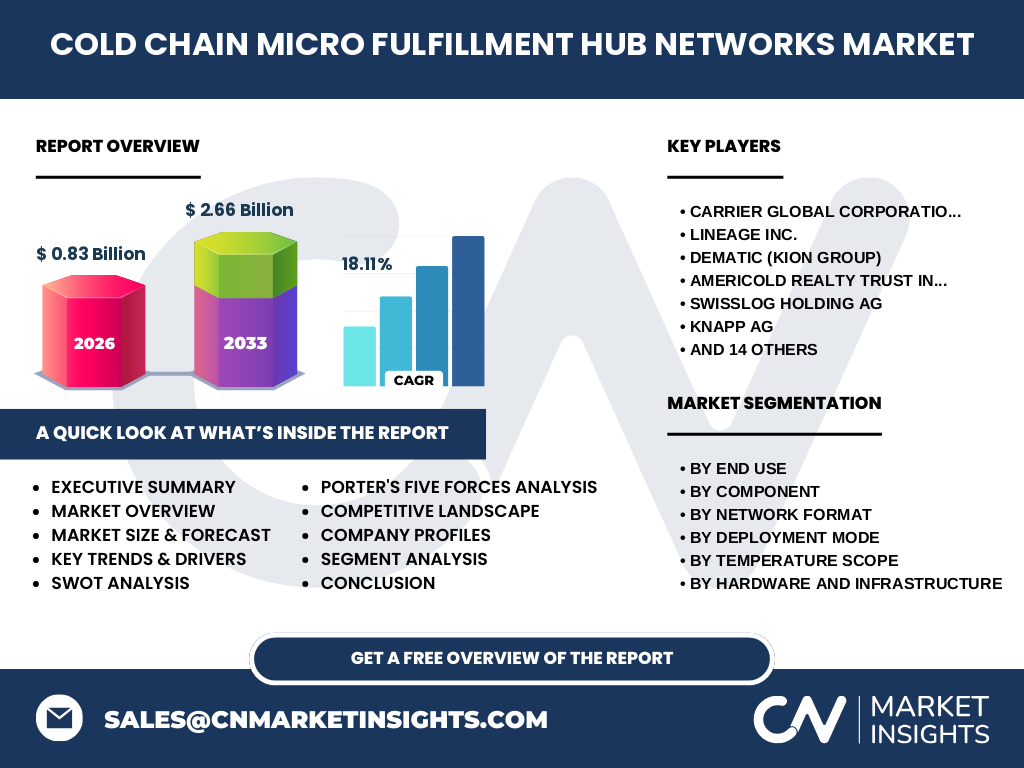
Our analysis indicates that the Cold Chain Micro-Fulfillment Hub Networks Market valued at 0.83 Billion in 2026, serves as the critical infrastructural backbone for hyper-local perishable logistics. Complying with stringent FDA and WHO cold chain mandates, these ultra-dense networks deploy automated storage and retrieval systems directly into urban footprints to solve the last-mile refrigeration dilemma.
Structural Growth Drivers and Market Restraints
The market is propelled by exploding demand for rapid grocery delivery and temperature-sensitive pharmaceuticals. However, our research highlights severe capital expenditure hurdles and zoning restrictions for urban industrial refrigeration. Industry leaders like Carrier Global Corporation and Thermo King are countering these restraints by engineering modular, low-noise thermal packaging systems.
Emerging Industry Trends and Evolution Patterns
The shift toward automated urban nodes represents a defining market shift. Integrating advanced internet of things monitoring systems and predictive analytics platforms allows operators like Fabric (CommonSense Robotics) to eliminate spoilage risks during peak quick-commerce demand windows in congested metropolitan centers.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic irrevocably altered consumer behavior, surging e-grocery adoption and stress-testing legacy supply chains. Post-COVID recovery has catalyzed aggressive investments in hybrid city network models, with cold chain operators aggressively upgrading cloud-based logistics platforms to maintain resilient inventory visibility.
Competitive Landscape and Strategic Market Concentration
Market concentration is intensifying as global real estate investment trusts and automation giants converge. Americold Realty Trust Inc. and Lineage Inc. dominate large-scale storage, while specialists like AutoStore AS and Dematic (KION Group) provide the automated grid infrastructure essential for dense urban micro-hubs.
Executive Summary of the Cold Chain Micro-Fulfillment Hub Networks Market
Priced for explosive expansion, the Cold Chain Micro-Fulfillment Hub Networks Market industry trends reveal an undeniable trajectory toward 2.66 Billion by 2033 at an 18.11% CAGR. Urbanization and consumer intolerance for thawed perishables make these localized automated nodes non-negotiable for modern retail.
Market Forecast and Long-Term Valuation Dynamics from 2027 to 2033
Our proprietary financial modeling projects rapid market scaling from 2027 through 2033, culminating at a 2.66 Billion valuation. This growth is sustained by an impressive 18.11% CAGR, driven by heavy adoption of multi-temperature grocery hubs and autonomous material handling equipment across secondary cities.
Segmentation Analysis Across End-Use, Components, and Network Formats
The market fractures across five core pillars: end-use (grocery, pharmacy), component types, deployment modes, temperature scopes, and network formats. Stand-alone urban cold micro-fulfillment nodes and dark store cold hubs represent the fastest-growing segments, heavily reliant on automated storage and retrieval systems.
Geographic Distribution and Regional Performance Overview
Regional performance is dictated by urban density and stringent food safety regulations. North America and Europe currently lead deployment rates, while Asia-Pacific emerges as the high-growth frontier due to massive quick commerce food delivery expansion in mega-cities requiring specialized fresh produce hubs.
In-Depth Regional Review of High-Density Markets
North American markets prioritize pharmaceutical and health retail compliance, whereas European hubs focus heavily on sustainable, energy-efficient refrigeration units. Regional logistics providers face strict municipal emissions laws, forcing a rapid transition toward electric refrigerated transport equipment.
Company Profiles and Strategic Positioning of Leading Market Participants
Industry stalwarts like Swisslog Holding AG, KNAPP AG, and NewCold Advanced Cold Logistics B.V. leverage proprietary warehouse management software to optimize dense urban footprints. Meanwhile, regional operators like Snowman Logistics Limited and Coldman Logistics Pvt. Ltd. secure dominant footholds in emerging southern hemisphere markets.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to specialized refrigeration engineering requirements, while buyer power is high among major grocery consolidators. The threat of new entrants is mitigated by severe initial capital outlays required for advanced blast chillers and automated conveying infrastructure.
SWOT Analysis of the Cold Chain Micro-Fulfillment Sector
Key strengths lie in unmatched delivery speed and reduced spoilage rates. Weaknesses involve high energy consumption profiles. Opportunities abound in pharmaceutical cold-chain compliance, while threats stem from volatile energy pricing and unstable refrigerant supply chains.
Value Chain Analysis from Raw Materials to End-User Delivery
The value chain originates with raw thermal insulation materials and compressor component manufacturers. It flows through automated equipment integrators like Culina Group Limited and RLS Logistics Inc. before terminating at consumer-facing dark store cold hubs managed by platforms like Smart Warehousing LLC.
Investment Insights and High-Potential Growth Areas
Strategic investors should target software-driven cloud connected networked hubs and automated storage infrastructure. Companies mastering energy-autonomous refrigeration and AI-powered route optimization software will capture outsized returns throughout the 2027-2033 forecast window.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Cold Chain Micro-Fulfillment Hub Networks Market analysis confirms that localized, automated temperature control is the future of perishables. Stakeholders must embrace modular warehouse structures and cloud-based logistics platforms to secure long-term market viability.
Research Methodology and Baseline Estimation Techniques
Our baseline estimates are triangulated by combining customs trade registry data, primary stakeholder interviews with executives at firms like ORBCOMM Inc. and Constellation Cold Logistics, and secondary macroeconomic indicators tracking urban real estate and retail cold-chain spending.
Scope of the Report and Operational Limitations
This report covers global deployment metrics across hardware, software, and storage systems from 2026 through 2033. Excluded from this specific scope are long-haul intermodal cold chain transit networks and non-refrigerated ambient micro-fulfillment centers lacking thermal integrity.
Recent Developments, Strategic Partnerships, and Corporate Innovations
Recent market activity is dominated by joint ventures between automated hardware suppliers and regional logistics providers. Key players like FreezPak Logistics LLC and GND Solutions have launched integrated IoT monitoring systems designed to slash energy waste in urban cold rooms.