What is the scope and industry significance of the Military Semiconductor Market?
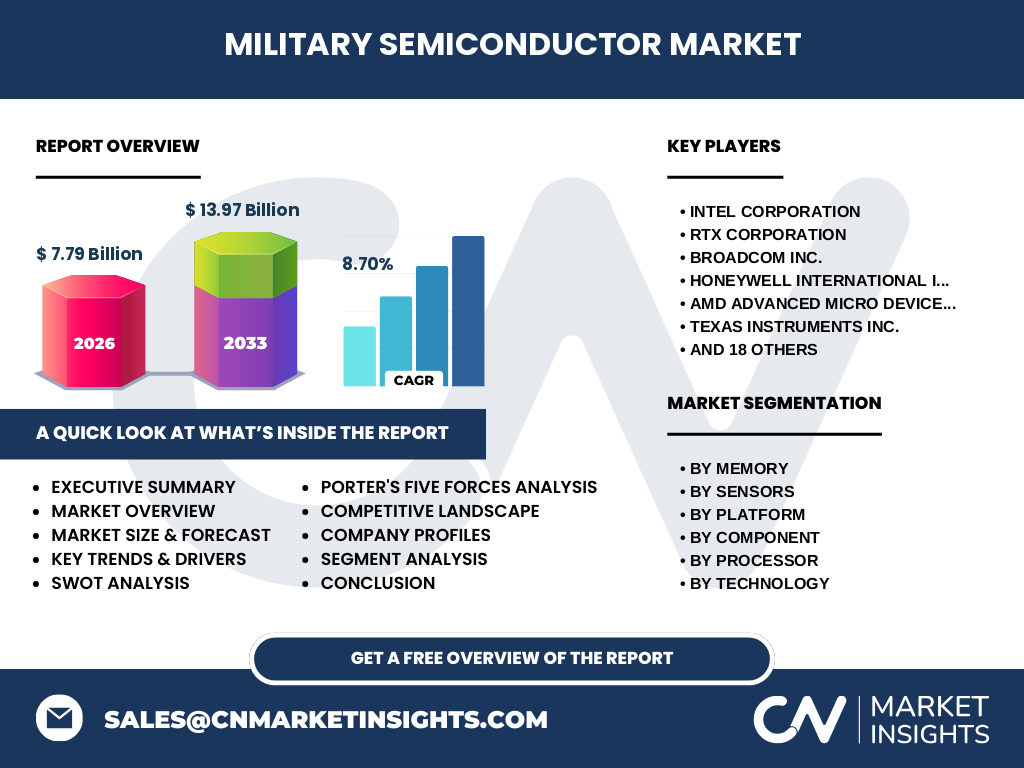
Our analysis indicates that the Military Semiconductor Market underpins critical defense infrastructure globally. Valued at 7.79 Billion in 2026, this sector encompasses hardened microelectronics, radiation-tolerant processors, and specialized sensors deployed across airborne, naval, land, and space domains, governed by strict ITAR and EAR export controls.
Structural Growth Drivers and Market Restraints
The market is propelled by a CAGR of 8.70%, driven by surging demand for AI-enabled battlefield analytics and phased-array radar modernization. However, severe supply chain bottlenecks for raw materials like high-purity silicon carbide (SiC) and gallium nitride (GaN), alongside prolonged fab lead times, act as primary restraints limiting rapid production scaling.
Emerging Technological Shifts
The transition toward wide-bandgap semiconductors such as Gallium Nitride (GaN) and Silicon Carbide (SiC) defines current industry trends. These materials offer superior thermal management and high-frequency performance essential for advanced Electronic Warfare (EW) and next-generation radar systems, favoring agile merchant foundries over traditional legacy suppliers.
Pandemic Aftermath and Recovery Dynamics
The COVID-19 pandemic severely disrupted wafer fabrication schedules and test-facility operations, creating defense-grade component shortages. Recovery has been spearheaded by targeted government interventions like the US CHIPS Act, accelerating domestic packaging initiatives and bolstering supply chain resilience for critical analog and logic integrated circuits.
Competitive Benchmarking and Market Concentration
Industry concentration remains high among vertically integrated aerospace primes and specialized semiconductor houses. Market leaders like Intel Corporation, RTX Corporation, and Texas Instruments Inc. dominate through proprietary rad-hard design methodologies, deep DoD relationships, and robust intellectual property portfolios guarding high-performance processors.
Executive Summary of Strategic Findings
Our comprehensive research projects the market to expand from 7.79 Billion in 2026 to 13.97 Billion by 2033. Strategic growth is anchored in heightened geopolitical tensions and accelerated digital transformation across naval combat management and airborne avionics platforms, requiring sustained R&D investment.
Long-Term Market Forecast from 2027 to 2033
Driven by robust defense budgets and space-based asset expansion, the sector is set to achieve a consistent 8.70% CAGR through 2033, culminating in a market valuation of 13.97 Billion. Sustained adoption of Field Programmable Gate Arrays (FPGAs) will heavily influence this trajectory.
Segmentation Analysis by Component and Technology
The ecosystem is segmented by components including Memory, Processors, Analog ICs, Logic ICs, Discrete Power Devices, and Sensors. Technological adoption heavily favors Silicon Carbide (SiC) and Gallium Nitride (GaN) due to their unmatched power efficiency in demanding airborne and ground tactical communication environments.
Geographic Distribution and Regional Performance
North America commands the largest share due to massive defense outlays and domestic fabrication mandates. Meanwhile, the Asia-Pacific region demonstrates the fastest growth velocity, fueled by escalating indigenous military modernization programs in nations like India and South Korea, coupled with localized packaging hubs.
In-Depth Regional Review of Defense Electronics
North American procurement focuses heavily on multi-domain battle management systems, whereas European markets prioritize interoperability and electronic countermeasure upgrades. Concurrently, Asia-Pacific military investments center on advanced naval sonar arrays and missile guidance sensors, heavily involving regional foundries.
Strategic Positioning of Leading Industry Players
Key market participants leverage distinct operational strategies. Broadcom Inc. and AMD Advanced Micro Devices Inc. focus on high-throughput compute engines, while Infineon Technologies AG and ON Semiconductor Corporation specialize in high-reliability discrete power devices and radiation-hardened power management integrated circuits.
Porter's Five Forces Analysis
Supplier power is moderate to high, restricted by specialized foundry access and stringent defense qualification standards. Threat of substitutes remains exceptionally low given the rigorous environmental, thermal, and radiation-tolerance specifications required for military-grade semiconductors that commercial-off-the-shelf components rarely meet.
SWOT Analysis of the Defense Semiconductor Sector
Key strengths include captive defense revenue streams and mission-critical reliability. Weaknesses involve high NRE (Non-Recurring Engineering) costs. Opportunities abound in autonomous drone swarms, while threats manifest as escalating cyber-espionage and intellectual property theft targeting fabless design houses.
Value Chain Analysis from Raw Materials to End-Users
The value chain starts with ultra-pure wafer extraction (Silicon, GaAs, GaN), moves through IC design and wafer fabrication, and progresses to specialized packaging and rigorous MIL-STD testing before final integration into radar and communication subsystems by primes like Northrop Grumman Corporation and BAE Systems Plc.
Investment Insights and High-Potential Areas
High-potential investment pockets center on advanced packaging facilities and radiation-hardened mixed-signal components. Venture capital and defense primes are aggressively backing startups specializing in Gallium Nitride power amplifiers to capture surging demand within electronic warfare and satellite communication payloads.
Conclusion and Definitive Takeaways
With the market scaling to 13.97 Billion by 2033 at an 8.70% CAGR, stakeholders must prioritize supply chain sovereignty and embrace wide-bandgap materials. Companies that successfully navigate export controls and secure domestic foundry capacity will capture outsized defense contracting rewards.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with defense procurement officers, and secondary macroeconomic indicators from defense ministries and multilateral trade organizations to ensure absolute data fidelity.
Scope of the Report and Analytical Limitations
This report covers global military semiconductor deployments across airborne, naval, land, and space domains, tracking components from discrete power devices to complex microprocessors. Exclusions apply to strictly commercial aerospace avionics and dual-use consumer electronics lacking formal military-grade certification.
Recent Developments and Strategic Industry Moves
Recent industry momentum highlights strategic foundry partnerships and product launches aimed at defense resilience. Firms like Microchip Technology Inc. and Qorvo Inc. have announced expanded rad-hard manufacturing lines to support next-generation low-earth-orbit military satellite constellations and tactical edge-computing nodes.