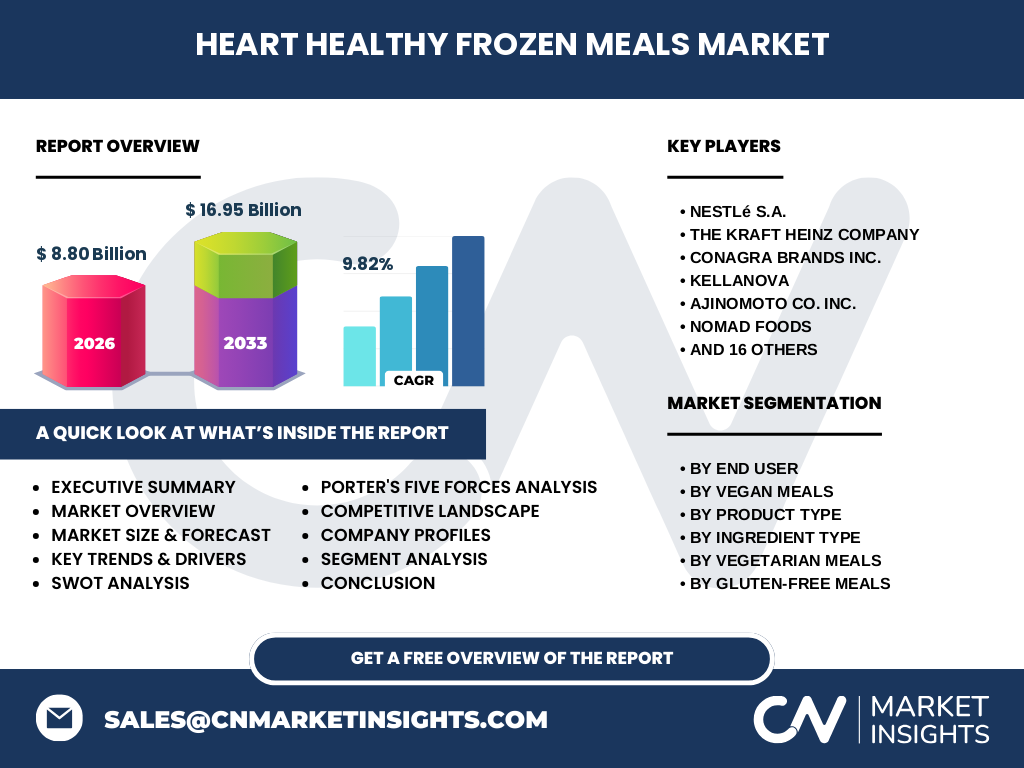
Market overview of the Heart-Healthy Frozen Meals Market
Our analysis indicates the Heart-Healthy Frozen Meals Market achieves a valuation of 8.80 Billion in 2026. This sector encompasses nutrient-dense, portion-controlled convenience foods formulated by the FDA and AHA dietary guidelines, mitigating cardiovascular risks via strict sodium, fat, and cholesterol limits.
Key market drivers, restraints, challenges, and opportunities shaping the Heart-Healthy Frozen Meals Market
Surging cardiovascular disease prevalence acts as a primary catalyst, while high cold-chain logistics costs restrain expansion. Regulatory scrutiny from the USDA creates compliance hurdles, yet lucrative opportunities emerge in functional product innovations.
Emerging trends and growth patterns in the Heart-Healthy Frozen Meals Market
Industry trends highlight clean-label processing and transparent nutritional profiling. Consumers increasingly demand organic and allergen-free profiles, prompting brands like Amy's Kitchen Inc. and Caulipower LLC to reformulate traditional frozen offerings into functional health solutions.
COVID-19 impact analysis and recovery trajectory for the Heart-Healthy Frozen Meals Market
The pandemic accelerated retail frozen food adoption due to pantry-loading behaviors. Post-COVID recovery trajectories remain robust, sustained by permanent shifts toward home-centric wellness management and preventative dietary care.
Competitive benchmarking and strategic dynamics
The market features high consolidation among multinational conglomerates and agile disruptors. Major players like Nestlé S.A. and Conagra Brands Inc. leverage vast distribution networks to outpace niche competitors.
Executive summary of key findings
Driven by rising health consciousness, the Heart-Healthy Frozen Meals Market is projected to reach 16.95 Billion by 2033, expanding at a remarkable CAGR of 9.82% from 2027.
Market forecast from 2027 to 2033
Based on our research, steady upward momentum will scale the market from its 2026 baseline of 8.80 Billion to 16.95 Billion by 2033, reflecting an aggressive 9.82% CAGR driven by aging populations.
Segmentation analysis across end users and product types
Segmentation spans end users (Adults, Children, Elderly) and product categories like Vegetarian, Non-Vegetarian, Vegan, and Gluten-Free meals, alongside specialized ingredient matrices focusing on whole grains and lean proteins.
Regional market analysis and geographic distribution
Geographic performance shows North America leading consumption due to established retail cold chains, while Europe follows closely driven by stringent European Food Safety Authority wellness labeling initiatives.
In-depth regional review of high-growth territories
North American markets dominate through advanced supermarket infrastructure, whereas Asia-Pacific regions exhibit accelerated adoption due to rising urban disposable incomes and chronic lifestyle disease awareness.
Company profiles and strategic positioning of leading enterprises
Industry leaders like The Kraft Heinz Company and Nomad Foods deploy aggressive acquisition strategies to capture health-focused segments, integrating sustainable sourcing and clean-label processing into their supply chains.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry remains intense, with moderate supplier power constrained by agricultural commodity availability. Threat of substitution is low given the specialized functional nature of these cardiac-focused meals.
SWOT analysis of the sector
Strengths include established retail distribution; weaknesses involve high refrigeration overheads. Opportunities lie in personalized nutrition, while threats stem from shifting raw agricultural commodity pricing.
Value chain analysis from raw materials to end-users
The value chain flows from certified organic agricultural producers through temperature-controlled manufacturing plants, passing via major logistics hubs to supermarkets, hypermarkets, and direct-to-consumer online channels.
Investment insights and high-potential areas
High-potential capital allocation targets plant-based and diabetic-friendly functional lines. Investors should prioritize brands utilizing advanced IQF (Individually Quick Frozen) technology to preserve micronutrients.
Conclusion and strategic takeaways
The Heart-Healthy Frozen Meals Market represents an essential growth frontier, bridging consumer demand for convenience with rigorous clinical nutritional standards through 2033.
Research methodology and data triangulation
Our analysis triangulates data via primary executive interviews, trade registry metrics from customs databases, and secondary macroeconomic indicators to establish reliable baseline estimates for 2026.
Scope of the report and coverage parameters
This report covers global revenue performance, volume metrics, and competitive landscapes from 2027 to 2033, excluding localized unpackaged culinary services and non-frozen dietary alternatives.
Recent developments, partnerships, and strategic moves
Recent milestones feature strategic co-packing partnerships by companies like Saffron Road and new product rollouts from Daily Harvest targeting functional low-sodium consumer segments.