Market Overview: Defining the Scope of the Defense Semiconductor Market
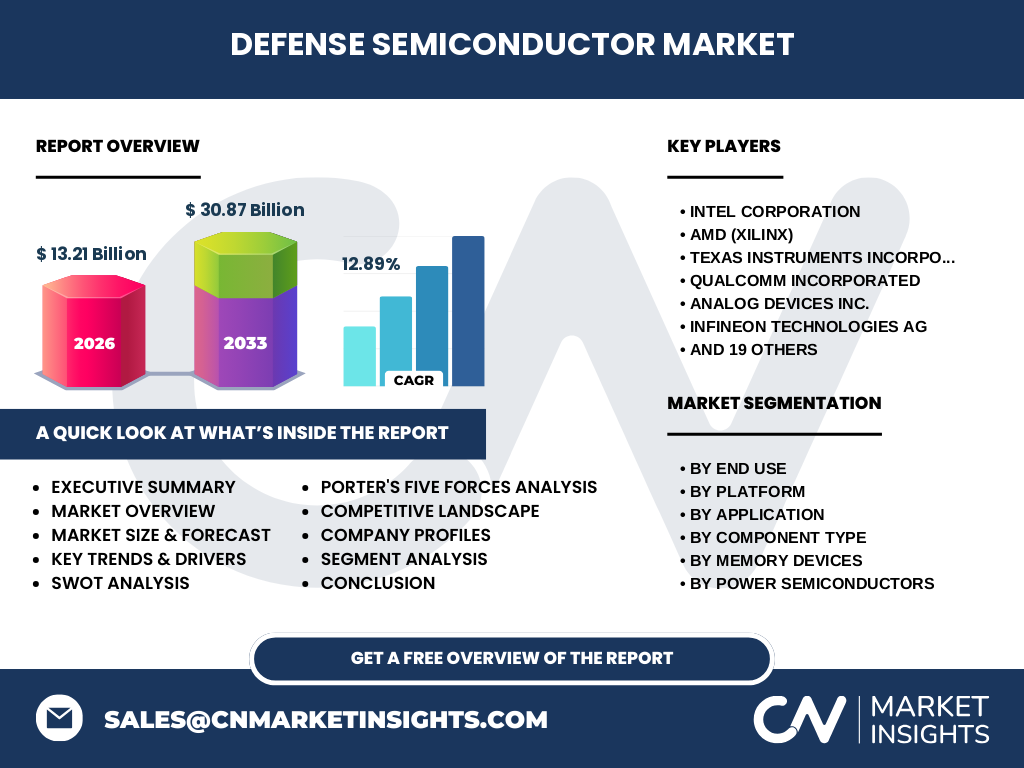
Our analysis indicates that the Defense Semiconductor Market encompasses specialized microelectronics deployed in military, homeland security, and space defense applications. Valued at 13.21 Billion in 2026, this sector underpins critical infrastructure requiring extreme radiation hardness, wide bandgap raw materials like silicon carbide, and compliance with stringent ITAR regulations.
Structural Growth Drivers and Market Restraints
The market is propelled by a 12.89% CAGR driven by escalating geopolitical tensions and modernization of radar and electronic warfare systems. However, restrictive export controls from the Bureau of Industry and Security and lengthy semiconductor fabrication lead times continue to pose substantial logistical hurdles for defense primes.
Emerging Technological Trends in Military Microelectronics
Gallium nitride and advanced packaging are revolutionizing high-frequency radio frequency and microwave components. Market leaders like Qorvo and Wolfspeed are capitalizing on this shift, delivering power amplifiers that withstand extreme thermal thresholds demanded by modern airborne and naval sensor arrays.
Pandemic Aftershocks: COVID-19 Impact on Defense Supply Chains
Based on our research, the pandemic exposed severe vulnerabilities in onshore fabrication for defense-grade integrated circuits. The recovery trajectory has been heavily shaped by legislative interventions such as the CHIPS Act, securing localized foundry access for critical analog and mixed signal integrated circuits.
Competitive Benchmarking and Industry Concentration
The competitive landscape features high consolidation among aerospace primes and specialized semiconductor vendors. Companies like RTX Corporation and Northrop Grumman vertically integrate advanced microprocessors, while merchant suppliers such as Texas Instruments and Analog Devices maintain dominant positions through proprietary rad-hard libraries.
Executive Summary of the Defense Semiconductor Market Report
This comprehensive report projects the Defense Semiconductor Market to expand significantly, reaching 30.87 Billion by 2033. Strategic growth is concentrated in space-based architectures and missile guidance systems, favoring firms with robust domestic foundry ecosystems and advanced digital signal controller portfolios.
Long-Term Market Forecast from 2027 to 2033
Driven by sustained defense budgets and multi-year military procurement cycles, the sector will scale rapidly from its 2026 baseline. Our data suggests that space defense and electronic warfare upgrades will outpace legacy land-based platforms, capturing disproportionate revenue share through the forecast window.
Comprehensive Segmentation Analysis
The market breaks down across diverse operational parameters:
- End Use: Military, Homeland Security, Space Defense
- Platform: Air, Land, Naval, Space Based
- Application: Radar, Communications, Electronic Warfare, Avionics, Missile Guidance
- Component: Microprocessors, Memory, Analog/Mixed Signal, RF/Microwave, Power Semiconductors
Geographic Distribution and Regional Market Performance
North America commands the largest revenue share, underpinned by the Department of Defense spending and domestic foundries like GlobalFoundries. Meanwhile, the Asia-Pacific region demonstrates the fastest growth trajectory due to escalating naval modernization programs and localized semiconductor self-sufficiency initiatives in Taiwan and South Korea.
In-Depth Regional Review of Defense Microelectronics Hubs
European markets are prioritizing sovereign radar and secure communication systems through the European Defence Fund, directly benefiting regional players like Infineon and STMicroelectronics. Simultaneously, U.S. procurement remains heavily focused on secure microcontrollers and radiation-hardened memory devices.
Strategic Positioning of Key Industry Participants
Industry titans like Intel Corporation and AMD (Xilinx) supply high-performance computing nodes for tactical edge processing, while specialized players like Lattice Semiconductor dominate reprogrammable logic solutions. Microchip Technology and NXP Semiconductors maintain strongholds in secure, long-lifecycle microcontrollers tailored for harsh military environments.
Porter's Five Forces Assessment of Competitive Pressures
Bargaining power of buyers is exceptionally high, dominated by sovereign defense agencies enforcing strict mil-spec qualifications. Conversely, the threat of new entrants remains low due to prohibitive capital expenditures for fabrication facilities and rigorous security clearances required to handle classified defense intellectual property.
SWOT Analysis of the Defense Semiconductor Ecosystem
Strengths lie in extreme reliability and proprietary rad-hard designs. Weaknesses involve long product development cycles. Opportunities emerge from commercial off-the-shelf adoption, while threats center on rare earth material supply chain bottlenecks and geopolitical trade restrictions.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from polysilicon and gallium nitride raw material extraction through specialized wafer fabrication by foundries like WIN Semiconductors, culminating in system integration by primes like BAE Systems. Each node requires rigorous testing to meet MIL-STD certification standards before deployment.
Strategic Investment Insights and High-Potential Areas
Investors should target pure-play providers of wide bandgap power semiconductors and radiation-hardened flash memory. Companies integrating artificial intelligence accelerators into tactical edge nodes represent high-alpha opportunities as autonomous drone swarms and uncrewed naval vessels receive priority defense funding.
Conclusion and Critical Industry Takeaways
The trajectory toward 30.87 Billion by 2033 underscores the indispensable role of microelectronics in modern national security. Stakeholders must navigate complex export controls and prioritize resilient, localized supply chains to capture expanding opportunities in electronic warfare and missile guidance.
Robust Research Methodology for Baseline Triangulation
Our findings are synthesized by triangulating bottom-up trade registry data from customs authorities, primary qualitative interviews with Chief Technology Officers across prime contractors, and top-down macro-economic defense budget allocations from agencies like the Stockholm International Peace Research Institute.
Scope of the Report and Analytical Parameters
This report evaluates the global Defense Semiconductor Market across specified component, platform, application, and end-use vectors from 2026 through 2033. Excluded from this scope are commercial aerospace electronics and consumer-grade dual-use components lacking explicit military qualification certifications.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by aggressive fab expansion partnerships and strategic acquisitions. Companies like Skyworks Solutions and Teledyne Technologies have forged critical foundry agreements to secure dedicated capacity for gallium arsenide and high-reliability analog components amid surging global defense demand.