What is the market overview and industry significance of the Reusable Sterilization Container Systems Market?
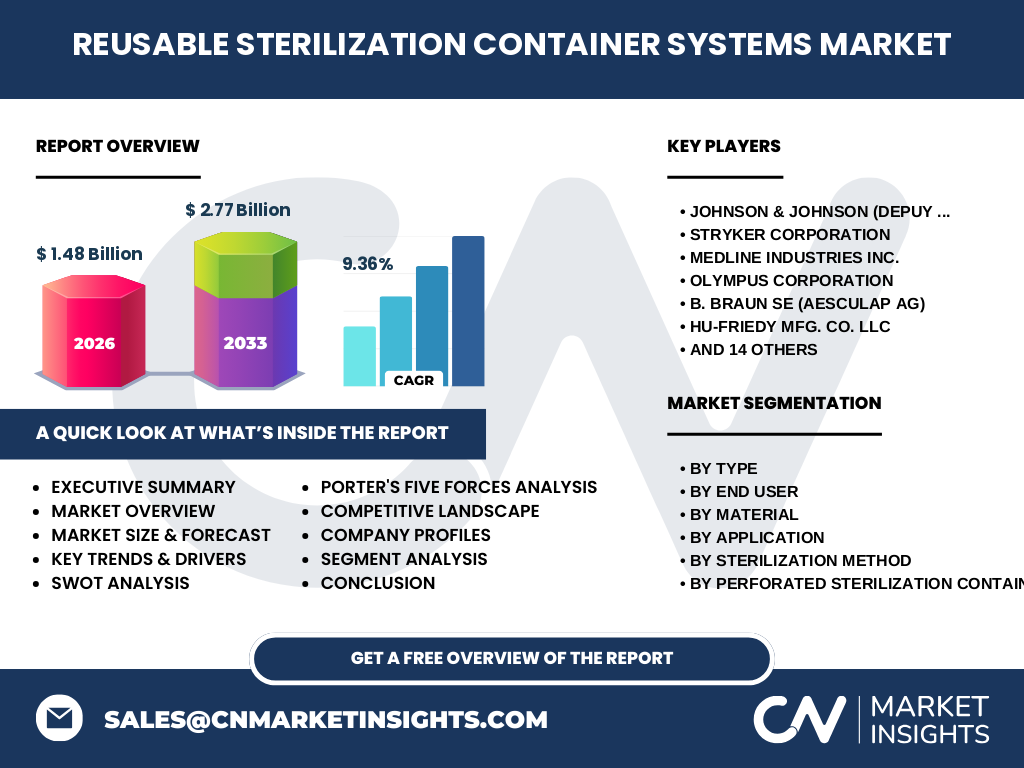
Our analysis indicates that the Reusable Sterilization Container Systems Market is valued at $1.48 Billion in 2026. These rigid containment solutions are critical for maintaining the sterility of surgical instruments from central processing departments to the operating room, replacing traditional sterile-wrap methods to minimize hospital-acquired infections and reduce medical waste in compliance with FDA and ISO standards.
Structural Growth Drivers and Market Restraints
The market is propelled by a rising volume of complex surgical procedures and stringent hospital hygiene protocols. Key restraints include the high initial capital expenditure required for premium aluminum and stainless steel containers, alongside stringent cleaning validation protocols mandated by regulatory bodies like the AAMI and FDA.
Emerging trends and growth patterns in the industry
Industry trends highlight a rapid shift toward filter-based perforated and valve-based perforated container systems that enhance steam penetration and drying efficiency. Healthcare facilities increasingly demand modular designs compatible with advanced hydrogen peroxide plasma sterilization to protect delicate micro-surgical tools.
How did the COVID-19 pandemic impact the Reusable Sterilization Container Systems Market?
The pandemic caused severe supply chain bottlenecks for medical-grade aluminum and stainless steel raw materials, delaying central sterile processing upgrades. However, the subsequent recovery trajectory accelerated hospital investments in robust, reusable infection control assets to mitigate single-use blue wrap shortages during elective surgery surges.
Competitive Benchmarking and Major Market Players
Market concentration is moderately high, dominated by multinational heavyweights like Johnson & Johnson (DePuy Synthes), Stryker Corporation, Getinge AB, and B. Braun SE (Aesculap AG). These leaders leverage extensive hospital distribution networks and proprietary container locking mechanisms to secure long-term group purchasing organization contracts.
Executive Summary of the Reusable Sterilization Container Systems Market
Our research projects the Reusable Sterilization Container Systems Market to expand from $1.48 Billion in 2026 to $2.77 Billion by 2033, registering a robust 9.36% CAGR. This growth is underpinned by escalating hospital investments in sustainable surgical instrument protection and stringent compliance with sterile processing regulations.
Market Forecast and Long-Term Projections (2027 to 2033)
Driven by a steady 9.36% CAGR, market revenue will climb from the 2026 baseline to reach $2.77 Billion by 2033. This expansion is supported by accelerated infrastructure development across ambulatory surgery centers and rising adoption of automated washer-disinfectors in sterile processing departments.
Segmentation Analysis: Types, Materials, End Users, and Applications
The market segments by type into perforated and non-perforated systems; by material into stainless steel, aluminum, plastic, and composite materials; by end user spanning hospitals, ambulatory surgery centers, diagnostic centers, and clinics; and by application covering surgical instrument storage, instrument transportation, sterile processing, and medical device protection.
Regional market analysis and geographic distribution
North America commands the largest market share, driven by stringent CDC and AAMI guidelines coupled with high healthcare expenditure. Meanwhile, the Asia-Pacific region demonstrates the fastest growth trajectory, propelled by massive hospital infrastructure modernization initiatives in China, Japan, and India.
In-depth Regional Review of High-Growth Healthcare Hubs
European markets prioritize sustainable, autoclavable polymer and anodized aluminum containers to meet strict EU Medical Device Regulation (MDR) standards. In contrast, emerging markets in Latin America and the Middle East are upgrading from traditional blue wrap to rigid container systems to reduce long-term central sterile processing operational costs.
Company Profiles and Strategic Positioning of Leading Firms
Firms like Olympus Corporation, Medline Industries Inc., and Fortive Corporation (Advanced Sterilization Products) focus on seamless integration with low-temperature sterilization modalities. Specialized players such as Case Medical Inc. and Aygun Surgical Instruments differentiate themselves through innovative container identification tracking and tamper-evident security seals.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to standardized aerospace-grade aluminum and stainless steel sourcing. Competitive rivalry is fierce among established medical device manufacturers, while the threat of substitution is low given the clinical necessity of rigid containers over disposable wraps for heavy orthopedic trays.
SWOT Analysis of the Reusable Sterilization Container Systems Market
Strengths include exceptional durability and lower lifecycle costs compared to single-use wraps. Weaknesses involve high initial outlays. Opportunities lie in smart container RFID tracking integration, while threats stem from strict regulatory audits and alternative packaging innovations.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing medical-grade stainless steel and aluminum, followed by precision stamping and anodizing manufacturers. Finished goods flow through specialized medical distributors and GPO contracts to reach hospital central processing units and ambulatory surgical centers.
Investment Insights and High-Potential Growth Areas
Investors should target manufacturers incorporating IoT-enabled RFID tracking tags and sustainable composite materials. Companies offering modular tray inserts compatible with both steam and hydrogen peroxide plasma sterilization represent prime acquisition targets for major healthcare conglomerates.
Conclusion and Key Strategic Takeaways
The Reusable Sterilization Container Systems Market represents a highly lucrative, infection-control-critical sector primed to reach $2.77 Billion by 2033. Success hinges on regulatory compliance, material innovation, and strategic alignment with hospital sustainability mandates aimed at reducing surgical waste.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with chief sterile processing nurses, and secondary macroeconomic indicators from global healthcare ministries and surgical volume databases.
Scope of the Report and Analytical Limitations
This report covers global revenue performance for reusable sterilization container systems across specified material, type, application, and end-user segments from 2026 to 2033. Limitations include localized pricing variations driven by regional healthcare reimbursement policies and varying hospital procurement cycles.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry moves feature key players launching lightweight, anodized aluminum containers with integrated antimicrobial coatings. Strategic mergers and OEM distribution partnerships among firms like KLS Martin Group, Shinva Medical Instruments, and Getinge AB aim to expand footprint in emerging healthcare economies.