Market overview — definition, scope, and industry significance of Compression Boots Market
Our analysis indicates that the Compression Boots Market encompasses specialized medical and wellness devices designed to enhance blood circulation and lymphatic drainage through pneumatic or static pressure. Valued at $2.38 Billion in 2026, this sector is highly significant across both clinical recovery wards and elite athletic training facilities, utilizing medical-grade TPU fabrics and precise microcontroller electronics.
Key market drivers, restraints, challenges, and opportunities shaping Compression Boots Market
Growth is heavily propelled by rising incidences of deep vein thrombosis (DVT) and surging sports recovery expenditures. However, strict FDA and CE medical device clearance mandates act as regulatory hurdles. Opportunities abound in portable, rechargeable sequential compression boots for home care.
Emerging trends and growth patterns in Compression Boots Market
The market is witnessing a major shift toward programmable and gradient intermittent pneumatic compression boots integrated with Bluetooth telemetry. Manufacturers like Therabody Inc. and Hyperice Inc. are dominating consumer mindshare by linking pneumatic hardware to smartphone apps, optimizing pressure cycles for custom athletic rehabilitation.
COVID-19 impact analysis — how the pandemic affected Compression Boots Market and the recovery trajectory
The pandemic initially severely disrupted supply chains for medical-grade polyurethane and pneumatic valves originating from key Asian manufacturing hubs. Conversely, post-COVID spikes in elective orthopedic surgeries and a heightened consumer focus on at-home wellness dramatically accelerated the recovery trajectory for home care compression systems.
Competitive landscape — major players, market concentration, and strategic dynamics
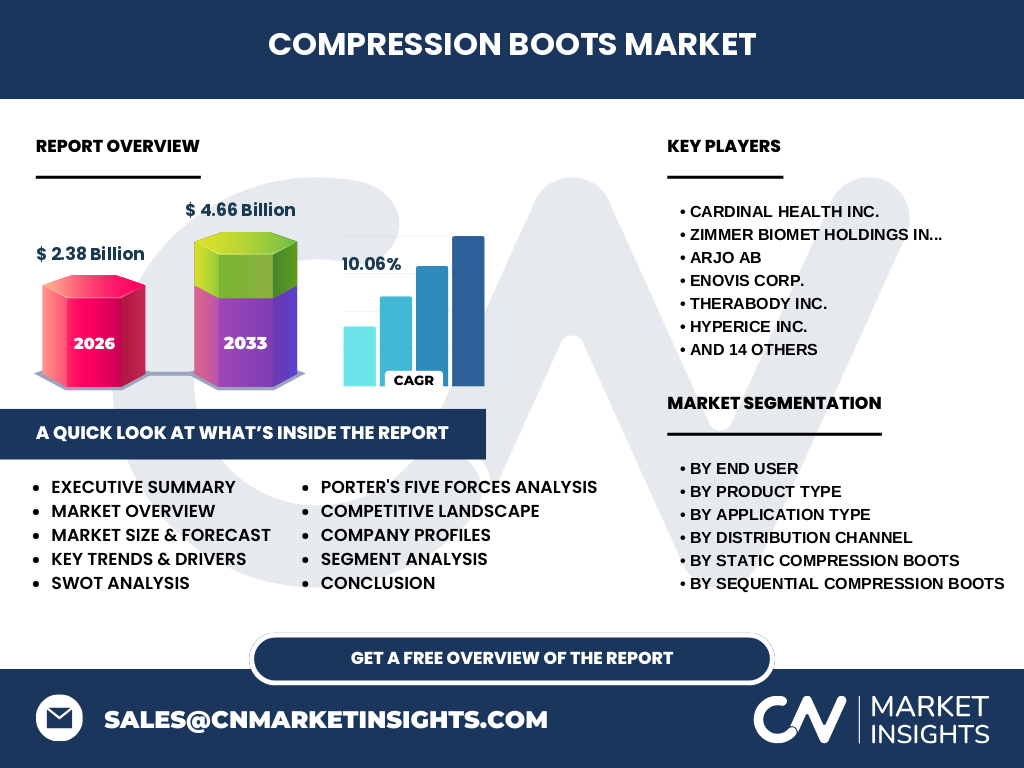
The market features a dual-track ecosystem: clinical giants like Cardinal Health Inc., Zimmer Biomet Holdings Inc., and Arjo AB dominate hospitals, while consumer-facing innovators like Therabody Inc. and Hyperice Inc. lead retail segments. Strategic M&A and patent litigation over multi-chamber gradient pressure profiles characterize current industry dynamics.
Executive summary — high-level synthesis of key findings about Compression Boots Market
Driven by robust clinical demand and athletic adoption, the Compression Boots Market is projected to expand from $2.38 Billion in 2026 to $4.66 Billion by 2033, reflecting a solid CAGR of 10.06%. Stakeholders must prioritize multi-chamber portable designs to capture high-growth clinical and home care opportunities.
Market forecast — projected growth from 2027 to 2033
Based on our research, the market will experience accelerated expansion, surging from the 2026 baseline to reach $4.66 Billion by 2033 at a consistent CAGR of 10.06%. This trajectory is underpinned by aging demographics prone to chronic venous insufficiency and expanding direct-to-consumer fitness recovery budgets.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans End Users (Hospitals, Clinics, Ambulatory Surgical Centers, Other End Users), Product Types (Sequential, Intermittent Pneumatic, Static Compression Boots), Applications (Medical, Sports And Fitness, Home Care), and Distribution Channels (Online Stores, Specialty Stores, Pharmacies). Each tier caters to distinct regulatory thresholds and purchasing behaviors.
Regional market analysis — geographic distribution and performance across regions
North America commands the largest market share, bolstered by advanced healthcare infrastructure and high consumer spending on athletic recovery tech. Meanwhile, Asia-Pacific represents the fastest-growing regional market, driven by expanding healthcare expenditure in China and South Korea, anchored by regional innovators like Zhejiang Longest Medical Technology Co. Ltd.
In-depth regional review — detailed examination of key regional markets
In North America, strict FDA oversight shapes product commercialization, favoring established clinical suppliers like Cardinal Health Inc. and Breg Inc. In Europe, adherence to stringent MDR guidelines dictates market entry, while Asia-Pacific benefits from lower raw material and labor costs managed by firms such as Shenzhen Fit King Health Technology Co. Ltd.
Company profiles — strategic positioning of leading companies in Compression Boots Market
Industry leaders occupy highly differentiated niches: Zimmer Biomet Holdings Inc. and Arjo AB focus on hospital-grade DVT prevention systems. Concurrently, consumer brands like Therabody Inc., Hyperice Inc., and Air Relax USA LLC leverage aggressive digital marketing and ergonomic portable designs to capture the lucrative sports and fitness demographic.
Porter's Five Forces analysis — competitive forces assessment
The threat of new entrants remains moderate to high due to low software barriers in consumer apps, though countered by steep medical certification costs. Bargaining power of buyers is high in institutional hospital procurement, whereas supplier power over specialized pneumatic solenoid valves remains concentrated among select component makers.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths lie in proven clinical efficacy for lymphedema and DVT. Weaknesses include high unit retail costs for advanced portable units. Opportunities exist in emerging home care telemedicine integrations. Threats stem from unverified low-cost knockoffs bypassing safety standards on e-commerce platforms.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw material suppliers providing medical-grade TPU, nylon, and micro-compressors. Manufacturers like Mego Afek AC Ltd. and Bio Compression Systems Inc. assemble the finished garments. Distribution then flows through specialized medical distributors, online stores, and hospital procurement channels to end-users.
Investment insights — strategic recommendations and high-potential areas
Investors should target manufacturers specializing in portable intermittent pneumatic compression boots and multi-chamber gradient systems. Companies integrating IoT-enabled biometric feedback loops offer superior valuation upside, as they bridge the gap between clinical efficacy and consumer fitness tracking.
Conclusion and key takeaways
The Compression Boots Market represents a high-growth intersection of medical therapeutics and consumer wellness. Achieving a market size of $2.38 Billion in 2026 and scaling toward $4.66 Billion by 2033 at a CAGR of 10.06%, the industry rewards agile players balancing regulatory compliance with user-centric portability.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-level executives at firms like Enovis Corp. and DoDaesung Maref Co. Ltd., and secondary macroeconomic indicators regarding global healthcare expenditure and sports science market growth.
Scope of the report — coverage parameters and limitations
This report covers global market sizing, segmental evaluations, and competitive intelligence for the period spanning 2026 to 2033. Limitations include unforeseen macroeconomic shifts, localized regulatory policy alterations, and sudden supply chain bottlenecks affecting electronic component availability across key manufacturing sectors.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent industry momentum is defined by strategic partnerships between athletic recovery brands and professional sports leagues. Major players have rolled out FDA-cleared wireless units equipped with lithium-ion batteries, eliminating cumbersome tubing and establishing new benchmarks for user convenience in both clinical and home care environments.