Market overview of the Radiofrequency (RF) Body Contouring Units Market
Our analysis indicates that the Radiofrequency (RF) Body Contouring Units Market valued at 7.36 Billion in 2026 represents a cornerstone of non-invasive aesthetic medicine. This sector encompasses specialized clinical and homecare hardware utilizing controlled thermal energy to target subcutaneous adipose tissue and stimulate neocollagenesis. Regulatory oversight by agencies like the FDA and CE ensures strict safety compliance for devices sourced from raw material supply chains involving medical-grade gold, titanium, and advanced ceramic applicators.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by surging consumer preference for non-surgical aesthetic procedures, yet growth is occasionally tempered by stringent compliance hurdles mandated by bodies such as the FDA. Key opportunities lie in expanding high-power professional systems into emerging economies, whereas high initial capital expenditures for multi-applicator platforms remain a persistent logistical challenge for independent clinics.
The Shift Toward Non-Invasive Aesthetic Solutions
Industry trends demonstrate a definitive pivot away from liposuction toward devices offering zero downtime. Manufacturers are rapidly integrating monopolar radiofrequency and multipolar radiofrequency technologies into compact professional devices. Based on our research, clinics prioritizing patient comfort are driving adoption of combined systems that simultaneously address cellulite reduction and skin tightening.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic severely disrupted elective aesthetic procedures, causing sharp supply chain bottlenecks for critical components like specialized semiconductor chips and delivery handpieces. However, our findings highlight a robust post-pandemic rebound. Clinics accelerated digital bookings and invested in high-power professional systems to capture pent-up consumer demand for body reshaping treatments.
Competitive Benchmarking and Strategic Market Dynamics
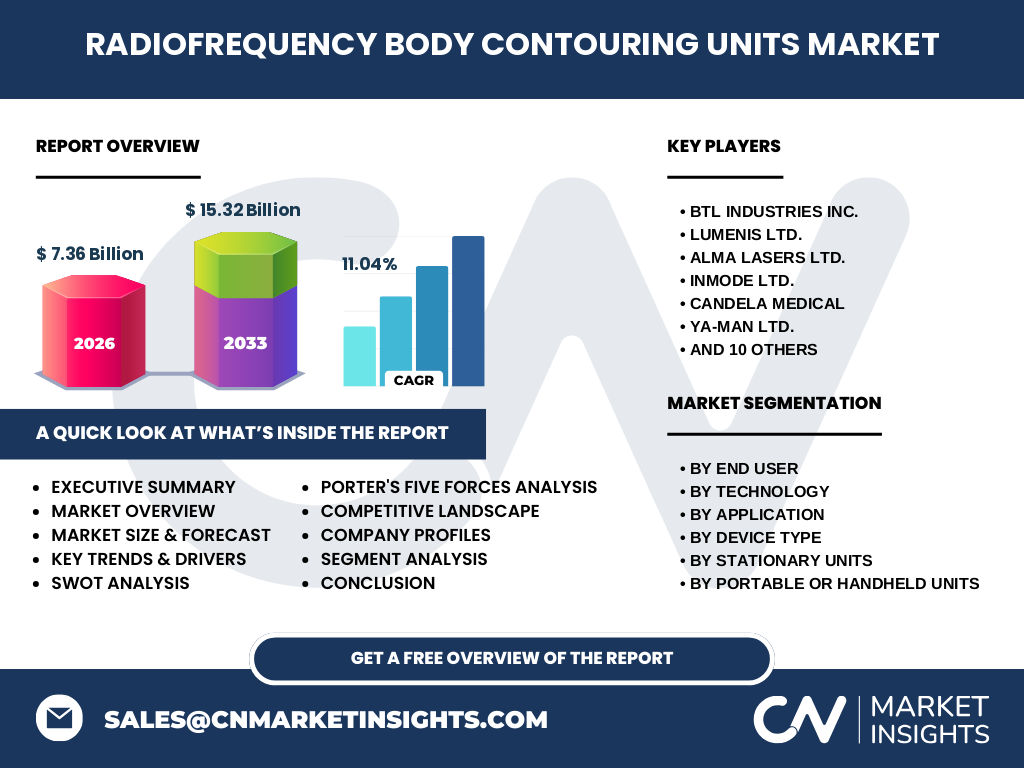
Market concentration is moderately high, dominated by established innovators such as InMode Ltd., Alma Lasers Ltd., and BTL Industries Inc. These tier-one players leverage extensive patent portfolios in fractional radiofrequency and aggressive physician training programs. Meanwhile, agile Asian manufacturers like Wontech Co. Ltd. and Shenzhen GSD Tech Co. Ltd. compete aggressively on cost-effective portable and home-use device platforms.
Executive Summary of Key Findings
Our comprehensive evaluation confirms that the Radiofrequency (RF) Body Contouring Units Market is poised for exceptional expansion, driven by technological convergence and rising disposable incomes. Strategic partnerships between device manufacturers and dermatology chains are unlocking new revenue streams, reinforcing the industry's trajectory toward high-margin recurring consumables and advanced multi-platform consoles.
Market Forecast and Long-Term Projections (2027 to 2033)
The data suggests unprecedented expansion, with the market projected to surge from 7.36 Billion in 2026 to 15.32 Billion by 2033, reflecting a robust 11.04% CAGR. This acceleration is underpinned by continuous hardware miniaturization, expanding applications in wrinkle reduction, and broadening reimbursement codes in select international geographies.
Segmentation Analysis Across Technology, Application, and Device Types
Segmentation is categorized by end user (Hospitals, Dermatology Clinics, Beauty Centers, Homecare Users, Specialty Clinics), technology (Monopolar, Bipolar, Multipolar, Combined), application (Body Contouring, Skin Tightening, Cellulite, Fat Reduction, Wrinkle Reduction), and device type (Stationary vs. Portable). Stationary units feature multi-applicator and clinic-based console systems, while portable units range from corded handheld devices to battery-operated home use variations.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America retaining the highest revenue share due to high consumer spending and widespread acceptance of aesthetic treatments. Europe follows closely, anchored by stringent CE certification frameworks that instill high consumer trust. Meanwhile, the Asia-Pacific region is registering the fastest growth, fueled by rising urban middle classes in countries like South Korea and Japan.
In-Depth Regional Review of Key Markets
Our regional audit reveals that the United States market is dominated by high-end clinic-based console systems deployed in premier dermatology practices. In contrast, the Asia-Pacific landscape shows unique traction for compact professional devices and home use gadgets, distributed heavily through specialized medical tourism hubs and e-commerce channels.
Company Profiles and Strategic Positioning
Leading entities occupy distinct strategic niches: Cynosure and Candela Medical focus on clinically proven high-power professional systems, whereas Solta Medical Inc. maintains strong brand equity in specialized skin tightening platforms. Concurrently, innovators like Jeisys Medical Inc. and EndyMed Medical Ltd. capture market share through proprietary multi-source phase-controlled radiofrequency delivery mechanisms.
Porter's Five Forces Analysis of the Industry
The threat of new entrants is moderate, constrained by high R&D costs and stringent FDA approval processes. Rivalry among existing competitors is intense, pressuring profit margins and forcing continuous innovation in applicator ergonomics. Buyer power is elevated due to the abundance of alternative non-invasive fat reduction modalities such as cryolipolysis.
SWOT Analysis of the Radiofrequency Body Contouring Sector
Key strengths include high treatment efficacy and excellent safety profiles. Weaknesses involve high device acquisition and maintenance costs. Opportunities abound in expanding homecare user segments, while threats stem from unregulated counterfeit aesthetic devices distributed through unauthorized online channels.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing medical-grade polymers, aluminum alloys, and specialized circuit components. Mid-stream manufacturers assemble these inputs into sophisticated stationary units and portable devices, which are subsequently channeled through specialized medical distributors to hospitals, dermatology clinics, and ultimately end-users.
Investment Insights and High-Potential Growth Areas
Investors should direct capital toward companies pioneering home-use devices and integrated platform systems, as these segments offer the highest scalability. Furthermore, targeting emerging markets in Latin America and Southeast Asia presents lucrative opportunities for early-mover advantage in specialized clinics.
Conclusion and Strategic Takeaways
The Radiofrequency (RF) Body Contouring Units Market industry trends confirm that technological innovation and user-centric design are paramount for long-term success. Stakeholders must adapt to shifting consumer demands favoring hybrid, multi-functional units that deliver rapid, measurable aesthetic results with minimal recovery times.
Research Methodology and Baseline Estimation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with key opinion leaders in dermatology, and secondary macroeconomic indicators. This multi-layered approach ensures precise market sizing and reliable forecasting models.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Radiofrequency (RF) Body Contouring Units Market from 2026 through 2033. Limitations include the exclusion of surgical liposuction equipment and traditional laser-only lipolysis platforms, focusing strictly on radiofrequency-driven therapeutic interventions.
Recent Developments, Product Launches, and Strategic Moves
Recent industry momentum is characterized by FDA clearances for advanced multi-applicator platforms and strategic mergers among device distributors. Companies like Apyx Medical Corporation and Lynton Lasers Ltd. have recently unveiled upgraded handpieces featuring real-time temperature feedback, significantly enhancing procedural safety and clinical efficacy.