What is the market overview of the Sports Rehabilitation Equipment Market?
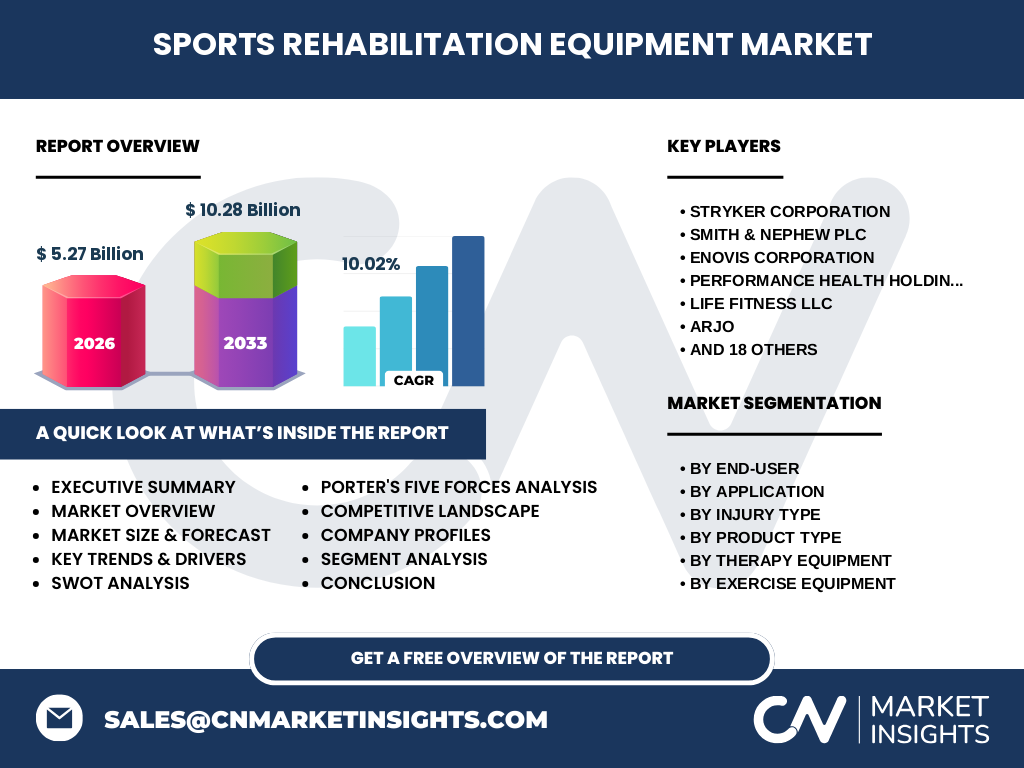
Our analysis indicates the Sports Rehabilitation Equipment Market stands at a robust valuation of $5.27 Billion in 2026. This sector encompasses advanced therapeutic devices, exercise apparatus, and body support solutions designed to restore mobility, manage trauma, and accelerate functional recovery for clinical facilities and athletic training programs worldwide.
What are the core market drivers, restraints, challenges, and opportunities shaping the industry?
Growth is significantly propelled by rising sports participation rates and advanced technological integrations in electrotherapy and robotics. However, strict FDA and CE mark compliance hurdles present logistical bottlenecks. Key opportunities lie in expanding telehealth-compatible home care settings and developing portable shockwave therapy units for remote athletic teams.
What are the emerging trends and growth patterns in the Sports Rehabilitation Equipment Market?
A notable shift toward data-driven recovery protocols is reshaping the Sports Rehabilitation Equipment Market industry trends. Practitioners increasingly utilize smart sensors embedded in resistance bands and balance boards to track patient biomechanics in real-time, favoring tech-forward manufacturers like Tecnobody S.r.l. and BTL Industries Inc.
How did the COVID-19 pandemic impact the market and shape the post-pandemic recovery trajectory?
Supply chain disruptions and elective surgery postponements initially contracted sector revenues during the pandemic. Yet, the crisis permanently accelerated adoption of remote rehabilitation, driving robust demand for portable continuous passive motion devices and tele-rehabilitation software supported by specialized home care product lines.
Competitive Benchmarking and Strategic Dynamics
The landscape is characterized by high market concentration among established medical technology leaders such as Stryker Corporation, Smith & Nephew plc, and Enovis Corporation. These players leverage aggressive M&A strategies to acquire proprietary laser and cryotherapy patents, outcompeting smaller regional suppliers through extensive global distribution networks.
Executive Summary of Key Findings
Our proprietary research projects the Sports Rehabilitation Equipment Market market size to expand from $5.27 Billion in 2026 to an impressive $10.28 Billion by 2033, registering a stellar compound annual growth rate (CAGR) of 10.02%. This acceleration is fueled by surging musculoskeletal injury volumes and rapid innovation in electrotherapy.
What is the long-term market forecast from 2027 to 2033?
The data suggests sustained double-digit expansion, scaling the market from its 2027 baseline to reach $10.28 Billion by 2033 at a 10.02% CAGR. Investments will heavily favor automated robotic gait trainers and advanced neuromuscular electrical stimulation units as aging populations and active youth demographics drive demand.
Segmentation Analysis of Product Categories and Applications
The market segments by end-user into Athletes and Non-Athletes, and by application across Hospitals And Clinics, Physiotherapy Centers, Rehabilitation Centers, and Home Care Settings. Product categories span Therapy Equipment, Body Support Devices, and Exercise Equipment, addressing diverse injury profiles from acute trauma to post-surgical care.
Geographic Distribution and Regional Market Performance
North America maintains a dominant revenue share due to high sports healthcare expenditures and stringent insurance reimbursement frameworks. Meanwhile, the Asia-Pacific region exhibits the fastest growth trajectory, driven by expanding healthcare infrastructure in emerging economies and rising investments in elite athletic training facilities.
In-Depth Regional Review and Localized Market Constraints
Localized regulatory hurdles, such as stringent PMDA approvals in Japan and varying CE mark interpretations across European Union member states, dictate regional go-to-market strategies. Supply chains rely heavily on key shipping hubs, making timely raw material sourcing for aluminum-based exercise machines and medical-grade polymers critical for regional success.
Strategic Positioning of Leading Industry Players
Market leaders occupy distinct niches: Keiser Corporation dominates pneumatic resistance training, Zynex Inc. leads in electrotherapy pain management, and Hocoma AG spearheads robotic neurological rehabilitation. Their strategic focus on clinical validation secures preferred-provider status within major hospital systems and professional sports franchises worldwide.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to specialized raw material dependencies for carbon-fiber braces and laser diodes. Competitive rivalry is fierce among global giants, while the threat of new entrants is mitigated by high R&D expenditures, stringent regulatory clearance costs, and established intellectual property moats held by incumbents.
SWOT Analysis of the Sports Rehabilitation Equipment Sector
Strengths include robust clinical efficacy and strong brand loyalty; weaknesses involve high device maintenance costs. Opportunities emerge in untapped home-care markets, while threats stem from stringent reimbursement cuts by third-party payers and counterfeit low-cost alternatives threatening medical device integrity.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material procurement—sourcing medical-grade silicones, titanium, and specialized electronic components. These materials flow through precision manufacturing facilities operated by firms like Dynatronics Corporation and Breg Inc., passing through specialty distributors and online stores before reaching clinical end-users.
High-Potential Investment Insights and Strategic Recommendations
Investors should direct capital toward companies integrating artificial intelligence into continuous passive motion and ultrasound devices. Our analysis indicates that early-stage acquisitions focusing on portable, app-connected recovery tools yield the highest valuation multiples as consumer demand shifts toward preventative and home-based therapy.
Conclusion and Strategic Takeaways for Industry Stakeholders
Surpassing $10 Billion by 2033, the market offers exceptional growth for entities aligning with technological convergence and home-care decentralization. Stakeholders must prioritize regulatory compliance, ergonomic product design, and strategic distribution partnerships to capture high-margin opportunities across both athlete and non-athlete segments.
Research Methodology and Baseline Estimation Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing customs trade registry data, primary stakeholder interviews with clinical physiotherapists, and secondary macroeconomic indicators. This multi-tiered analytical approach ensures precise market sizing and reliable forecasting across all product categories and geographic territories.
Scope of the Report and Analytical Limitations
This report covers global revenue performance across specified product types, injury classifications, and distribution channels from 2026 through 2033. Limitations include unforeseen macroeconomic shifts, sudden regulatory policy revisions in key jurisdictions, and localized supply chain disruptions affecting raw material availability.
Recent Developments, Product Launches, and Strategic Partnerships
Recent industry momentum highlights aggressive product innovation, including advanced shockwave therapy unit launches and strategic distribution alliances between rehabilitation device manufacturers and professional sports leagues. Companies are actively expanding their digital ecosystems to support remote patient monitoring and tele-physiotherapy modalities.