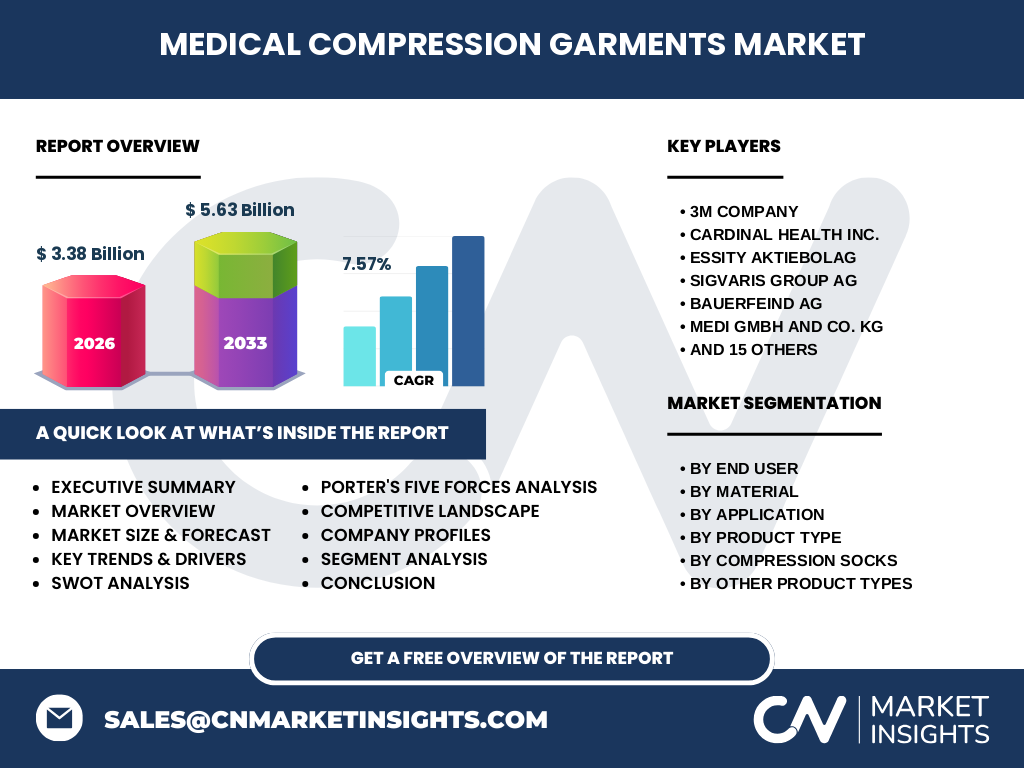
Market overview of the Medical Compression Garments Market
Our analysis indicates that the Medical Compression Garments Market represents a vital sector within medical textiles, valued at 3.38 Billion in 2026. This industry encompasses specialized therapeutic products like compression stockings, arm sleeves, and bandages engineered to apply controlled pressure, managing venous and lymphatic disorders.
Structural Growth Drivers and Restraints
The market is propelled by rising chronic venous insufficiency and deep vein thrombosis prevalence. However, stringent FDA and CE MDR compliance protocols create formidable market entry barriers, while raw material price volatility in nylon and spandex constrains profit margins for manufacturers.
Emerging Trends and Growth Patterns in Medical Compression Garments Market
A definitive shift toward smart textiles and custom-fit garments is redefining care delivery. Digital integration allows patients to monitor pressure application via connected applications, driving adoption across home care settings and specialized ambulatory surgical centers.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic caused severe supply chain disruptions and deferred elective surgeries, temporarily suppressing demand. Post-pandemic recovery has been robust, accelerated by heightened awareness of post-surgical thrombosis management and telehealth-enabled remote patient monitoring solutions.
Competitive Benchmarking and Market Concentration
The competitive landscape is characterized by moderate fragmentation, featuring multinational healthcare conglomerates alongside specialized textile innovators. SIGVARIS GROUP AG and Bauerfeind AG lead through continuous R&D, while firms like Tactile Systems Technology Inc. focus on advanced pneumatic compression.
Executive Summary of Key Findings
Our proprietary research confirms the Medical Compression Garments Market is poised for accelerated expansion, scaling from 3.38 Billion in 2026 to 5.63 Billion by 2033 at a 7.57% CAGR. Strategic focus on home care distribution channels will yield the highest returns.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the market will achieve a robust 7.57% CAGR, expanding from 2027 through 2033 to reach 5.63 Billion. This trajectory is underpinned by aging demographics and escalating incidence rates of lymphedema and chronic wounds globally.
Segmentation Analysis Across Applications and Materials
Segmentation spans multiple vectors: End Users (Hospitals, Ambulatory Surgical Centers, Home Care), Materials (Nylon, Cotton, Spandex, Natural Rubber), Applications (Varicose Vein Treatment, Deep Vein Thrombosis, Lymphedema, Wound Care), and Product Types including stockings, shorts, sleeves, and bandages.
Geographic Distribution and Regional Performance
Regional performance varies significantly due to healthcare infrastructure disparities and reimbursement policies. North America maintains dominance owing to high adoption of advanced wound care products, whereas Asia-Pacific represents the fastest-growing frontier driven by expanding hospital networks in urban centers.
In-Depth Regional Review
Regulatory stringency by bodies like the FDA in North America ensures high compliance standards, whereas European markets navigate complex MDR frameworks. Meanwhile, localized manufacturing hubs in emerging economies leverage affordable cotton and synthetic fibers to serve domestic retail pharmacies.
Strategic Positioning of Leading Companies
Industry leaders employ distinct differentiation strategies. Companies like 3M Company and Cardinal Health Inc. leverage vast distribution networks, while specialists such as Medi GmbH And Co. KG and Thuasne S.A.S focus on clinically validated orthopedic and vascular solutions.
Porter's Five Forces Analysis of Competitive Intensity
Supplier power remains moderate due to the commodity nature of nylon and spandex, whereas buyer power is high in hospital procurement tenders. Threat of substitution is low given the clinical efficacy required for deep vein thrombosis and lymphedema treatments.
SWOT Analysis of the Industry
Strengths include established clinical utility and broad product portfolios. Weaknesses involve patient compliance hurdles with tight garments. Opportunities lie in emerging home care markets, while threats include counterfeit products and reimbursement policy cuts.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction of nylon, spandex, and natural rubber, progressing through textile weaving, medical-grade compression knitting, sterilisation, and distribution via hospitals, online stores, and retail pharmacies to end-users.
Investment Insights and High-Potential Areas
Investors should target direct-to-consumer online distribution channels and smart compression startups. High-potential growth lies in customized pneumatic devices and anti-embolism solutions tailored for ambulatory surgical centers and home care environments.
Conclusion and Strategic Takeaways
The Medical Compression Garments Market offers compelling opportunities for stakeholders willing to invest in material science innovations and digital health integrations, securing a path toward the projected 5.63 Billion valuation by 2033.
Research Methodology and Baseline Triangulation
Our findings are derived from triangulating primary stakeholder interviews with vascular surgeons and procurement managers, combined with secondary trade registry data, macroeconomic indicators, and regulatory filings from agencies like the FDA and EMA.
Scope and Limitations of the Report
This report evaluates the global Medical Compression Garments Market across defined product, material, application, and end-user segments. Limitations include unforeseen macroeconomic shifts, geopolitical trade friction affecting raw material imports, and sudden regulatory alterations.
Recent Developments and Strategic Industry Moves
Recent milestones include AIROS Medical Inc. and Koya Medical Inc. launching advanced pneumatic compression devices, alongside strategic distribution partnerships formed by Essity Aktiebolag to expand its vascular therapy footprint across emerging retail pharmacy networks.