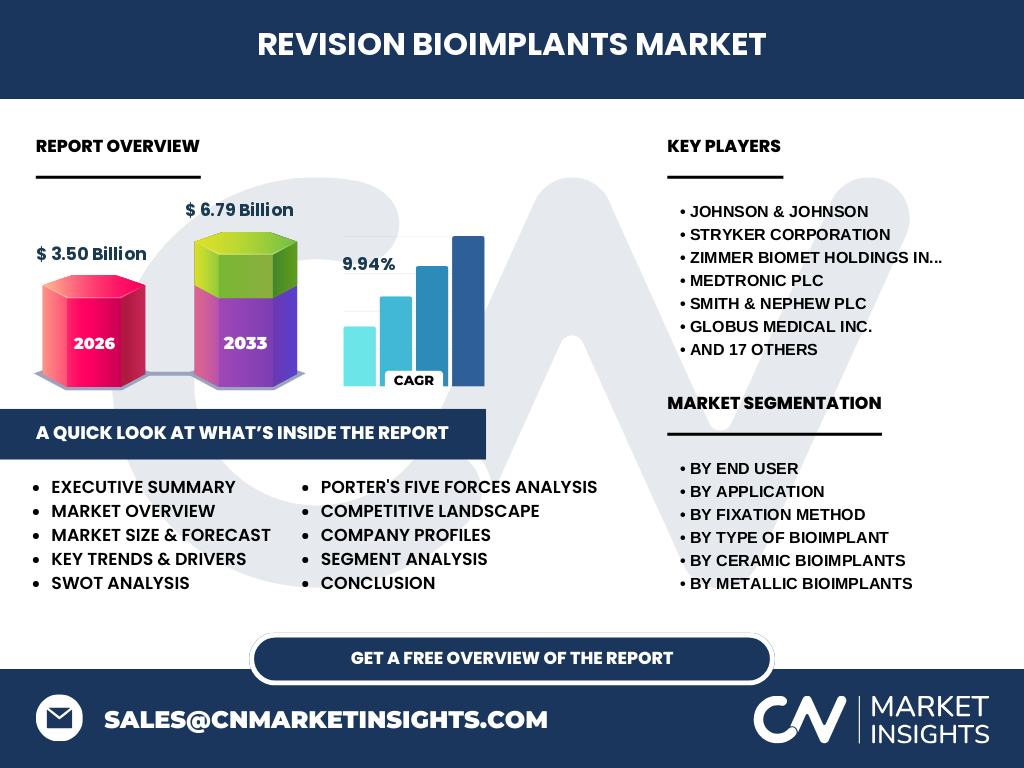
What is the market overview and scope of the Revision Bioimplants Market?
Our analysis indicates the Revision Bioimplants Market encompasses advanced medical devices utilized to replace, repair, or augment failed or degraded primary implants. Valued at 3.50 Billion in 2026, the industry addresses critical clinical challenges in orthopedic, dental, and cardiovascular procedures, driven by rising surgical revision rates and stringent biocompatibility standards mandated by regulatory bodies like the FDA and EMA.
Structural Growth Drivers, Restraints, and Opportunities
The market is propelled by an aging global demographic and higher primary joint arthroplasty volumes, which inevitably generate future revision procedures. However, high manufacturing costs for advanced materials and rigorous clinical trial hurdles act as restraints. Strategic opportunities abound in developing bioactive glass composites and magnesium-based implants that minimize osteolysis and reduce secondary failure rates.
Emerging Trends and Technological Growth Patterns
The shift toward patient-specific 3D-printed implants and custom Polyether Ether Ketone (PEEK) architectures represents a pivotal paradigm shift. Additive manufacturing allows precise anatomical matching, significantly reducing surgical theater times. Furthermore, the integration of antimicrobial coatings on titanium and cobalt-chromium substrates is rapidly emerging as the gold standard to mitigate periprosthetic joint infections.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted the sector as elective surgeries were deferred globally to prioritize emergency healthcare capacity. Supply chain bottlenecks for medical-grade titanium and specialized polymers caused temporary revenue contractions. Based on our research, the recovery trajectory has been exceptionally robust, fueled by surgical backlog clearances and accelerated hospital capital expenditures starting in late 2021.
Competitive Benchmarking and Industry Concentration
The competitive landscape is consolidated, featuring multinational medtech leaders alongside specialized innovators. Industry giants like Johnson & Johnson, Stryker Corporation, and Zimmer Biomet Holdings Inc. leverage expansive distribution networks and robust R&D pipelines. Meanwhile, agile players such as Globus Medical Inc. and Straumann Holding AG capture niche shares through proprietary surface modification technologies and modular revision systems.
Executive Summary of Key Industry Findings
Our comprehensive evaluation highlights a projected market expansion from 3.50 Billion in 2026 to 6.79 Billion by 2033, achieving a stellar CAGR of 9.94%. This robust trajectory underscores the critical necessity for durable revision solutions amidst escalating revision burdens. Companies prioritizing biomaterial innovation and regulatory compliance will capture disproportionate market value.
Market Forecast and Valuation Trajectory (2027 to 2033)
The data suggests sustained, aggressive growth, expanding the market from its 2026 baseline of 3.50 Billion to reach 6.79 Billion by 2033. This expansion is underpinned by a 9.94% CAGR, reflecting increased venture capital infusion, expanding reimbursement frameworks for complex revision surgeries, and higher adoption rates of ceramic-on-ceramic bearings in younger, active patient cohorts.
Segmentation Analysis by End User, Application, Fixation, and Type
Segmentation reveals nuanced demand patterns across the sector. By End User, demand spans Hospitals, Specialty Clinics, Ambulatory Surgical Centers, and Research Institutions. Applications cover Orthopedic, Dental, Cardiovascular, Neurological, and Plastic Surgery. Fixation methods include Cemented, Cementless, and Hybrid modalities. Bioimplant types encompass Metallic, Polymeric, Ceramic, and Composite variants, utilizing advanced sub-materials like Alumina, Zirconia, Silicone, and Carbon Fiber Composites.
Geographic Distribution and Regional Performance
Regional performance varies significantly based on healthcare infrastructure maturity, reimbursement policies, and local regulatory hurdles. North America currently dominates revenue generation due to high procedural volumes and early adoption of advanced PEEK and titanium technologies. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, driven by expanding healthcare expenditure in urban centers and rising medical tourism in nations like India and South Korea.
In-Depth Regional Review and Local Market Dynamics
North American growth is underpinned by advanced hospital networks and favorable Medicare reimbursement codes for revision arthroplasties. In Europe, stringent CE mark transitions under the European Medical Device Regulation (MDR) create localized compliance hurdles, favoring well-capitalized firms like B. Braun Melsungen AG and Peter Brehm GmbH. In contrast, emerging Asia-Pacific markets focus on cost-effective stainless steel and cobalt-chromium alternatives.
Strategic Positioning of Leading Market Participants
Industry leaders deploy distinct competitive strategies to defend and expand their market footprint. Firms such as Medtronic plc and Smith & Nephew plc focus on synergistic portfolios spanning cardiovascular and orthopedic revision. Concurrently, specialized providers like Paragon 28 Inc. and Maxx Orthopedics Inc. target specific anatomical niches, offering hyper-specialized instrumentation that secures high surgeon loyalty.
Porter's Five Forces Industry Assessment
The threat of new entrants remains low due to prohibitive R&D costs, strict FDA and ISO regulatory approvals, and entrenched surgeon preferences. Bargaining power of buyers is moderate to high, as large hospital group purchasing organizations (GPOs) demand volume discounts. Supplier power is tempered by the commodity nature of base metals, though proprietary bioactive glass composites command high supplier margins.
SWOT Analysis of the Revision Bioimplants Sector
Key strengths include advanced biocompatibility and prolonged implant longevity. Weaknesses involve high revision surgery failure risks and complex retrieval logistics. Opportunities lie in emerging bioactive glass composites and magnesium-based degradable implants. Threats encompass stringent regulatory compliance delays and unpredictable reimbursement policy revisions by federal payors.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing—procuring medical-grade titanium powder, zirconia blocks, and PEEK resins from certified chemical suppliers. Midstream activities involve precision machining, cleanroom sterilization, and rigorous biomechanical testing. The downstream phase involves direct distribution to hospital operating rooms and ambulatory surgical centers, orchestrated by specialized medical device sales representatives.
Strategic Investment Insights and High-Potential Areas
Investors should target emerging market segments exhibiting high growth potential, notably bioactive glass composites and 3D-printed patient-specific titanium implants. Strategic partnerships with academic research institutions will be vital for commercializing next-generation polymeric bioimplants, such as advanced polylactic acid derivatives designed for phased resorption.
Conclusion and Strategic Industry Takeaways
The Revision Bioimplants Market represents a high-barrier, high-reward sector projected to scale from 3.50 Billion to 6.79 Billion by 2033. Success hinges on navigating complex regulatory pathways, mastering advanced additive manufacturing techniques, and forging strong clinical partnerships to validate long-term implant efficacy in revision scenarios.
Research Methodology and Baseline Triangulation
Our analytical framework employs a rigorous triangulation methodology. Baseline estimates are constructed by cross-referencing import-export trade registries, proprietary primary interviews with orthopedic surgeons and hospital procurement heads, and secondary macroeconomic indicators from global health organizations. This ensures high data fidelity across all segment forecasts.
Scope of the Report and Analytical Parameters
This report covers global market sizing and forecasts from 2027 to 2033, utilizing 2026 as the baseline year. The scope encompasses detailed geographic evaluations across North America, Europe, Asia-Pacific, and Rest of the World. Limitations include the exclusion of primary implantation procedures that do not involve revision or secondary surgical intervention.
Recent Developments, Corporate Partnerships, and Product Launches
Recent market activity highlights aggressive R&D commercialization. Companies like Exactech Inc. and Orthofix Medical Inc. have announced FDA clearances for advanced revision fixation systems. Meanwhile, strategic acquisitions by firms such as Integra LifeSciences Holdings Corporation aim to consolidate regional distribution channels and enhance their orthopedic product portfolios.