Market overview and structural scope of the Peripheral Vascular Intervention Devices Market
Our analysis indicates that the Peripheral Vascular Intervention Devices Market encompasses specialized medical equipment designed to treat occlusive vascular diseases outside the coronary and intracranial circulations. Valued at 14.14 Billion in 2026, this sector plays a critical role in modern endovascular surgery, utilizing advanced raw materials like nitinol, medical-grade polymers, and platinum-iridium alloys to restore luminal patency in compromised peripheral vessels under strict regulatory frameworks.
What primary growth drivers, restraints, and challenges shape the Peripheral Vascular Intervention Devices Market?
The market is propelled by the escalating global prevalence of peripheral artery disease and diabetes-induced microvascular complications. Market restraints primarily stem from stringent FDA and CE-mark regulatory approval pathways and high device recall frequencies. Logistical hurdles involve maintaining cold-chain integrity for drug-coated configurations during transit through major medical distribution hubs.
Emerging technological trends and clinical adoption patterns
The shift toward minimally invasive outpatient procedures has accelerated the adoption of advanced atherectomy and drug-eluting platforms. Imaging guided intervention technology is increasingly combined with intravascular ultrasound to enhance procedural precision, favoring agile innovators capable of integrating diagnostic modalities directly into therapeutic catheter assemblies.
Pandemic repercussions and recovery trajectories within vascular interventions
The COVID-19 pandemic caused a temporary contraction in elective vascular procedures due to hospital resource reallocation and deferred outpatient diagnostics. However, our research reveals a robust post-pandemic rebound, driven by accumulated procedural backlogs and accelerated investments in ambulatory surgical centers to bypass hospital capacity constraints.
Competitive Benchmarking and Market Concentration
The competitive landscape is consolidated among Tier-1 medtech giants like Medtronic plc, Boston Scientific Corporation, and Abbott Laboratories, which leverage extensive global distribution networks. Meanwhile, specialized challengers such as Inari Medical Inc. and Shockwave Medical Inc. capture market share through disruptive mechanical thrombectomy and intravascular lithotripsy innovations.
Executive Summary: High-Level Synthesis of Market Projections
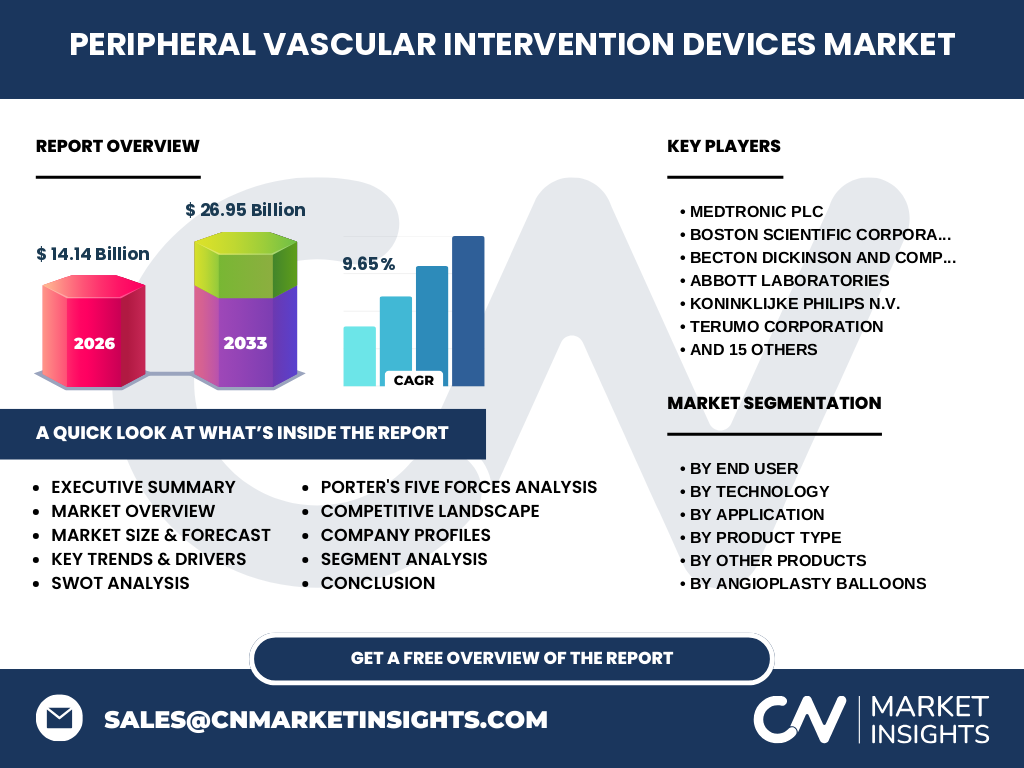
Driven by technological convergence and an aging demographic, the Peripheral Vascular Intervention Devices Market is projected to expand from 14.14 Billion in 2026 to 26.95 Billion by 2033, registering a robust CAGR of 9.65%. Strategic consolidation and localized manufacturing investments will define the industry's next phase of commercial expansion.
Peripheral Vascular Intervention Devices Market Forecast from 2027 to 2033
Our forecasting models project accelerated market velocity, surging from the 2026 baseline of 14.14 Billion to reach 26.95 Billion by 2033. This trajectory represents a steady 9.65% CAGR, fueled by escalating clinical demand for specialized peripheral artery disease treatments and expanding reimbursement frameworks across emerging economies.
Comprehensive Segmentation Breakdown and Market Roles
Segmentation spans multiple dimensions: End users encompass Hospitals, Ambulatory Surgical Centers, and Specialty Clinics Or Vascular Clinics. Technologies include Drug Coated Or Drug Eluting Technology, Non Coated Devices, Imaging Guided Intervention Technology, and Mechanical Intervention Technology, targeting peripheral artery disease, venous diseases, and critical limb ischemia.
Geographic Distribution and Regional Performance Dynamics
Regional performance is heavily skewed toward North America due to established reimbursement codes and high diagnostic rates. The Asia-Pacific region demonstrates the fastest growth velocity, supported by expanding healthcare infrastructure in China and Japan, while European markets remain stable under stringent MDR regulatory compliance standards.
In-depth Regional Review of Healthcare Infrastructure Constraints
North America maintains market dominance through early adoption of advanced plaque modification devices. Conversely, Latin American and Middle Eastern markets face localized reimbursement hurdles and restricted procurement budgets, slowing the widespread deployment of premium-priced bioabsorbable stents and specialized micro catheters.
Strategic Positioning of Leading Companies in the Ecosystem
Industry leaders maintain distinct market positions: Terumo Corporation and Cook Medical LLC focus on superior guide wire and support catheter engineering, while Penumbra Inc. and Inari Medical Inc. dominate the thrombectomy segment. Koninklijke Philips N.V. anchors its strategy in advanced imaging integration.
Porter's Five Forces Analysis of Competitive Intensity
Supplier power remains moderate due to specialized raw material requirements for nitinol and fluoropolymers. Competitive rivalry is intense among established multinational conglomerates, while the threat of substitution is mitigated by continuous device iteration in drug-coated angioplasty balloons and specialized atherectomy systems.
SWOT Analysis of the Vascular Intervention Sector
Strengths include robust intellectual property portfolios and high clinical efficacy. Weaknesses involve high R&D costs. Opportunities lie in emerging market expansion for critical limb ischemia treatments, while Threats encompass stringent regulatory hurdles and potential product liability litigation.
Value Chain Analysis from Raw Materials to Clinical End-Users
The value chain initiates with raw material synthesis of medical-grade stainless steel and polymers, progressing through precision cleanroom catheter manufacturing. Value flows through specialized logistics channels to major ports of entry, ultimately reaching clinical end-users in hospitals and ambulatory surgical centers.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize companies developing advanced plaque modification devices and specialized thrombectomy tools. High-growth opportunities exist in partnering with ambulatory surgical centers to capture shifting procedural volumes away from traditional hospital settings.
Conclusion and Strategic Takeaways for Market Entrants
The Peripheral Vascular Intervention Devices Market offers substantial commercial potential, backed by a projected expansion to 26.95 Billion by 2033. Success requires navigating regulatory complexities, forging strategic distribution partnerships, and investing aggressively in next-generation drug-eluting and imaging-guided technologies.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with vascular surgeons, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing and segment revenue allocations.
Scope of the Report and Analytical Parameters
This report covers global market dynamics for peripheral vascular intervention devices from 2026 through 2033. Analytical limitations include potential variances in localized healthcare spending and unpredictable regulatory review timelines across international jurisdictions.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum highlights aggressive product pipelines from innovators like Shockwave Medical Inc. and Zylox-Tonbridge Medical Technology Co. Ltd. Strategic mergers, acquisitions, and cross-border distribution agreements continue to reshape competitive boundaries in the global vascular sector.