What is the market overview and industry significance of the Defense Cloud Computing Market?
Our analysis indicates that the Defense Cloud Computing Market represents a critical technological frontier, valued at $9.04 Billion in 2026. This sector encompasses secure infrastructure, virtualization, and advanced data analytics tailored for military branches. Industry significance lies in modernizing command and control architectures, enabling real-time tactical edge computing, and ensuring resilient communications across global defense networks against sophisticated cyber threats.
What are the key market drivers, restraints, challenges, and opportunities shaping the Defense Cloud Computing Market?
Growth is propelled by surging demand for tactical data analytics and secure storage across combat operations. However, stringent regulatory compliance frameworks and data sovereignty mandates act as significant restraints. Technical challenges involve securing legacy hardware against zero-day exploits. Opportunities abound for providers delivering hybrid cloud solutions and advanced Hardware Security Modules that integrate seamlessly with legacy military platforms.
What are the emerging trends and growth patterns in the Defense Cloud Computing Market?
The sector is witnessing a decisive shift toward tactical edge computing and multi-cloud interoperability. Major defense agencies are increasingly adopting Infrastructure as a Service (IaaS) and Platform as a Service (PaaS) to accelerate mission software deployment. Our research highlights how containerization and automated orchestration tools are transforming how the Air Force and Navy deploy operational applications globally.
How did the COVID-19 pandemic impact the Defense Cloud Computing Market and what is the recovery trajectory?
The pandemic exposed vulnerabilities in legacy on-premise military IT, acting as a powerful catalyst for remote secure access and cloud adoption. Supply chain disruptions for networking equipment temporarily slowed infrastructure deployment. The post-pandemic recovery trajectory shows accelerated budget allocations toward secure access hardware and decentralized cloud architectures, ensuring uninterrupted remote command operations.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The competitive landscape features a mix of defense prime contractors and hyperscale cloud providers. Tech giants like Amazon Web Services Inc., Microsoft Corporation, and Google LLC dominate cloud infrastructure delivery. Meanwhile, traditional defense contractors such as Lockheed Martin Corporation, Northrop Grumman Corporation, and General Dynamics Corporation leverage deep domain expertise to integrate these cloud frameworks into classified military hardware.
Executive summary of key findings about the Defense Cloud Computing Market
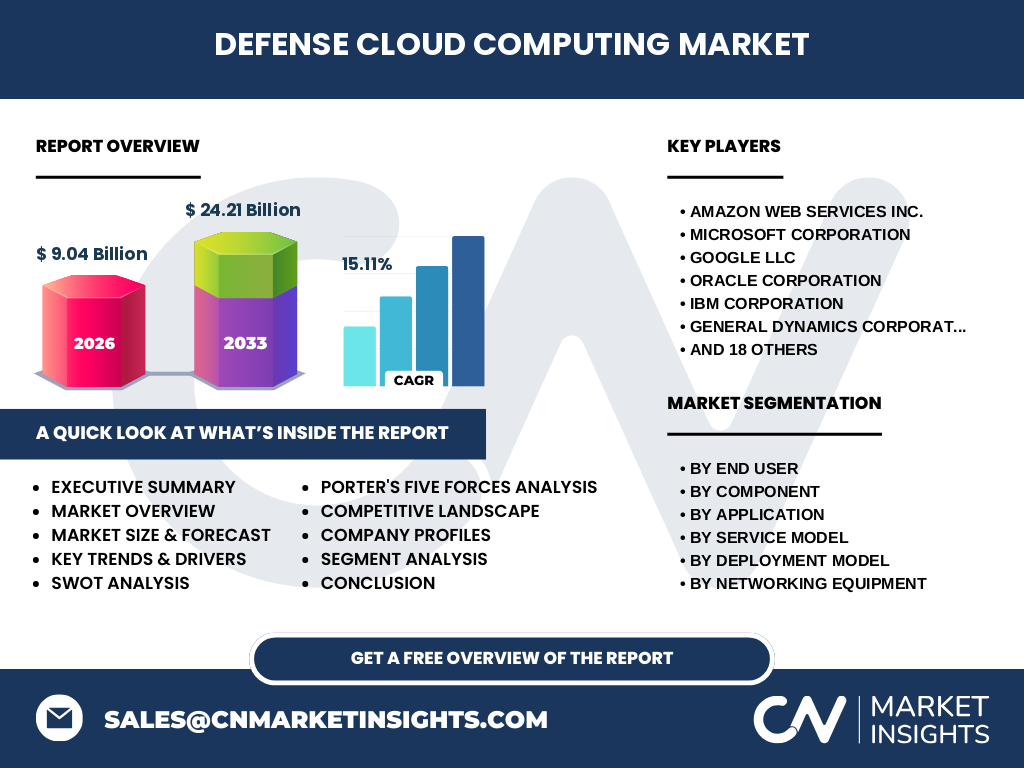
Our comprehensive research projects the Defense Cloud Computing Market to expand from $9.04 Billion in 2026 to reach $24.21 Billion by 2033, registering a robust CAGR of 15.11%. Key growth catalysts include multi-domain operations, surging demand for secure storage, and increased adoption of artificial intelligence analytics across Army, Navy, and Air Force installations worldwide.
Market forecast and projected growth trajectory from 2027 to 2033
Based on our econometric modeling, the market is poised for accelerated expansion, scaling from its 2026 baseline of $9.04 Billion to a substantial $24.21 Billion by 2033. This trajectory represents a steady CAGR of 15.11%, driven by sustained multi-billion-dollar government cloud migration contracts, expanding adoption of hybrid cloud deployments, and surging investments in combat operations data processing.
Segmentation analysis of the Defense Cloud Computing Market
The market is structured across multiple dimensions. By end user, it covers the Army, Navy, and Air Force. Component categories include Cloud Storage Servers and Virtualization Software. Service models span IaaS, PaaS, and SaaS, while deployment models feature Public, Private, and Hybrid Cloud. Applications range from Training And Simulation to critical Logistics And Supply Chain Management.
Regional market analysis and geographic performance distribution
Geographic performance is heavily influenced by national defense budgets and cybersecurity mandates. North America commands the largest market share, anchored by substantial Department of Defense expenditures. The Asia-Pacific region demonstrates the fastest growth rate, fueled by escalating regional security tensions and rapid military modernization programs requiring advanced data analytics and resilient networking equipment.
In-depth regional review of key Defense Cloud Computing Market territories
North America leads due to early adoption of multi-cloud defense strategies by key agencies. In Europe, stringent data protection regulations and initiatives toward strategic digital autonomy drive regional investments in private cloud and sovereign infrastructure. Meanwhile, Asia-Pacific nations are rapidly procuring advanced security and encryption hardware to protect sensitive military networks against state-sponsored cyber espionage.
Company profiles and strategic positioning of leading market participants
Market leaders utilize distinct strategic approaches. Firms like Palantir Technologies and Leidos Holdings Inc. excel in tactical data integration and analytics. Tech enterprises such as Oracle Corporation and IBM Corporation provide secure enterprise database management. Meanwhile, defense specialists like BAE Systems plc, Thales Group, and RTX Corporation ensure ruggedized hardware compatibility for deployed tactical units.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate to high, as sovereign defense departments dictate stringent technical specifications. Threat of new entrants remains low due to formidable barriers, including strict security clearances, compliance certifications, and massive capital requirements for cloud storage servers. Competitive rivalry is intense among established cloud hyperscalers and defense primes vying for multi-billion-dollar enterprise migration contracts.
SWOT analysis of the Defense Cloud Computing Market
Strengths include unmatched data processing capabilities and enhanced operational agility. Weaknesses involve vulnerabilities in legacy integration and complex compliance hurdles. Opportunities lie in expanding edge computing for deployed forces and leveraging AI-driven automation. Threats encompass sophisticated cyber warfare attacks, potential cloud service outages, and evolving geopolitical data localization restrictions.
Value chain analysis from raw materials to end-user deployment
The value chain originates with raw material providers supplying silicon and rare earth elements for hardware security modules and servers. Component manufacturers then build switching equipment and trusted platform modules. Software vendors develop cloud management platforms, which systems integrators like Booz Allen Hamilton Holding Corporation and Science Applications International Corporation (SAIC) assemble into bespoke solutions for the Army and Navy.
Investment insights and high-potential areas for capital allocation
Our analysis reveals that high-potential investment opportunities lie in specialized security and encryption hardware and decentralized edge computing architectures. Venture capital and private equity should prioritize firms offering advanced resource orchestration tools and zero-trust security frameworks. Companies enabling seamless interoperability between legacy tactical radios and modern cloud storage will capture disproportionate market share.
Conclusion and key takeaways for stakeholders
The Defense Cloud Computing Market represents a high-growth sector set to reach $24.21 Billion by 2033 at a 15.11% CAGR. Success in this landscape requires rigorous adherence to defense-grade security, deep integration with legacy military platforms, and robust hybrid cloud capabilities. Stakeholders must align their product roadmaps with the Department of Defense's multi-cloud and tactical edge modernization goals.
Research methodology and baseline estimation triangulation
Our baseline estimates are derived through a rigorous triangulation methodology. We combine defense budget filings from global ministries, trade registry data for networking equipment shipments, and primary stakeholder interviews with chief technology officers across defense primes like General Dynamics Corporation and Cisco Systems Inc. This primary qualitative input is cross-referenced with macroeconomic indicators and historical cloud adoption curves.
Scope of the report and coverage parameters
This report covers the global Defense Cloud Computing Market across all major component types, service models, deployment architectures, applications, and end-user branches. Geographical scope encompasses North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include the exclusion of unverified black-budget projects and classified intelligence operations not officially acknowledged by regulatory bodies.
Recent developments, strategic partnerships, and product launches
Recent market activity is characterized by major cloud service providers partnering with defense contractors to secure high-level government accreditations. Notable moves include joint ventures focusing on tactical edge deployments, enhanced automation and provisioning tools for deployed units, and the rollout of specialized hardware security modules designed to withstand extreme battlefield environments, strengthening overall operational resilience.