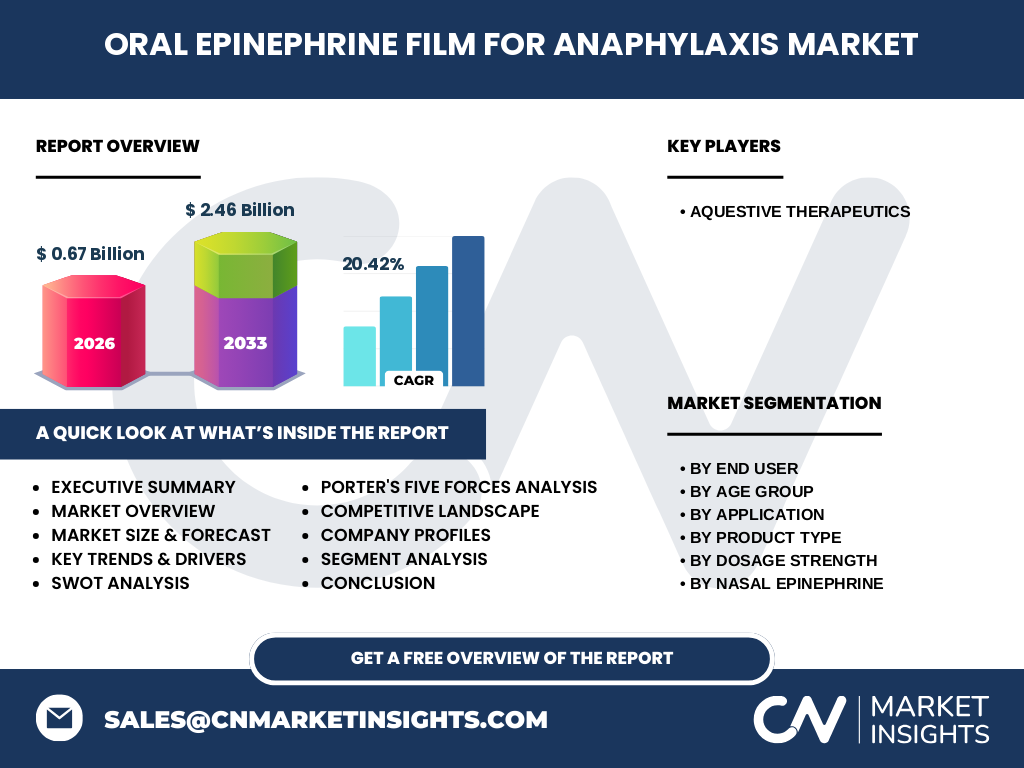
Market overview of the Oral Epinephrine Film For Anaphylaxis Market
The Oral Epinephrine Film For Anaphylaxis Market represents a paradigm shift in emergency allergy therapeutics, valued at $0.67 Billion in 2026. This sector encompasses advanced sublingual and buccal delivery systems designed to rapidly bypass hepatic first-pass metabolism, offering a needle-free alternative for severe IgE-mediated hypersensitivity reactions.
Structural Growth Drivers and Restraints
Our analysis indicates that rising food allergy prevalence fuels adoption, while strict regulatory hurdles by agencies like the FDA act as a temporary constraint. Growth is heavily accelerated by patient preference for non-invasive, discrete delivery matrices over traditional auto-injectors.
Emerging Industry Trends and Formulation Innovations
The shift toward polymer-based oral films is transforming acute care logistics. These formulations ensure rapid mucosal absorption without water, reducing caregiver administration anxiety during pediatric and adult anaphylactic events across school and institutional settings.
COVID-19 Impact Analysis and Post-Pandemic Recovery
Supply chain bottlenecks in specialty excipients temporarily disrupted clinical timelines during the pandemic. However, the post-pandemic recovery trajectory has rebounded strongly, driven by heightened decentralized healthcare demand and increased direct-to-consumer pharmacy distribution models.
Competitive Benchmarking and Market Concentration
The competitive landscape features high market concentration led by specialized innovators like Aquestive Therapeutics. Strategic positioning relies heavily on robust intellectual property portfolios surrounding proprietary sublingual film casting technologies and rapid bioequivalence profiling.
Executive Summary of Key Industry Findings
Our proprietary research reveals a robust 20.42% CAGR, propelling the market from $0.67 Billion in 2026 to $2.46 Billion by 2033. Commercial success depends on securing favorable formulary placement across retail pharmacies and institutional healthcare channels.
Long-Term Market Forecast from 2027 to 2033
Driven by rapid commercialization pipelines and expanding clinical indications, the market is projected to scale aggressively from 2027 through 2033. This trajectory reflects widespread clinical adoption across hospital emergency departments and outpatient home settings.
Comprehensive Segmentation Analysis
Segmentation spans multiple dimensions: By End User (Retail Pharmacies, School And Institutional Settings, Hospital Emergency Departments, Home Use), By Age Group (Geriatric, Pediatric, Adult), By Application (Insect Sting Allergic Reactions, Food Allergy Induced Anaphylaxis, Drug Induced Anaphylaxis), By Product Type, and By Dosage Strength.
Geographic Distribution and Regional Performance
North America dominates the global revenue share due to high anaphylaxis incidence rates and rapid uptake of novel drug-delivery platforms. Meanwhile, Asia-Pacific emerges as a high-growth region, supported by expanding retail pharmacy networks and rising healthcare expenditure.
In-Depth Regional Review of High-Growth Markets
Regulatory harmonization across key Western markets streamlines product approvals, whereas localized reimbursement policies dictate adoption speed in emerging economies. Localized manufacturing partnerships are increasingly critical to mitigate cross-border logistical hurdles.
Company Profiles and Strategic Positioning
Pioneering firms such as Aquestive Therapeutics leverage specialized polymer engineering to maintain a competitive moat. Their strategic focus centers on clinical trial progression, patent defense, and strategic commercial partnerships with global pharmaceutical distributors.
Porter's Five Forces Analysis of the Sector
Bargaining power of buyers remains moderate due to strict prescription requirements, while threat of substitutes is challenged by the unique pharmacokinetic profile of films. High R&D capital requirements effectively keep threat of new entrants relatively low.
SWOT Analysis of Oral Epinephrine Film For Anaphylaxis Market
Key strengths include needle-free convenience and rapid systemic absorption. Weaknesses involve strict thermal stability storage requirements. Opportunities lie in pediatric market expansion, while threats stem from generic injectable epinephrine auto-injector pricing pressure.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with specialty active pharmaceutical ingredient synthesis, followed by specialized polymer film casting and secondary packaging. Distribution flows through major pharmaceutical wholesalers directly to retail pharmacies, hospitals, and institutional end-users.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize companies developing pediatric-specific low-dose formulations and those with established supply chain resilience. High-potential areas include expanding distribution footprints within school health districts and pediatric allergy clinics.
Conclusion and Strategic Takeaways
The Oral Epinephrine Film For Anaphylaxis Market is poised for explosive growth, backed by compelling clinical advantages over legacy auto-injectors. Stakeholders must align R&D with patient-centric usability to capture outsized market share through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with clinical immunologists, regulatory filing analysis from bodies like the EMA and FDA, and secondary macroeconomic indicators sourced from global trade registries.
Scope of the Report and Coverage Parameters
This report evaluates global market dynamics for oral epinephrine films, covering historical baselines, current valuations, and a granular forecast through 2033. Limitations include restricted data visibility in unregulated gray-market localized distribution channels.
Recent Developments and Industry Catalysts
Recent milestones highlight aggressive patent filings, FDA advisory committee reviews, and strategic commercialization agreements aimed at expanding retail pharmacy shelf-space. These moves signal a maturing market transitioning from late-stage clinical trials to widespread commercial deployment.