What is the scope and industry significance of the Counter-Drone Systems Market?
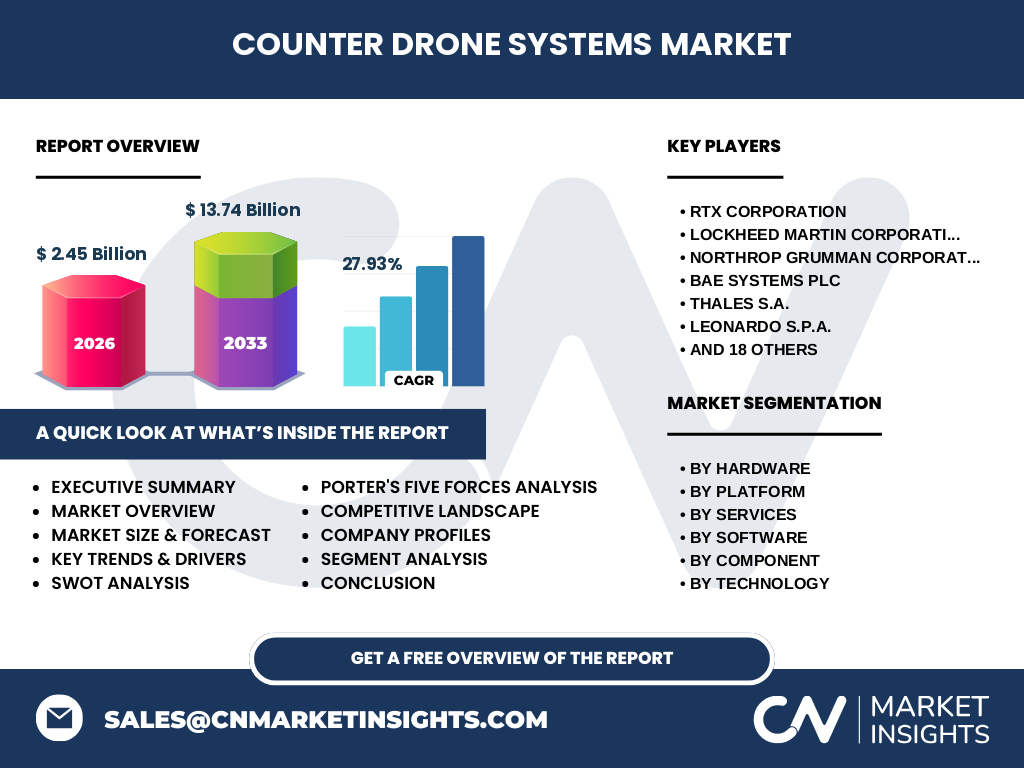
Our analysis indicates the Counter-Drone Systems Market reaches $2.45 Billion in 2026, driven by critical defense imperatives. This sector encompasses advanced hardware like Radar Systems and software such as Command And Control Software designed to mitigate illicit Unmanned Aerial Vehicle incursions across military and commercial sectors.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating geopolitical friction and commercial airspace violations. Strict regulatory frameworks imposed by bodies like the FAA constrain rapid deployment, while technological hurdles in Signal Processing Software remain formidable challenges for manufacturers.
Emerging Trends and Growth Patterns in the Counter-Drone Systems Market
We observe a distinct pivot toward Artificial Intelligence Based Systems to autonomously detect and classify micro-drones. Integration Services are experiencing surging demand as buyers seek to unify disparate Electro Optical Cameras and Jamming Devices into cohesive defense architectures.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially disrupted global supply chains for specialized semiconductor components used in Radio Frequency Sensors. However, accelerated defense digitization post-2021 catalyzed a robust recovery, positioning the Counter-Drone Systems Market for unprecedented post-pandemic expansion.
Competitive Landscape and Strategic Dynamics
Industry concentration is high, dominated by prime defense contractors like RTX Corporation and Lockheed Martin Corporation. Meanwhile, agile innovators like Anduril Industries Inc. and DroneShield Limited leverage proprietary Threat Detection Software to capture high-margin commercial and tactical contracts.
Executive Summary of the Counter-Drone Systems Market Report
Our comprehensive research values the Counter-Drone Systems Market at $2.45 Billion in 2026, scaling dramatically to $13.74 Billion by 2033. Expanding at a remarkable 27.93% CAGR, this market represents a prime investment horizon across Military And Defense and Critical Infrastructure.
Market Forecast from 2027 to 2033
The data projects stellar acceleration, surging from baseline 2026 valuations to $13.74 Billion by 2033. This trajectory reflects a sustained 27.93% CAGR, heavily underpinned by escalating procurement budgets for Laser Weapons and Interceptor Drones globally.
Segmentation Analysis Across Hardware, Software, and Services
The market breaks down by hardware, software, services, component, technology, application, and product type. Key sub-segments include: - Hardware: Radar Systems, Radio Frequency Sensors, Electro Optical Cameras, Infrared Sensors, Acoustic Sensors, Jamming Devices, Laser Weapons, Interceptor Drones - Platform: Ground-Based, Handheld, Unmanned Aerial Vehicle (UAV)-Based, Marine-Based - Services: Installation Services, Maintenance And Support Services, Training And Simulation Services, Consulting Services, Integration Services - Software: Command And Control Software, Data Analytics Software, Artificial Intelligence Based Software, Signal Processing Software, Threat Detection Software, Tracking And Monitoring Software - Component: Hardware, Software, Services - Technology: Radar Systems, Radio Frequency Detection, Electro Optical Systems, Infrared Systems, Acoustic Sensors, Artificial Intelligence Based Systems - Application: Military And Defense, Commercial, Homeland Security, Critical Infrastructure, Other Applications - Product Type: Detection Systems, Jamming Systems, Interception Systems, Laser Systems, Other Product Types
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily skewed toward regions facing heightened airspace security threats. North America maintains dominance due to robust Department of Defense spending, while the Asia-Pacific region demonstrates the fastest adoption rate within Critical Infrastructure and Homeland Security domains.
In-Depth Regional Review of Key Markets
Our analysis indicates North America commands the largest revenue share, anchored by domestic innovators like SRC Inc. and Epirus Inc. Concurrently, European markets are prioritizing border security enhancements, driving demand for solutions offered by Thales S.A. and Rheinmetall AG.
Company Profiles and Strategic Positioning
Industry leaders deploy distinct strategic positioning. Prime contractors like Northrop Grumman Corporation and BAE Systems plc focus on multi-domain integration, while specialized pure-plays such as CERBAIR SAS and Fortem Technologies Inc. target niche tactical Detection Systems and Jamming Systems.
Porter's Five Forces Analysis of Competitive Pressures
Competitive rivalry is intense among established primes, yet threat of new entrants is mitigated by high R&D entry barriers. Buyer power is moderate due to specialized military specifications, while supplier power remains low regarding raw electronic components and rare earth minerals.
SWOT Analysis of the Counter-Drone Systems Industry
Strengths lie in advanced sensor fusion and rapid deployment capabilities. Weaknesses involve high initial capital expenditures. Opportunities abound in Critical Infrastructure protection, whereas threats stem from rapidly evolving drone evasion tactics and complex regulatory hurdles.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying rare earths for Infrared Sensors. Midstream manufacturers assemble Laser Weapons and Radar Systems, while downstream integrators deliver complete solutions to Military And Defense end-users via Integration Services.
Investment Insights and High-Potential Areas
Investors should target early-stage developers specializing in Artificial Intelligence Based Software and Tracking And Monitoring Software. These high-potential domains offer exceptional scalability as autonomous threat mitigation becomes the mandatory standard for Commercial applications.
Conclusion and Key Takeaways for Industry Stakeholders
The Counter-Drone Systems Market represents a high-growth frontier, scaling to $13.74 Billion by 2033 at a 27.93% CAGR. Stakeholders must prioritize software-defined capabilities and strategic partnerships to capture emerging opportunities across global defense ecosystems.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with defense executives, and secondary macroeconomic indicators. This multi-layered methodology ensures highly accurate market sizing for the Counter-Drone Systems Market.
Scope of the Report and Coverage Parameters
This report covers global developments in the Counter-Drone Systems Market through 2033. Limitations include restricted access to classified military procurement data, though extensive secondary validation compensates to provide an exhaustive industry overview.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity highlights aggressive cross-border partnerships and technological acquisitions. Companies like Elbit Systems Ltd. and Saab AB have recently unveiled advanced counter-UAS suites, signaling a concerted industry push toward integrated Interception Systems and mobile Marine-Based platforms.