What is the market overview and scope of the Spatial Analytics Platform Market?
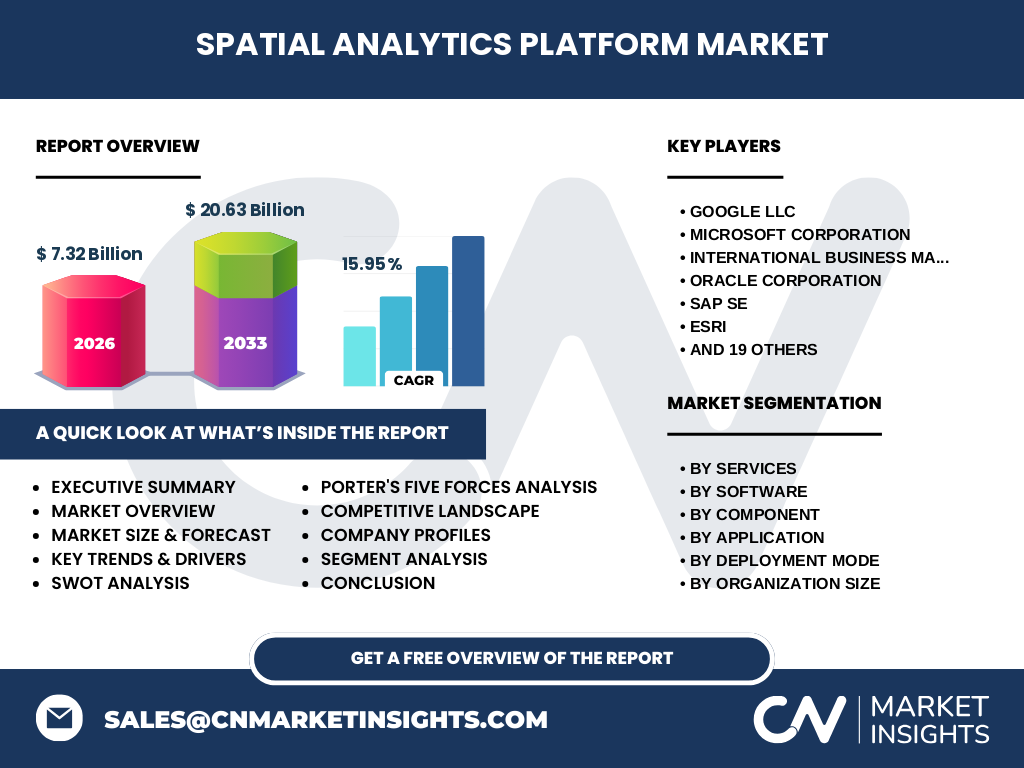
Our analysis indicates that the Spatial Analytics Platform Market is valued at $7.32 Billion in 2026, establishing a critical foundation for location-based intelligence. This sector encompasses advanced software and services that ingest geospatial coordinates, satellite feeds, and IoT data streams to drive enterprise decision-making across global supply chains and municipal infrastructure.
What are the structural growth drivers and market restraints shaping the Spatial Analytics Platform Market industry trends?
Structural expansion is propelled by rapid urban agglomeration and the proliferation of IoT sensors feeding real-time telemetry. However, data privacy mandates from regulatory bodies like the European Union's GDPR create compliance hurdles. Platform adoption heavily favors organizations capable of navigating complex cross-border data sovereignty requirements without sacrificing processing velocity.
The Shift Toward Cloud-Native Architectures: Emerging trends in Spatial Analytics Platform Market analysis
The industry is undergoing a definitive migration from legacy on-premises installations to hyper-scale cloud environments. Vendors are embedding machine learning models directly into mapping suites to automate feature extraction from remote sensing feeds. This technical evolution accelerates time-to-insight for asset-heavy sectors like utilities and multimodal transportation networks.
How did the pandemic impact the Spatial Analytics Platform Market market size and trajectory?
During the pandemic, remote workforce mandates accelerated the deployment of cloud-based location intelligence tools for asset tracking and epidemiological mapping. Post-crisis recovery generated a CAGR of 15.95% as logistics providers and retail conglomerates sought resilient spatial modeling platforms to mitigate supply chain disruptions.
Competitive Benchmarking: Major players and strategic dynamics
The market features a consolidated core of enterprise tech giants including Google LLC, Microsoft Corporation, and Esri, alongside specialized geospatial innovators like Planet Labs and CARTO. Market leaders leverage strategic acquisitions and cloud integrations to bundle remote sensing software with advanced location intelligence capabilities, locking enterprises into proprietary ecosystems.
Executive Summary of the Spatial Analytics Platform Market
Our research forecasts the Spatial Analytics Platform Market to reach $20.63 Billion by 2033, expanding at a robust CAGR of 15.95% from 2027. Enterprise investments are increasingly concentrated on cloud deployment modes and managed services that streamline spatial data processing without requiring massive internal GIS engineering teams.
Market Forecast and Trajectory for the Spatial Analytics Platform Market
Driven by accelerating 5G rollouts and smart city investments, the market will scale aggressively from its 2026 valuation to $20.63 Billion by 2033. Sequential analysis reveals that cloud infrastructure services and spatial modeling software will capture the lion's share of this incremental capital expenditure.
Segmentation Analysis: Software, Services, Deployment, and Applications
The market bifurcates into software and services, with software encompassing GIS, remote sensing, and location intelligence tools. Services range from consulting to managed deployments. Applications span urban planning, environmental monitoring, and retail analytics. Large enterprises currently dominate consumption, though small and medium enterprises are rapidly adopting cloud-based solutions.
Regional Market Performance and Geographic Distribution
Geographic performance reflects varying concentrations of smart infrastructure investments and regulatory maturity. North America maintains the highest market share due to early adoption by federal agencies and logistics leaders. Meanwhile, Asia-Pacific exhibits the fastest growth velocity, fueled by massive urbanization projects and government-backed geospatial initiatives in emerging economies.
In-Depth Regional Review of High-Growth Geographies
In North America, demand is anchored by federal defense contracts and advanced retail site selection modeling. In contrast, European markets prioritize environmental monitoring and strict adherence to spatial data privacy regulations. Regional suppliers must tailor their compliance frameworks to local statutory bodies to capture sustainable enterprise contracts.
Company Profiles and Strategic Positioning
Industry participants deploy distinct value propositions to capture market share. Esri maintains dominance in traditional GIS, while Amazon Web Services and Microsoft Corporation leverage cloud infrastructure dominance. Specialized players like Mapbox and TomTom N.V. carve out defensible niches in navigation software and developer-friendly location APIs.
Porter's Five Forces Analysis of Competitive Intensity
Rivalry is intense among established GIS vendors and cloud hyperscalers offering native spatial extensions. Buyer power remains moderate-to-high, as enterprises demand interoperable spatial data processing tools. Threat of substitutes is mitigated by the sheer complexity of handling multi-terabyte vector and raster datasets without specialized infrastructure.
SWOT Analysis: Evaluating the Spatial Analytics Platform Market
Strengths include high precision in predictive modeling and robust multi-source data ingestion. Weaknesses involve steep learning curves for advanced spatial simulation software. Opportunities lie in integrating generative AI with satellite imagery. Threats stem from escalating cybersecurity vulnerabilities targeting critical utility and transportation grid maps.
Value Chain Analysis from Raw Data to End-Users
The value chain originates with raw data acquisition from satellite operators like Planet Labs and IoT sensor arrays. Middle-tier software vendors process these inputs via geospatial algorithms. Finally, system integrators and consultants deliver tailored dashboards to end-users in healthcare, retail, and urban planning.
Investment Insights and Strategic Recommendations
Investors should direct capital toward cloud-native spatial modeling startups and managed services providers addressing the GIS talent shortage. High-potential areas include real-time supply chain tracking platforms and automated geocoding tools that reduce enterprise friction during digital transformation initiatives.
Conclusion and Key Takeaways for Industry Stakeholders
The Spatial Analytics Platform Market represents a high-growth investment opportunity, projected to hit $20.63 Billion by 2033. Stakeholders must prioritize cloud deployment flexibility and AI-driven spatial data visualization capabilities to capture discerning enterprise clients across regulated vertical markets.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived by triangulating primary stakeholder interviews with C-level geospatial executives, secondary macroeconomic indicators, and trade registry filings. Rigorous quantitative modeling cross-references regional software licensing revenues with cloud infrastructure consumption metrics to ensure high-fidelity market sizing.
Scope of the Report and Coverage Parameters
This report evaluates the global Spatial Analytics Platform Market across software, services, deployment modes, and organization sizes from 2026 to 2033. Limitations include excluding unverified open-source GIS tools lacking commercial enterprise support contracts and proprietary internal defense systems.
Recent Developments and Strategic Industry Moves
Recent market activity highlights aggressive partnerships between cloud hyperscalers and spatial software vendors to streamline satellite data processing. Major industry announcements feature product launches centered on AI-powered geocoding and real-time mapping APIs designed to optimize urban logistics and autonomous vehicle navigation.