What is the market overview and industry significance of the Aerospace And Defense Biometrics Market?
Our analysis indicates that the Aerospace And Defense Biometrics Market stands at a critical juncture of national security and digital transformation, reaching $13.04 Billion in 2026. This sector encompasses advanced identification solutions deployed by defense agencies and aerospace primes to secure restricted facilities, manage borders, and authenticate military personnel. The industry is foundational for countering sophisticated cyber-physical threats, integrating biometric hardware, specialized software, and mission-critical services into secure government infrastructures.
Key market drivers, restraints, challenges, and opportunities shaping Aerospace And Defense Biometrics Market
Based on our research, surging cross-border security threats and military modernization initiatives act as primary structural drivers, accelerating the adoption of automated border control software and iris scanners. Conversely, strict compliance mandates and high implementation costs represent notable restraints. Integrating legacy hardware with cloud-based architectures poses persistent engineering challenges, while significant opportunities emerge in developing tamper-proof multimodal biometrics for tactical battlefield deployment.
Emerging trends and growth patterns in Aerospace And Defense Biometrics Market
The data suggests a decisive shift toward multimodal biometric systems that combine facial recognition cameras and palm vein recognition to eliminate single-point authentication vulnerabilities. Defense contractors are increasingly prioritizing edge-computing capabilities within handheld biometric devices, enabling real-time criminal identification and forensics in disconnected operational environments without relying on vulnerable cloud uplinks.
How did the COVID-19 pandemic affect Aerospace And Defense Biometrics Market and what is the recovery trajectory?
The pandemic caused temporary supply chain disruptions for rare earth raw materials needed in fingerprint scanners, yet it ultimately accelerated demand for contactless technologies. Post-COVID recovery trajectories show aggressive defense spending reallocations toward touchless facial recognition software and automated border control solutions designed to minimize physical touchpoints during high-volume passenger processing across international airports.
Competitive benchmarking and strategic dynamics in the Aerospace And Defense Biometrics Market
Market concentration is high, dominated by aerospace primes and defense contractors like Lockheed Martin Corporation, Northrop Grumman Corporation, and Thales Group. These giants leverage extensive government contracting networks to deploy comprehensive identity management platforms. Meanwhile, agile technology innovators such as IDEMIA Group and HID Global Corporation drive competitive pressure through proprietary software algorithms and advanced border security integrations.
Executive summary of key findings
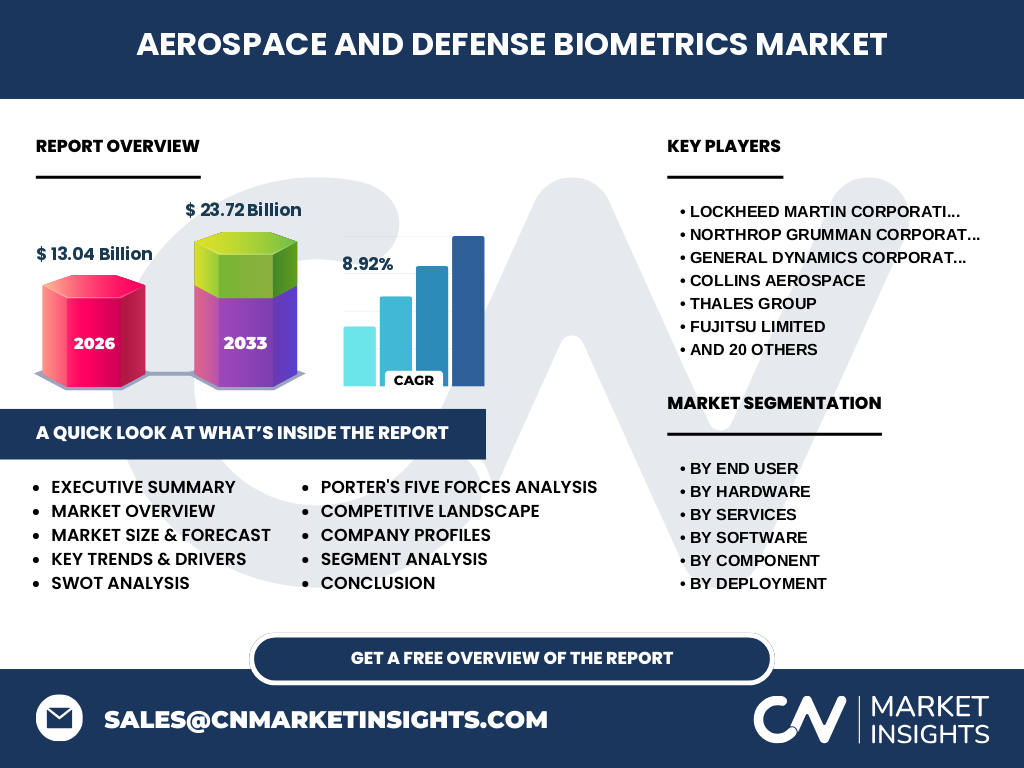
Our proprietary analysis projects the Aerospace And Defense Biometrics Market to expand from $13.04 Billion in 2026 to $23.72 Billion by 2033, achieving a robust CAGR of 8.92%. Growth is anchored by heavy investments from intelligence agencies and homeland security departments seeking secure, automated identification frameworks. Companies that master multimodal integration and resilient cloud deployment will capture disproportionate market share.
Market forecast from 2027 to 2033
The market is poised for accelerated expansion, scaling from its 2026 baseline of $13.04 Billion to reach $23.72 Billion by 2033 at a compound annual growth rate of 8.92%. This trajectory is fueled by continuous modernization cycles within military and defense organizations, alongside rising demand for automated border control software and rigorous access control infrastructure.
Segmentation analysis across end-users, hardware, software, services, and technology
The Aerospace And Defense Biometrics Market segments into distinct operational pillars. By End User: Military And Defense, Homeland Security, Law Enforcement Agencies, Intelligence Agencies, Government Organizations. By Hardware: Fingerprint Scanners, Facial Recognition Cameras, Iris Scanners, Voice Recognition Devices, Handheld Biometric Devices. By Services: System Integration, Consulting, Maintenance, Training, Managed Security. By Software: Biometric Identification, Facial Recognition, Identity Management, Automated Border Control, Data Analytics. By Component: Hardware, Software, Services. By Deployment: On Premises, Cloud-Based. By Technology: Fingerprint Recognition, Face Recognition, Iris Recognition, Voice Recognition, Palm Vein Recognition, DNA Biometrics, Signature Recognition, Multimodal Biometrics. By Application: Access Control, Surveillance, Payment, Border Control, Intelligence, Criminal Identification, Personnel Authentication.
Regional market analysis and geographic performance distribution
Geographic performance reflects divergent national security priorities and defense budget allocations. North America dominates global revenues due to extensive homeland security initiatives by agencies utilizing advanced technologies from firms like Peraton Inc. and Leidos Holdings Inc. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate, propelled by rapid military modernization and large-scale border digitization programs across emerging economies.
In-depth regional review of key operational zones
In North America, strict federal mandates regarding personnel authentication drive widespread adoption of advanced identification platforms. Europe exhibits strong demand for automated border control software, driven by regional immigration pacts and stringent Schengen area monitoring. In the Middle East and Africa, escalating investments in critical infrastructure defense favor the deployment of high-end facial recognition cameras and iris scanners provided by international prime contractors.
Company profiles and strategic positioning of leading market participants
Industry leaders occupy distinct strategic niches. General Dynamics Corporation and Collins Aerospace integrate biometrics directly into aerospace avionics and secure defense platforms. NEC Corporation and Fujitsu Limited supply world-class facial recognition software and multimodal algorithms. Meanwhile, specialized defense specialists like CACI International Inc., Elbit Systems Ltd., and QinetiQ Group plc deliver tailored intelligence and reconnaissance solutions for tactical military operations.
Porter's Five Forces analysis of the competitive landscape
The threat of new entrants remains low due to stringent government clearance protocols, high R&D costs, and strict certification standards. Bargaining power of buyers is moderate to high, as large defense agencies dictate strict performance criteria. Supplier power is tempered by specialized component manufacturing, while competitive rivalry is intense among established contractors like L3Harris Technologies Inc. and Northrop Grumman Corporation.
SWOT analysis of the Aerospace And Defense Biometrics Market
Strengths include high system reliability and mission-critical accuracy in hostile environments. Weaknesses involve vulnerabilities in legacy integration and high deployment costs. Opportunities lie in expanding cloud-based identity management platforms for decentralized forces. Threats encompass sophisticated cyberattacks targeting biometric databases and strict data privacy regulations governing civilian border control data.
Value chain analysis from raw materials to end-users
The value chain initiates with silicon wafer and semiconductor procurement for hardware sensors, progressing through optical lens fabrication and biometric algorithm coding by software developers such as Aware Inc. and Daon Inc. System integrators then package these elements with maintenance and support services before deployment to end-users like law enforcement agencies and military branches.
Investment insights and strategic recommendations
Investors should target niche innovators specializing in Deoxyribonucleic Acid Biometrics and multimodal fusion algorithms, as these technologies represent the next frontier in secure personnel identification. Partnerships with established prime contractors like Lockheed Martin Corporation offer the most reliable pathway to securing lucrative, long-term government defense contracts.
Conclusion and key takeaways for industry stakeholders
The Aerospace And Defense Biometrics Market offers compelling growth prospects, scaling from $13.04 Billion in 2026 to $23.72 Billion by 2033. Stakeholders must prioritize investment in cloud-agnostic architectures, multimodal recognition software, and resilient cybersecurity frameworks to capture value across military, intelligence, and border control verticals.
Research methodology and baseline estimation triangulation
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, defense budget registries, and primary stakeholder interviews with chief technology officers across top-tier firms like SAIC, ManTech International Corporation, and Secunet Security Networks AG. Quantitative models cross-reference historical procurement data with projected geopolitical threat assessments.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment of biometric hardware, software, and services across military, homeland security, and law enforcement end-users from 2026 through 2033. Limitations include restricted access to classified military black-budget allocations and proprietary intelligence agency deployments, which are estimated via secondary macroeconomic proxies.
Recent developments in company announcements, product launches, and strategic partnerships
Recent industry momentum is characterized by strategic acquisitions and technological alliances. Companies such as IDEMIA Group and HID Global Corporation have launched next-generation contactless biometric readers designed for high-throughput military installations. Simultaneously, partnerships between defense contractors and software specialists like Neurotechnology UAB and M2SYS Technology Inc. aim to enhance edge-computing security for deployed tactical units.