What is the scope and industry significance of the Hypersonic Defense Market?
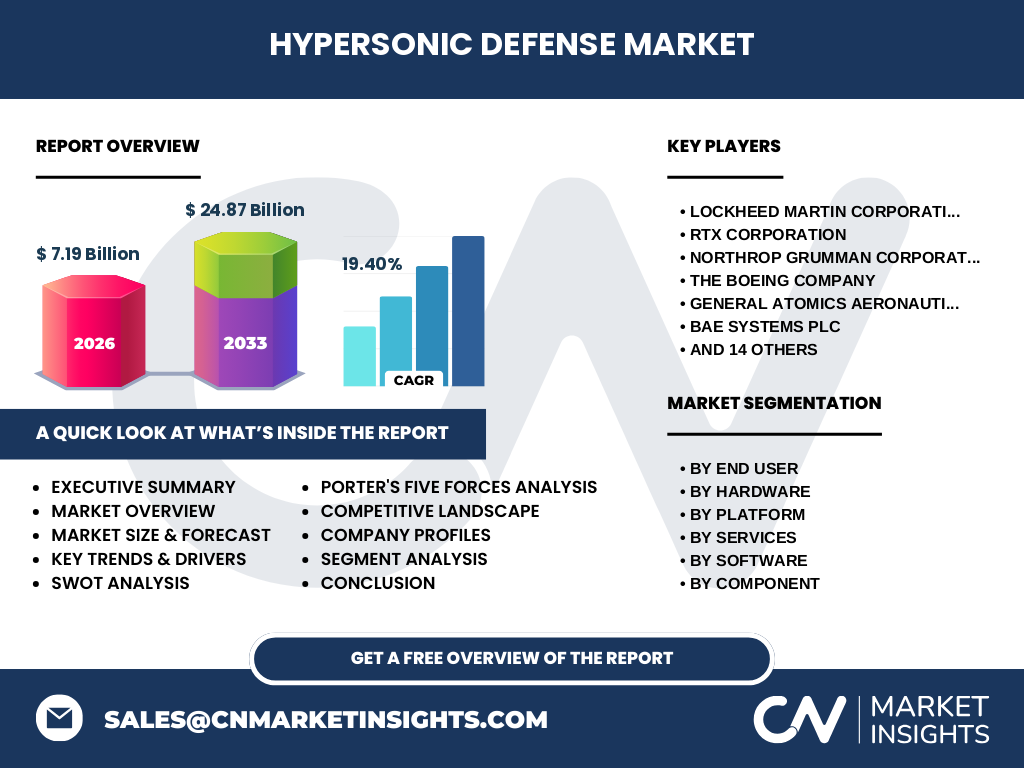
Our analysis indicates that the Hypersonic Defense Market represents a critical frontier in modern military preparedness, valued at 7.19 Billion in 2026. This sector encompasses advanced interceptors, early-warning sensor architectures, and specialized command systems designed to counter high-velocity glide vehicles. Strategic significance stems from the urgent need to protect national airspace against maneuvering threats traveling above Mach 5.
Structural Growth Drivers and Restraints
The data suggests that escalating geopolitical tensions and rapid proliferation of Mach-plus weaponry are primary catalysts. Strong defense budgets are fueling massive procurement cycles, though supply chain bottlenecks for ultra-high-temperature ceramics and complex regulatory export controls under ITAR regulations continue to act as notable operational restraints for prime contractors.
Emerging Trends in the Hypersonic Defense Market
Industry trends highlight a decisive pivot toward digitized threat analysis software and resilient space-based infrared sensor constellations. Defense agencies are prioritizing modular architectures that integrate seamlessly with legacy command networks, allowing firms like Palantir Technologies Inc. to deploy advanced mission planning tools directly to active operational theaters.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic introduced severe supply chain disruptions and labor shortages across specialized aerospace manufacturing hubs. However, our research shows that government intervention and classified funding pipelines insulated the sector, resulting in a robust recovery trajectory that directly accelerated the current 19.40% CAGR forecast.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains high among prime contractors possessing deep aerospace engineering heritage. Firms such as Lockheed Martin Corporation, RTX Corporation, and Northrop Grumman Corporation dominate prime integration, leveraging vast R&D budgets to secure multi-billion-dollar interceptor development contracts while smaller technology innovators focus on niche sensor components.
Executive Summary of the Hypersonic Defense Market
Our comprehensive report reveals a thriving sector projected to surge from 7.19 Billion in 2026 to 24.87 Billion by 2033 at a CAGR of 19.40%. Accelerated threat evolution is driving unprecedented investments in thermal protection systems, advanced propulsion, and multi-layered detection architectures globally.
Market Forecast from 2027 to 2033
The data projects consistent, aggressive expansion throughout the forecast window, culminating in a market valuation of 24.87 Billion by 2033. This trajectory is underpinned by sustained, long-term government procurement commitments and rapid technological maturation moving from experimental flight tests to full-scale operational deployment.
Segmentation Analysis Across Categories
Segmentation spans multiple critical domains: by end user (Military, Homeland Security, Other), hardware (Launch Systems, Guidance Navigation, Propulsion, Thermal Protection, Sensors, Communication), platform (Land, Naval, Airborne, Space), services, software, component, and technology. Propulsion and sensor technologies capture the highest value share due to extreme engineering demands.
Regional Market Analysis and Geographic Distribution
North America commands the largest revenue share, driven by aggressive Pentagon spending and initiatives by agencies like the Missile Defense Agency. Meanwhile, the Asia-Pacific region demonstrates the fastest relative growth, spurred by regional arms buildups and escalating investments in domestic counter-hypersonic interceptor programs by nations like Japan.
In-Depth Regional Review
European markets are increasingly focused on collaborative defense initiatives through bodies like the European Defence Agency, with firms such as MBDA Missile Systems spearheading joint interceptor studies. Concurrently, North American testing facilities at White Sands and the Pacific Missile Range Facility remain central to validation.
Company Profiles and Strategic Positioning
Leading industry participants employ distinct growth strategies. Raytheon (RTX) and Lockheed Martin focus on end-to-end interceptor systems, whereas Kratos Defense & Security Solutions Inc. specializes in low-cost target drones and hypersonic testbeds, providing critical validation infrastructure for the broader defense ecosystem.
Porter's Five Forces Analysis
Our analysis indicates moderate-to-high barriers to entry due to extreme capital expenditure requirements and stringent security clearance mandates. Buyer power is heavily concentrated among national defense ministries, while threat of substitution is low given the unique physical challenges of intercepting Mach 5 targets.
SWOT Analysis of the Sector
Strengths include unmatched technological innovation and robust state backing. Weaknesses involve lengthy procurement cycles. Opportunities lie in space-based tracking layers and software integration, while threats encompass severe supply chain vulnerabilities for raw materials like carbon-carbon composites and stringent geopolitical export controls.
Value Chain Analysis
The value flow initiates with raw material providers supplying specialized alloys and thermal insulators, moving through tier-one subsystem integrators like Honeywell International Inc. and L3Harris Technologies Inc., culminating in final platform assembly by prime contractors and ultimate deployment by military end-users.
Investment Insights and High-Potential Areas
Investors should focus on firms specializing in thermal protection systems and artificial intelligence-driven threat analysis software. These niches offer superior margin potential as defense organizations increasingly prioritize software-defined defense capabilities and survivable materials capable of withstanding extreme aerodynamic heating.
Conclusion and Key Takeaways
The Hypersonic Defense Market is undergoing a paradigm shift, expanding at a remarkable 19.40% CAGR toward a 24.87 Billion valuation by 2033. Success in this landscape requires mastering advanced material science, secure software integration, and agile manufacturing partnerships.
Research Methodology
Our findings are derived by triangulating primary stakeholder interviews with defense procurement officers, exhaustive trade registry data from aerospace manufacturing hubs, and secondary macroeconomic indicators regarding global defense budget allocations, ensuring high analytical fidelity and actionable market intelligence.
Scope of the Report
This report covers global deployment dynamics, technology breakdowns, and competitive positioning across North America, Europe, Asia-Pacific, and rest-of-world markets. Limitations include restricted access to strictly classified black-budget defense programs, focusing instead on publicly disclosed procurement contracts and industry-verified R&D expenditures.
Recent Developments in the Industry
Recent strategic moves include major contract awards for glide-phase interceptor development involving Northrop Grumman Corporation and L3Harris Technologies Inc., alongside cross-border technological partnerships aimed at accelerating sensor fusion capabilities and expanding flight-testing infrastructure across allied defense networks.