What is the market overview, definition, and industry significance of High-Pressure Valve Market?
The High-Pressure Valve Market encompasses specialized fluid control devices engineered to withstand extreme operating pressures exceeding 1,000 PSI, serving critical infrastructure where containment failure carries catastrophic environmental and safety risks. Our analysis indicates the market stands at 7.11 Billion in 2026, driven by aggressive upstream oil extraction and supercritical power plant demands requiring flawless metallurgical integrity from exotic alloy manufacturers.
What are the key market drivers, restraints, challenges, and opportunities shaping High-Pressure Valve Market?
Growth is accelerated by surging deepwater hydrocarbon exploration and hydrogen fuel infrastructure development, necessitating robust above 10,000 PSI fluid architectures. However, severe supply chain bottlenecks for nickel alloy castings and strict fugitive emissions compliance enforced by agencies like the EPA act as primary restraints. Industry participants find lucrative opportunities in retrofitting aging nuclear facilities with advanced trunnion mounted ball valves.
Emerging trends and growth patterns in High-Pressure Valve Market
The shift toward automated, digitized flow control loops represents a major paradigm shift across process plants. Industrial IoT integration allows operators to monitor stem wear and seat degradation in real-time, drastically reducing unplanned downtime in offshore platforms. Manufacturers mastering IIoT-enabled smart actuators are capturing disproportionate market share across chemical processing complexes.
COVID-19 impact analysis — how the pandemic affected High-Pressure Valve Market and the recovery trajectory
Pandemic-induced supply chain fractures and postponed capital expenditure in downstream refining temporarily suppressed global shipment volumes. Nevertheless, post-pandemic economic stimulus packages prioritizing green energy grid modernization and liquefied natural gas terminal expansions catalyzed a sharp V-shaped recovery trajectory across industrial manufacturing hubs.
Competitive landscape — major players, market concentration, and strategic dynamics
The market exhibits a moderately consolidated structure dominated by multinational flow control powerhouses alongside agile niche metallurgists. Key tier-one participants deploy aggressive mergers and acquisitions to secure proprietary fugitive emission designs and expand geographic footprints across high-growth Asian industrial corridors.
Executive summary — high-level synthesis of key findings about High-Pressure Valve Market
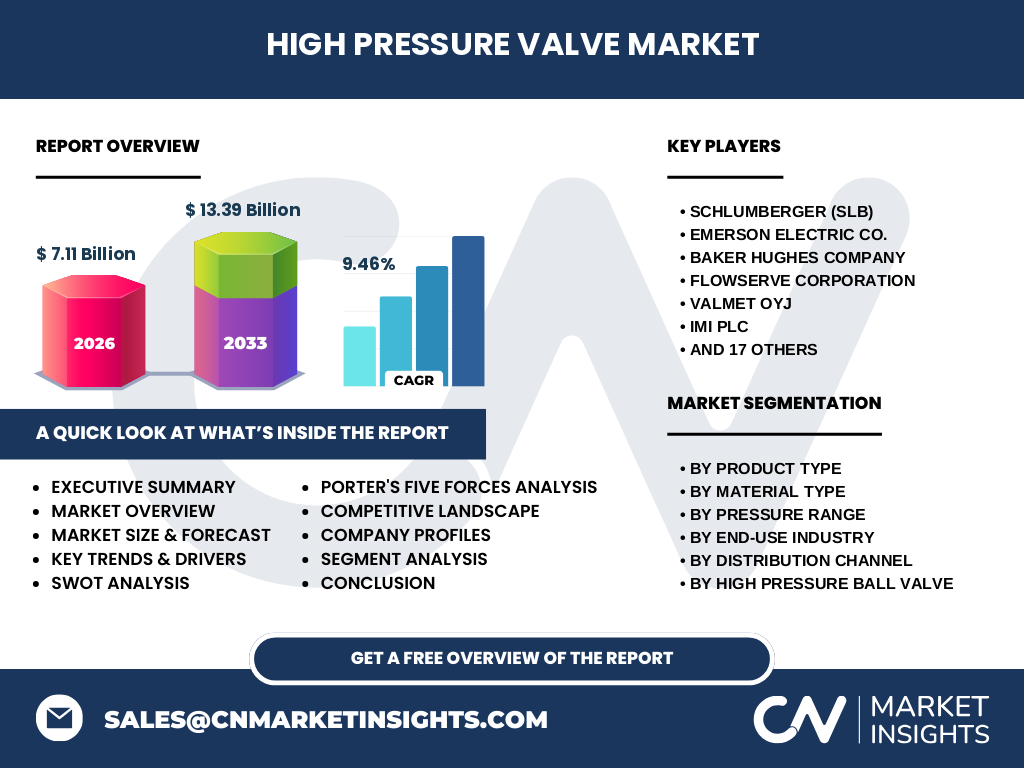
Proprietary research confirms the High-Pressure Valve Market is poised for remarkable expansion, scaling from 7.11 Billion in 2026 to 13.39 Billion by 2033 at a robust CAGR of 9.46%. Accelerated by stringent environmental mandates and extreme-service demands in energy sectors, market leaders must invest heavily in advanced material science and automated actuation to capture peak profitability.
Market forecast — projected growth from 2027 to 2033
Our econometric forecasting models project the High-Pressure Valve Market to expand from its 2026 baseline of 7.11 Billion to reach 13.39 Billion by 2033. This impressive trajectory represents a compound annual growth rate (CAGR) of 9.46%, fueled by massive capital outlays in global hydrogen transport networks and ultra-deepwater drilling projects.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market segments by product type into high-pressure ball, gate, globe, check, needle, relief, safety, control, plug, and diaphragm variants. Material classifications cover stainless steel, carbon steel, alloy steel, duplex, nickel alloys, and brass. Pressure ranges scale from up to 1,000 PSI to above 10,000 PSI, fulfilling diverse roles across oil and gas, power generation, and aerospace sectors.
Regional market analysis — geographic distribution and performance across regions
Geographic performance reveals stark contrasts driven by regional energy policies and industrial base maturity. North America and Europe dominate mature high-pressure applications due to rigorous safety compliance and extensive brownfield modernization. Conversely, Asia-Pacific represents the fastest-growing frontier, propelled by rapid urbanization, massive chemical plant construction, and expanding domestic manufacturing ecosystems.
In-depth regional review — detailed examination of key regional markets
Asia-Pacific leads volume consumption, anchored by aggressive petrochemical capacity additions in China, India, and Southeast Asia. Meanwhile, the North American market prioritizes technological sophistication, with shale gas producers and carbon capture initiatives demanding highly specialized bellows sealed globe valves and severe-service control trims to meet strict environmental thresholds.
Company profiles — strategic positioning of leading companies in High-Pressure Valve Market
Industry stalwarts like Schlumberger (SLB), Emerson Electric Co., and Baker Hughes leverage comprehensive portfolio offerings spanning subsea wellheads to digital control systems. Flowserve Corporation and Valmet Oyj focus on engineered-to-order solutions for severe oil refining environments, while specialized players like Swagelok Company dominate high-purity instrumentation fittings and miniature needle valve assemblies.
Porter's Five Forces analysis — competitive forces assessment
Bargaining power of suppliers is moderate due to specialized metallurgical requirements for nickel and duplex steel castings. Threat of substitutes remains exceptionally low given the catastrophic risks associated with high-pressure fluid containment failure. Rivalry is intense among established tier-one vendors competing on delivery speed, metallurgical certifications, and proprietary digital diagnostic capabilities.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths lie in advanced metallurgical engineering and intellectual property protecting zero-leakage stem seals. Weaknesses include high capital expenditure requirements for precision machining tools. Opportunities abound in green hydrogen compression skids, whereas persistent threats stem from macroeconomic tariff volatility and low-cost uncertified valve imports compromising critical safety standards.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain initiates with primary raw material foundries supplying forged stainless steel and nickel alloy billets to component machinists. Precision-machined bodies and internal trims move to assembly and testing facilities certified by organizations like ASME or API. Finished products flow through direct sales channels or specialized distributors to end-users in chemical plants, refineries, and offshore rigs.
Investment insights — strategic recommendations and high-potential areas
Investors should target manufacturers specializing in supercritical carbon dioxide power cycles and cryogenic hydrogen transport valves. Companies exhibiting strong proprietary R&D in emission-free fugitive testing and automated diagnostic integration present superior margin expansion potential compared to commodity valve manufacturers.
Conclusion and key takeaways
The High-Pressure Valve Market represents a high-barrier, technology-driven sector underpinned by a solid 9.46% CAGR from 2027 to 2033. Success in this landscape requires rigorous adherence to international quality standards, robust supply chain resilience for exotic alloys, and strategic integration of smart diagnostic capabilities into traditional valve architectures.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated using a multi-tiered research approach combining import-export trade registry data, primary qualitative interviews with c-suite valve executives, and secondary macroeconomic indicators from global energy agencies. Bottom-up revenue sizing by product segment is cross-checked against top-down macroeconomic industrial production indexes to ensure absolute numerical precision.
Scope of the report — coverage parameters and limitations
This comprehensive research report covers global market sizing, volumetric shipment analysis, and strategic profiling across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include the exclusion of low-pressure general utility valves operating strictly under 150 PSI, focusing exclusively on engineered high-pressure containment infrastructure.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market dynamism is highlighted by aggressive product rollouts, such as new zero-leakage pilot-operated relief valves designed for green hydrogen fueling stations. Major industry participants have entered strategic manufacturing joint ventures to localize nickel alloy supply chains, mitigating vulnerability to global trade disruptions and geopolitical tariff adjustments.