Market Overview of Once-Weekly Basal Insulin Therapy Market
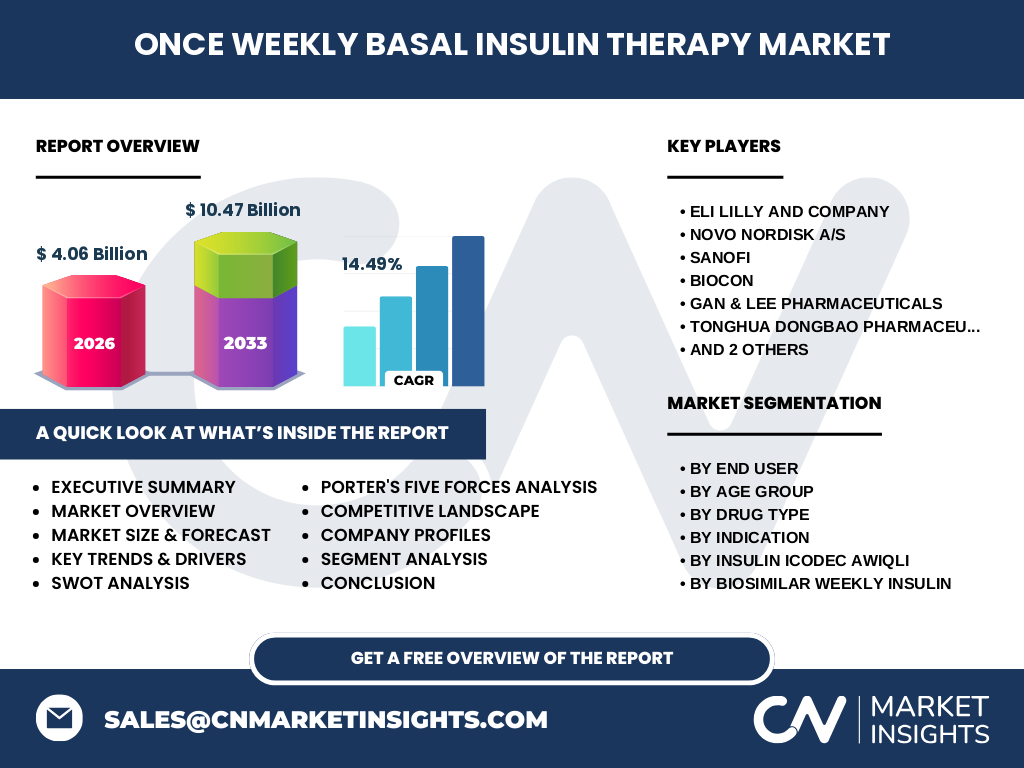
Our analysis indicates the Once-Weekly Basal Insulin Therapy Market represents a paradigm shift in endocrinology, valued at $4.06 Billion in 2026. This sector encompasses advanced subcutaneous formulations designed to reduce injection frequency for diabetic patients, replacing traditional daily basal regimens with engineered molecules featuring extended half-lives.
Structural Growth Drivers and Market Restraints
The market is propelled by the urgent need to mitigate injection fatigue and improve adherence among Type 1 and Type 2 diabetes cohorts. Conversely, strict regulatory hurdles enforced by agencies like the US FDA and EMA, alongside complex cold-chain logistical hurdles for biologic distribution, act as notable restraints.
Emerging Trends in the Once-Weekly Basal Insulin Therapy Market Industry
The data suggests a rapid pivot toward Next Generation Ultra Long Acting Insulin and smart delivery mechanisms. Innovations focusing on hepato-preferential action and glucose-responsive formulations are redefining therapeutic parameters, heavily favored by leading biologic developers seeking portfolio differentiation.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic severely disrupted clinical trial recruitment and delayed regulatory reviews for novel basal peptides. However, post-pandemic healthcare modernization accelerated telemedicine adoption and remote patient monitoring, creating a resilient recovery trajectory for self-administered weekly therapies.
Competitive Benchmarking and Market Concentration
Industry leadership is highly concentrated among established biopharmaceutical giants leveraging robust proprietary delivery devices. Companies like Novo Nordisk A/S and Eli Lilly and Company dominate commercialization pathways, while specialized device manufacturers like Gerresheimer AG supply critical prefilled pen components.
Executive Summary of the Once-Weekly Basal Insulin Therapy Market Analysis
Our research underscores unprecedented expansion, projecting the market to surge from $4.06 Billion in 2026 to $10.47 Billion by 2033 at a robust CAGR of 14.49%. This trajectory reflects immense clinical demand for simplified glycemic control protocols across global geriatric and adult populations.
Market Forecast Projections from 2027 to 2033
Driven by widespread commercial adoption of breakthrough molecules, our projections confirm a stellar 14.49% CAGR. The market will expand exponentially, reaching the $10.47 Billion valuation threshold by 2033 as biosimilar competition enters emerging regional economies.
Segmentation Analysis Across Therapeutic and Care Settings
Segmentation spans drug types including Insulin Icodec Awiqli, Biosimilar Weekly Insulin, and next-generation agents. End-user deployment covers ambulatory care centers, hospitals, specialized diabetes care clinics, and homecare settings, addressing diverse patient demographics from pediatric to geriatric cohorts.
Regional Market Analysis and Geographic Distribution
Geographically, North America currently captures the largest revenue share due to high healthcare expenditure and rapid adoption of advanced biologics. Meanwhile, Asia-Pacific emerges as the fastest-growing territory, propelled by expanding patient pools and improving healthcare infrastructure in localized urban centers.
In-Depth Regional Review of Adoption Barriers
While Western markets grapple with payer reimbursement negotiations and formulary restrictions, developing regions face cold-chain distribution constraints. Overcoming these logistical bottlenecks at regional shipping hubs remains vital for market penetration among price-sensitive populations.
Strategic Positioning of Leading Company Profiles
Market participants deploy distinct growth strategies; Sanofi and Biocon focus on expanding biosimilar pipelines, whereas Ypsomed Holding AG innovates advanced auto-injector platforms. Regional players like Gan & Lee Pharmaceuticals and Tonghua Dongbao Pharmaceutical Co. Ltd. aggressively target domestic high-volume manufacturing.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate to high due to stringent insurer formulary controls. Conversely, threat of new entrants is low given the prohibitive capital requirements for biologic R&D, stringent regulatory approvals, and complex patent portfolios protecting current market leaders.
SWOT Analysis of the Once-Weekly Basal Insulin Therapy Market
Strengths lie in superior patient adherence and breakthrough pharmacokinetic profiles. Weaknesses involve high treatment costs. Opportunities exist in untapped emerging markets, while threats include potential pricing pressures from generic alternatives and unforeseen long-term immunogenicity signals.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with recombinant DNA technology and amino acid synthesis, moving through aseptic formulation and prefilled pen assembly by partners like Gerresheimer AG. Distribution flows through cold-chain logistics networks directly to hospitals, clinics, and homecare end-users.
Investment Insights and High-Potential Areas
Strategic capital allocation should target proprietary device design, smart insulin formulations, and localized manufacturing partnerships in high-growth developing economies. Investors stand to gain significantly by backing firms optimizing subcutaneous delivery technologies.
Conclusion and Key Takeaways for Industry Stakeholders
The Once-Weekly Basal Insulin Therapy Market represents a transformative commercial opportunity, backed by a definitive 14.49% CAGR through 2033. Stakeholders must prioritize R&D in biosimilars and user-friendly delivery devices to secure sustainable competitive advantages.
Research Methodology for Baseline Triangulation
Our analytical framework triangulates baseline estimates by cross-referencing primary stakeholder interviews with key opinion leaders, trade registry data from regulatory authorities, and macroeconomic indicators to ensure robust, empirically grounded market sizing.
Scope of the Report and Analytical Limitations
This report evaluates global market dynamics, therapeutic segmentations, and competitive landscapes from 2026 to 2033. Limitations include unforeseen macroeconomic shifts, localized regulatory policy alterations, and variable healthcare reimbursement policy reforms across developing sovereign states.
Recent Developments and Strategic Industry Moves
Recent milestones feature expedited FDA approvals for novel once-weekly formulations, strategic licensing agreements between major pharmaceutical houses, and capital investments in advanced prefilled injection pen manufacturing facilities to support accelerating global patient demand.