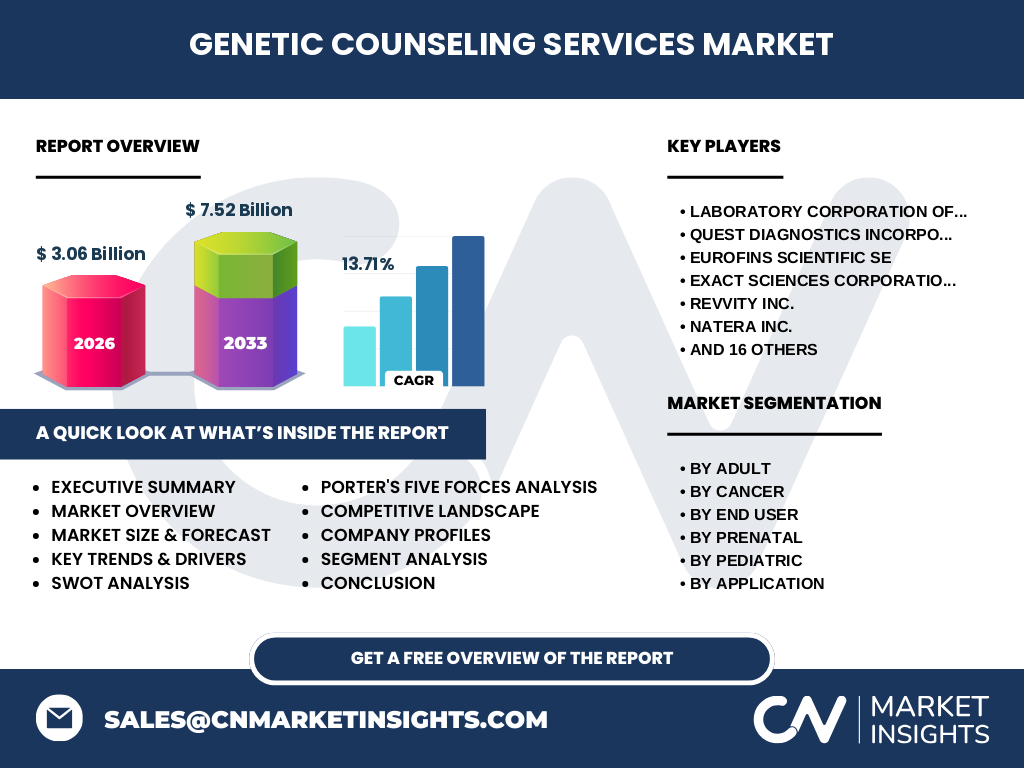
Market overview of the Genetic Counseling Services Market
Our analysis indicates that the Genetic Counseling Services Market is valued at 3.06 Billion in 2026. This sector evaluates hereditary risks, interprets genomic data, and guides clinical decision-making across oncology, prenatal care, and rare diseases, bridging complex sequencing technologies with patient understanding.
Key growth drivers and restraints shaping the industry
Growth is propelled by expanding multi-cancer panels and falling sequencing costs, whereas severe shortages of board-certified genetic counselors act as a critical bottleneck. Regulatory hurdles from agencies like the FDA constrain direct-to-consumer expansion, prioritizing clinical validation.
Emerging trends and growth patterns
The shift toward decentralized care has amplified tele-genetics adoption. InformedDNA and Genome Medical Inc. lead this digital transformation, integrating virtual counseling platforms directly into hospital electronic health records to streamline clinical workflows.
COVID-19 impact analysis and recovery trajectory
The pandemic initially depressed in-person consultations by over 40 percent. However, regulatory flexibilities for telehealth catalyzed a permanent operational pivot, accelerating the market past pre-pandemic growth trajectories toward its robust 2027-2033 outlook.
Competitive landscape and strategic market dynamics
Market consolidation is intensifying as diagnostics giants acquire specialized counseling networks. Laboratory Corporation of America Holdings and Quest Diagnostics Incorporated leverage vast logistics footprints to bundle genetic testing with proprietary counseling services.
Executive summary of the Genetic Counseling Services Market
The Genetic Counseling Services Market industry trends highlight rapid expansion driven by precision medicine integration. Strategic investments in telehealth infrastructure and algorithmic variant interpretation platforms are vital for capturing value across diverse patient cohorts.
Market forecast from 2027 to 2033
Based on our research, the market will surge from 3.06 Billion in 2026 to reach 7.52 Billion by 2033, expanding at a remarkable CAGR of 13.71%. This trajectory reflects mainstream clinical adoption of hereditary cancer panels and preventive pharmacogenomic profiling.
Segmentation analysis across clinical categories
The sector spans Adult, Cancer, Prenatal, Pediatric, and specialized Service Types. Hereditary Breast Cancer Counseling and Noninvasive Prenatal Testing Counseling drive high-volume throughput, while Nutrigenomic Counseling and Adoption Genetic Counseling represent emerging niche opportunities.
Regional market analysis and geographic distribution
North America dominates revenue generation due to established reimbursement codes and high genomic literacy. Meanwhile, Asia-Pacific exhibits the fastest adoption velocity, spurred by rising disposable incomes and expanding diagnostic laboratory infrastructure in urban healthcare hubs.
In-depth regional review of key markets
US and European markets benefit from structured payers and established clinical guidelines from bodies like the ACMG. Conversely, emerging markets encounter localized constraints such as limited insurance coverage for preventive genetics, necessitating direct-out-of-pocket payment models.
Company profiles and strategic positioning
Key innovators like Myriad Genetics Inc., Natera Inc., and Ambry Genetics Corporation differentiate through proprietary variant databases and scaled genetic laboratories. Meanwhile, 23andMe Holding Co. captures consumer segments through direct-to-consumer genetic counseling bridges.
Porter's Five Forces analysis of the industry
Supplier power remains moderate due to specialized clinician scarcity, while buyer power is low given the specialized, diagnostic nature of services. Threat of substitution is minimal, but competitive rivalry among established diagnostics firms is exceptionally intense.
SWOT analysis of the sector
Strengths include advanced genomic databases and rising precision medicine demand. Weaknesses involve counselor shortages and complex reimbursement landscapes. Opportunities lie in AI-driven variant interpretation, whereas regulatory compliance shifts represent primary threats.
Value chain analysis from raw materials to end-users
The value chain flows from sequencers and raw biochemical reagents to clinical laboratories like NeoGenomics Inc. and Guardant Health Inc., culminating in genetic counselors who translate complex genomic data for hospitals, clinics, and end-users.
Investment insights and high-potential areas
High-potential investments target AI-powered genomic data interpretation platforms and scalable telehealth infrastructure. Companies reducing administrative friction in variant curation offer superior risk-adjusted returns for venture capital and private equity investors.
Conclusion and key takeaways
The Genetic Counseling Services Market market size expansion to 7.52 Billion underscores its transition from adjunct specialty to core clinical care. Stakeholders must embrace telehealth and automation to overcome clinician shortages and capture emerging precision medicine demand.
Research methodology and triangulation of baseline estimates
Baseline estimates are triangulated by combining national health registry data, primary stakeholder interviews with clinical geneticists, and secondary macroeconomic indicators regarding healthcare expenditure, ensuring high-fidelity market sizing.
Scope of the report and coverage parameters
This report covers global clinical indications, delivery modes, and end-user facilities from 2026 to 2033. Excluded from this scope are unvalidated recreational genomics services lacking clinical utility frameworks or regulatory oversight.
Recent developments in the industry
Recent strategic moves feature Exact Sciences Corporation and GeneDx forging partnerships with digital health platforms to expand remote oncology counseling access, alongside venture funding rounds for boutique providers like Lilac Insights Private Limited.