What is the market overview of the Narrowbody Aircraft Market?
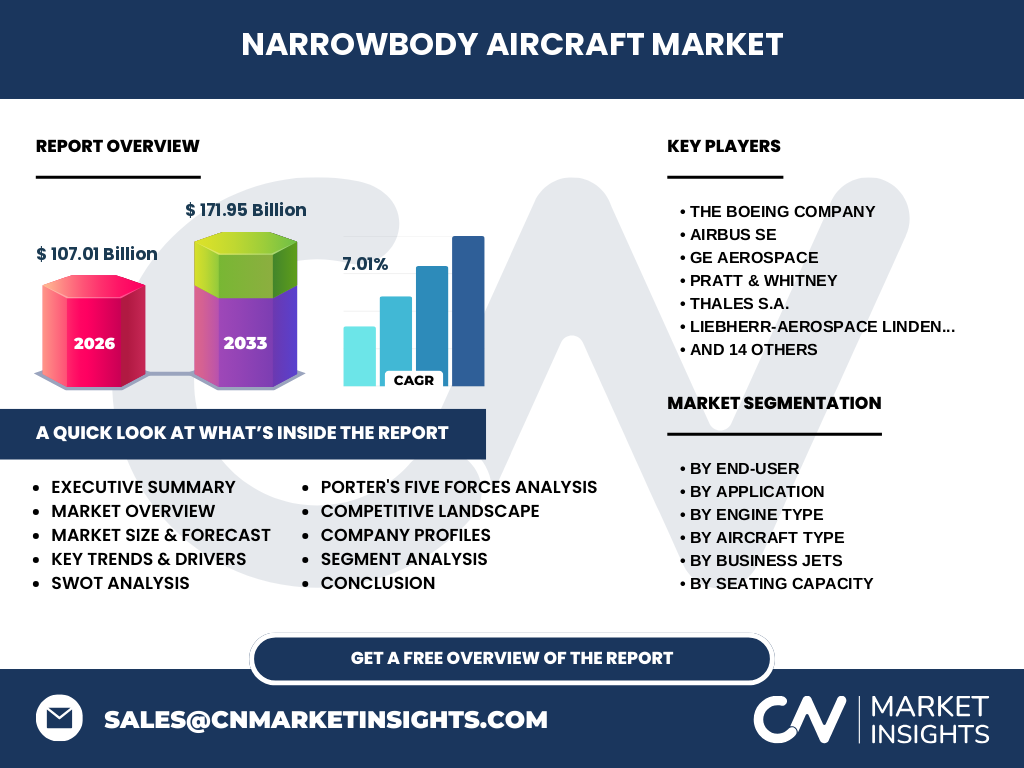
Our analysis indicates that the Narrowbody Aircraft Market is valued at 107.01 Billion in 2026, serving as the foundational backbone for global aviation logistics. This sector encompasses single-aisle commercial airliners, regional jets, and tactical military variants utilized extensively by airlines and leasing companies for short-to-medium-haul routes.
Key market drivers, restraints, challenges, and opportunities shaping the Narrowbody Aircraft Market
Growth is propelled by rising passenger traffic and fleet modernization demands, though constrained by severe supply chain bottlenecks for raw materials like aerospace-grade titanium and carbon composites. Regulatory pressures from the FAA and EASA demanding lower carbon emissions create lucrative opportunities for advanced turbofan propulsion innovators.
Emerging trends and growth patterns in Narrowbody Aircraft Market
The industry is witnessing an aggressive pivot toward ultra-fuel-efficient propulsion systems and lightweight composite airframes. Major manufacturers like Airbus SE and The Boeing Company are prioritizing digital twin manufacturing and sustainable aviation fuel compatibility to capture eco-conscious airline fleets.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically crippled commercial jet deliveries, forcing a sharp contraction in production lines across Spirit AeroSystems and Safran Aircraft Engines. However, the post-2022 recovery trajectory has been exceptionally robust, driven by pent-up domestic leisure travel and accelerated retirements of older, inefficient twin-aisle models.
Competitive benchmarking and strategic market concentration
The market exhibits a high degree of consolidation, characterized by a dominant duopoly between Airbus SE and The Boeing Company in commercial single-aisles, alongside aggressive challengers like Commercial Aircraft Corporation of China Ltd. Engine manufacturers such as GE Aerospace and Pratt & Whitney exert significant pricing power.
Executive summary of the Narrowbody Aircraft Market
Driven by robust post-pandemic travel demand, the Narrowbody Aircraft Market is projected to surge from 107.01 Billion in 2026 to 171.95 Billion by 2033, achieving a stellar 7.01% CAGR. Supply chain resilience and sustainable technology integration remain critical strategic imperatives for sustained profitability.
Market forecast from 2027 to 2033
Based on our econometric modeling, the sector will expand decisively, scaling up to 171.95 Billion by 2033 at a steady 7.01% CAGR. This expansion is underpinned by massive airline backlog orders requiring consistent fuselage and avionics deliveries from suppliers like Thales S.A. and Liebherr-Aerospace.
Segmentation analysis across end-users, applications, and aircraft types
The market segments by end-user into airlines, leasing companies, and military; by application into passenger transport, freight transport, and military operations; and by engine type into turbofan and turboprop. Aircraft types further divide into commercial aircraft, business jets, and military aircraft, with the single-aisle commercial category dominating volume.
Regional market analysis and geographic performance
Geographic performance highlights Asia-Pacific as the fastest-growing regional hub due to burgeoning middle-class populations and expanding low-cost carrier networks. North America maintains a mature yet highly lucrative replacement cycle, while European carriers face stringent environmental mandates overseen by the European Union Aviation Safety Agency.
In-depth regional review of high-growth territories
Asia-Pacific leads demand dynamics, supported by aggressive fleet expansions from carriers in China and India. Meanwhile, North American operations focus heavily on cabin retrofits and digital avionics upgrades supplied by firms like Collins Aerospace and Parker Hannifin to maximize operational efficiency on high-frequency domestic corridors.
Company profiles and strategic positioning of leading players
Industry titans like Airbus SE and The Boeing Company leverage massive global assembly footprints, while propulsion specialists such as MTU Aero Engines AG and Safran Aircraft Engines focus on next-generation open-rotor and geared turbofan technologies to secure long-term service agreements.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate-to-high due to specialized metallurgical requirements, whereas the threat of new entrants is exceptionally low given the insurmountable capital expenditure and stringent FAA certification hurdles. Rivalry among established primes is intense, focusing on delivery speed and fuel burn efficiency.
SWOT analysis of the Narrowbody Aircraft Market
Key strengths include unmatched operational flexibility and fuel economy for short-haul routes. Weaknesses involve complex, fragile supply chains. Opportunities lie in regional jet modernization programs by Embraer S.A. and Comac, while external threats stem from geopolitical trade frictions and volatile jet fuel prices.
Value chain analysis from raw materials to end-users
The value flow originates with raw material extraction—such as aluminum-lithium alloys and carbon fiber—processed by tier-one suppliers like GKN Aerospace and FACC AG into major sub-assemblies. These flow into original equipment manufacturers for final integration before delivery to commercial airlines and leasing firms.
Investment insights and high-potential growth pockets
Investors should target component manufacturers specializing in lightweight composite structures and electric taxiing systems. Companies partnering with sustainable aviation fuel initiatives and digital predictive maintenance platforms offer superior risk-adjusted returns throughout the forecast period.
Conclusion and core takeaways for stakeholders
The Narrowbody Aircraft Market presents robust expansion opportunities backed by a solid 7.01% CAGR. Stakeholders must proactively address supply chain vulnerabilities and invest heavily in eco-efficient propulsion technologies to capture long-term market share through 2033.
Research methodology and data triangulation techniques
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, primary stakeholder interviews with C-suite executives across tier-one suppliers, and secondary macroeconomic indicators from civil aviation authorities such as the ICAO and FAA to ensure absolute market accuracy.
Scope of the report and coverage parameters
This report covers global market sizing, revenue forecasts, and granular segment analysis spanning commercial, business, and military narrowbody categories from 2026 to 2033. Excluded from this scope are widebody aircraft fleets and purely rotary-wing military hardware, ensuring hyper-focused analytical depth.
Recent developments, partnerships, and strategic moves
Recent industry momentum is defined by strategic joint ventures in hybrid-electric propulsion, multi-billion-dollar single-aisle orders by major leasing entities, and aggressive factory automation investments by structural suppliers like Spirit AeroSystems and Hong Kong Aircraft Engineering Company Limited to alleviate production backlogs.