Market Overview of the HER2 Targeted Therapies Industry
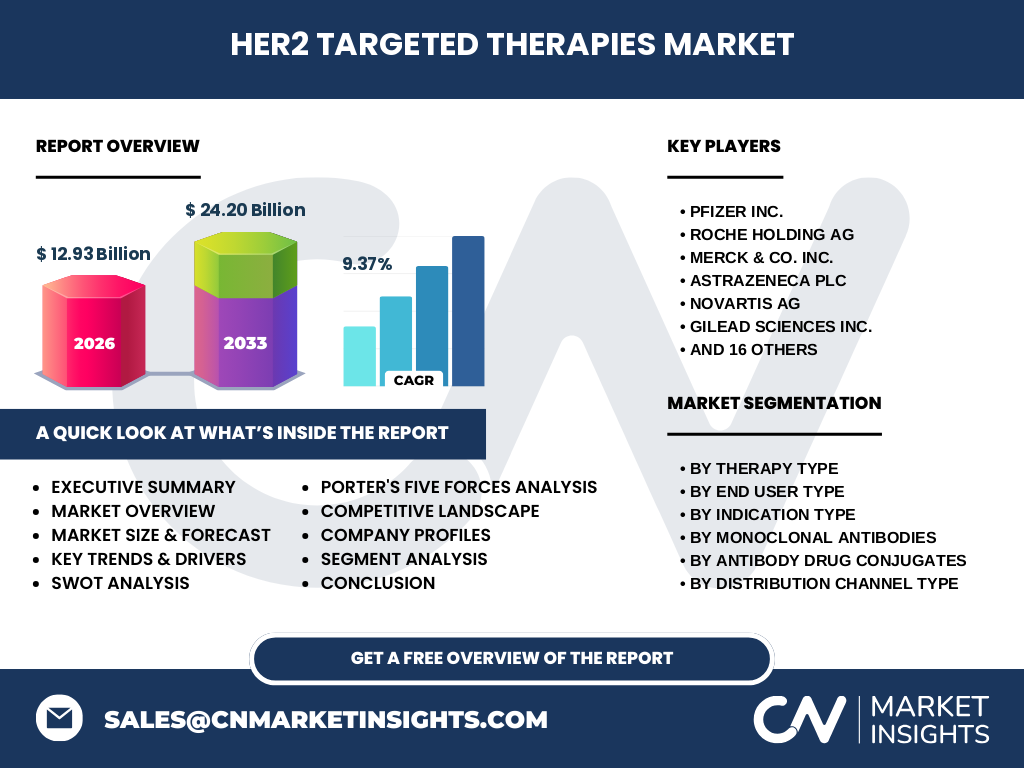
Our analysis indicates that the HER2 Targeted Therapies Market valuation stands at 12.93 Billion in 2026. This sector encompasses advanced oncological interventions designed for human epidermal growth factor receptor 2-positive cancers, including monoclonal antibodies, tyrosine kinase inhibitors, and antibody-drug conjugates, critical for modern precision oncology governed strictly by the FDA and EMA.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising breast and gastric cancer incidences alongside innovations in antibody-drug conjugates like Trastuzumab Deruxtecan. However, severe restraints involve high drug development costs, strict regulatory hurdles by bodies like the PMDA, and stringent cold-chain logistical requirements impacting distribution in remote areas.
Emerging Trends Shaping the HER2 Targeted Therapies Landscape
The landscape is pivoting toward next-generation antibody-drug conjugates and biosimilar monoclonal antibodies to reduce healthcare expenditures. Companies such as Celltrion Inc. and Biocon Biopharmaceuticals Pvt. Ltd. are driving adoption by lowering therapy costs, altering clinical practice guidelines globally.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic caused severe diagnostic delays and supply chain disruptions for critical raw materials. Recovery has been robust, driven by tele-oncology adoption and a swift resumption of clinical trials by frontrunners like Roche Holding AG and AstraZeneca PLC.
Competitive Benchmarking and Market Concentration
The industry exhibits high concentration, dominated by established pharmaceutical giants such as Pfizer Inc., Novartis AG, and Roche Holding AG. These players leverage extensive global distribution networks and aggressive R&D investments to maintain dominance against agile innovators like Zymeworks Inc.
Executive Summary: Key Findings for the HER2 Targeted Therapies Sector
The HER2 Targeted Therapies Market is poised for remarkable expansion, growing from 12.93 Billion in 2026 to 24.20 Billion by 2033 at a CAGR of 9.37%. Precision medicine advancements and expanding indications in colorectal cancer heavily anchor this trajectory.
Market Forecast Projections (2027 to 2033)
Based on our research, the market will scale from its 2026 baseline of 12.93 Billion to reach 24.20 Billion by 2033. This expansion reflects a steady 9.37% CAGR, heavily driven by increased uptake of tyrosine kinase inhibitors like Tucatinib and rising oncology clinic visits.
Segmentation Analysis Across Therapy, Indication, and End-User Types
Segmentation spans therapy types (Monoclonal Antibodies, Tyrosine Kinase Inhibitors, Antibody Drug Conjugates), indications (Breast, Gastric, Colorectal Cancer), routes of administration (Oral, Intravenous), and end-users including hospitals and cancer specialty centers, each addressing specific patient needs.
Geographic Distribution and Regional Performance
North America leads regional adoption due to established healthcare infrastructure and favorable reimbursement policies by CMS. Meanwhile, Asia-Pacific represents the fastest-growing frontier, propelled by rising healthcare investments in China and Japan, involving local innovators like Jiangsu Hengrui Pharmaceuticals.
In-Depth Regional Review of High-Growth Markets
North America and Europe currently capture the largest revenue shares, supported by rapid uptake of advanced therapies like Margetuximab. Conversely, the Asia-Pacific region displays exceptional growth momentum, fueled by the commercial expansion of regional biosimilars and domestic oncology centers.
Strategic Positioning of Leading Industry Companies
Industry leaders like AstraZeneca PLC and Daiichi Sankyo Company Limited focus on proprietary antibody-drug conjugates. Meanwhile, firms like MacroGenics Inc. and Puma Biotechnology carve niches through targeted tyrosine kinase inhibitors and specialized oncology portfolios.
Porter's Five Forces Analysis of Competitive Pressures
Rivalry is intense among major incumbents, while the threat of new entrants remains moderate due to steep R&D barriers and stringent FDA approval processes. Bargaining power of buyers is offset by specialized oncology demand, whereas substitute threat is low.
SWOT Analysis of the HER2 Targeted Therapies Market
Strengths include robust clinical efficacy and specialized pipelines. Weaknesses involve high treatment costs. Opportunities lie in emerging colorectal cancer indications, while threats encompass aggressive biosimilar erosion and complex international patent litigation landscapes.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with upstream chemical and biological raw material suppliers, progressing to biopharmaceutical manufacturing plants utilizing complex bioreactors. Products move through cold-chain logistics to hospital pharmacies, retail outlets, and online pharmacies for end-user administration.
Investment Insights and High-Potential Growth Areas
High-potential opportunities center on next-generation antibody-drug conjugates and oral routes of administration that enhance patient compliance. Investors should target emerging biotech innovators in Asia-Pacific with robust clinical trial pipelines in gastric cancer indications.
Conclusion and Strategic Takeaways for Stakeholders
The HER2 Targeted Therapies Market offers lucrative prospects, supported by a forecasted expansion to 24.20 Billion by 2033. Strategic partnerships, decentralized oncology care, and portfolio diversification into biosimilars remain critical for sustained competitive advantage.
Research Methodology and Baseline Triangulation
Our findings are synthesized by triangulating primary stakeholder interviews with key opinion leaders, secondary macroeconomic indicators from global health organizations, regulatory filings from the FDA and EMA, and proprietary trade registry data.
Scope of the Report and Coverage Parameters
This report covers global market dynamics from 2026 to 2033, analyzing specific therapy types, routes of administration, and distribution channels. Limitations include unpredictable geopolitical shifts impacting global pharmaceutical supply chains and evolving international healthcare reimbursement policies.
Recent Developments, Strategic Partnerships, and Product Launches
Recent milestones feature strategic co-development agreements for novel antibody-drug conjugates by pioneers like Zymeworks Inc. and clinical trial expansions by Daiichi Sankyo Company Limited, reinforcing active pipeline investments across global oncology markets.