Market overview and structural significance within heavy engineering
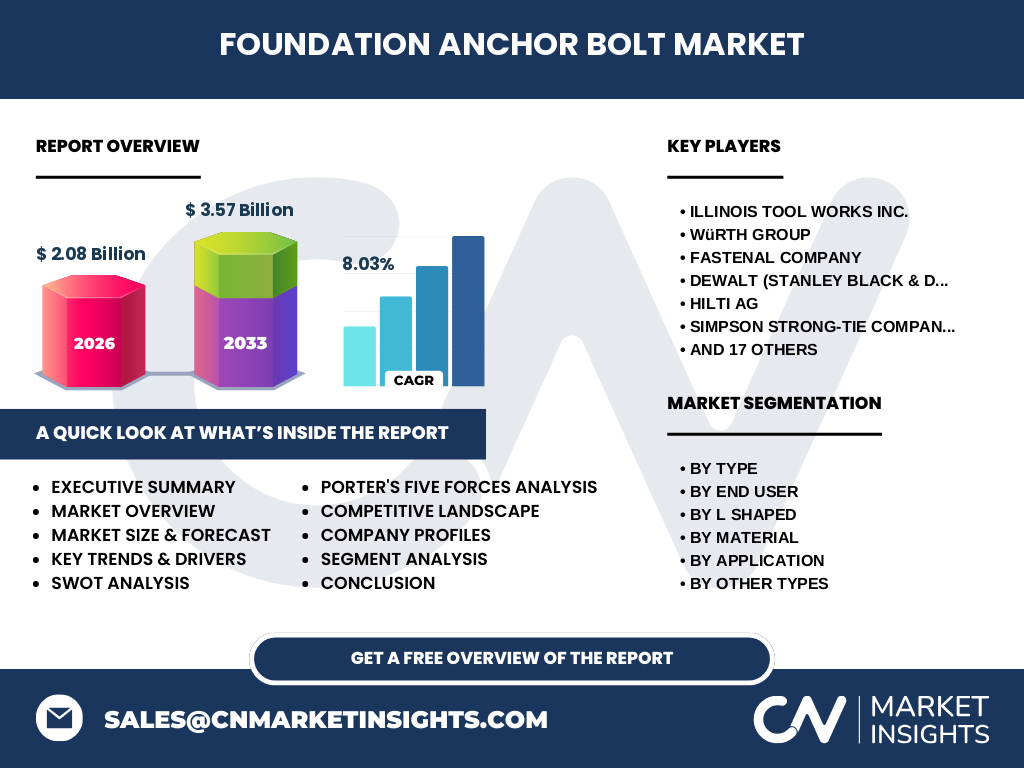
Our analysis indicates that the Foundation Anchor Bolt Market plays a critical role in structural engineering by securing heavy machinery and structural steel to concrete foundations. Valued at $2.08 Billion in 2026, this sector underpins safety and load-bearing compliance across global infrastructure projects, navigating strict ASTM and ISO standards for carbon, alloy, and stainless steel raw materials.
What primary catalysts and barriers govern expansion in the Foundation Anchor Bolt Market?
The market is driven by rapid urbanization and industrial capital expenditures, though restrained by volatile raw material costs for carbon and alloy steel. Opportunities abound in renewable energy installations, while logistical hurdles through major ports like Shanghai and Rotterdam pose supply chain bottlenecks for heavy-duty forged configurations.
Emerging growth patterns and technological shifts
The data suggests a strong pivot toward corrosion-resistant stainless steel and hot-forged L-shaped variants designed for extreme seismic zones. Engineering firms increasingly demand custom-designed anchor bolts and full-length swedge bolts to maximize pull-out resistance in high-stress infrastructure and offshore power applications.
COVID-19 impact analysis and post-pandemic recovery trajectories
Pandemic-induced supply chain disruptions and construction freezes temporarily depressed demand across commercial and residential sectors. However, government stimulus packages targeting green energy and transportation infrastructure catalyzed a robust recovery, accelerating procurement via digital distribution channels and direct supplier partnerships.
Competitive Benchmarking and Market Concentration
The competitive landscape is defined by a mix of multinational giants and specialized forges. Market leaders like Illinois Tool Works Inc., Hilti AG, and Fastenal Company leverage extensive distribution networks, while specialists like Portland Bolt dominate custom manufacturing segments through rapid turnaround of heavy-duty headed bolts.
Executive summary of the Foundation Anchor Bolt Market
Our research projects the Foundation Anchor Bolt Market to expand from $2.08 Billion in 2026 to reach $3.57 Billion by 2033, registering a robust 8.03% CAGR. This growth is heavily anchored by infrastructure investments and surging industrial machinery deployments across developing economies.
Market forecast trajectory from 2027 to 2033
Driven by a projected 8.03% CAGR, the market will scale from its 2026 baseline to $3.57 Billion by 2033. This expansion reflects sustained long-term capital outlays in power and energy, particularly wind turbine foundations requiring specialized double end rods with plates.
Segmentation analysis across product types and end users
The market segments by Type (L Shaped, Double End Rods With Plate, Headed Bolts, Swedge Bolts), End User (Residential, Commercial, Industrial, Infrastructure), Material (Carbon Steel, Stainless Steel, Alloy Steel), and Distribution Channel (Direct Sales, Distributors, Online Retail), enabling targeted deployment for construction and power sectors.
Geographic distribution and regional performance dynamics
Regional performance varies based on localized regulatory frameworks and construction intensity. Asia-Pacific leads consumption due to aggressive infrastructure buildouts, while North America and Europe demand high-specification stainless steel and hot-forged fasteners compliant with stringent local building codes and seismic mandates.
In-depth regional review of key consuming geographies
North American growth is anchored by commercial modernization and renewable energy investments, utilizing massive distribution networks managed by firms like Fastenal and Simpson Strong-Tie. Meanwhile, Asia-Pacific remains the high-volume manufacturing epicenter, driven by rapid industrialization and urban transit projects.
Strategic positioning of leading companies in the sector
Industry leaders maintain distinct strategic moats: Hilti AG focuses on proprietary chemical and mechanical anchoring systems, Würth Group dominates multi-channel distribution, and specialized manufacturers like Dyson Corporation engineer massive custom fasteners for heavy industrial and bridge construction applications.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers is moderate to high due to standardized product commoditization, though mitigated by strict safety certifications. Threat of substitutes remains low because structural engineering codes mandate certified steel fasteners like swedge and L-shaped bolts for primary load paths.
SWOT evaluation of the Foundation Anchor Bolt Market ecosystem
Strengths include mission-critical utility in all heavy construction; weaknesses involve vulnerability to raw steel price swings. Opportunities lie in offshore wind energy expansion, while threats include counterfeit low-grade fasteners compromising structural integrity and triggering regulatory penalties.
Value chain analysis from raw materials to end-user deployment
The value chain starts with raw steel mills supplying carbon, alloy, and stainless grades, progressing through specialized hot-forging, threading, and swedging facilities. Finished goods move through direct sales, industrial distributors like Fastenal, and online platforms to end-users in construction and power.
Strategic investment insights and high-potential areas
Investors should target manufacturers specializing in high-strength alloy and corrosion-resistant stainless steel variants tailored for renewable energy and offshore infrastructure. Companies investing in automated forging and digital inventory integration with distributors will capture outsized market share.
Conclusion and key structural takeaways
The Foundation Anchor Bolt Market represents a vital, high-growth component of the global construction economy. Reaching $3.57 Billion by 2033 at an 8.03% CAGR, the sector rewards technological adaptation, stringent quality compliance, and diversified supply chain strategies.
Research methodology for baseline estimates and validation
Our baseline estimates are triangulated by combining international trade registry data, primary stakeholder interviews with engineering executives, and secondary macroeconomic indicators such as national construction spending indices, ensuring high-fidelity market sizing and growth projections.
Scope of the report and analytical boundaries
This report covers global market dynamics for foundation anchor bolts from 2026 to 2033, analyzing specific segments across materials, product types, and end-user verticals. Excluded from this scope are generic non-structural fasteners and temporary construction hardware not engineered for permanent foundations.
Recent developments, corporate partnerships, and strategic moves
Recent industry activity highlights major players expanding production capacities for heavy-duty headed and swedge bolts to meet surging renewable energy demands. Strategic acquisitions among top-tier distributors like Würth and Fastenal aim to secure localized inventory and streamline delivery to mega-infrastructure projects.