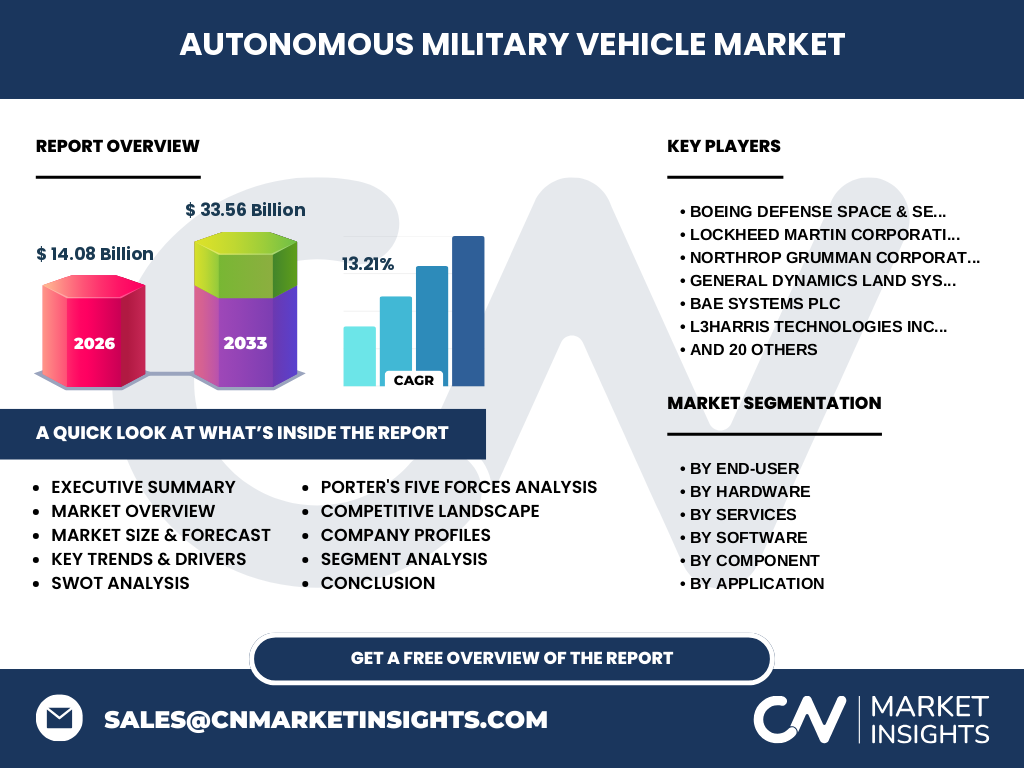
Market overview of the Autonomous Military Vehicle Market
Our analysis indicates that the Autonomous Military Vehicle Market represents a critical technological frontier, valued at $14.08 Billion in 2026. This sector encompasses unmanned aerial, ground, surface, and underwater platforms designed to minimize direct human exposure in hostile zones while executing complex defense mandates.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating geopolitical tensions and the imperative for force multiplication. However, stringent military certification hurdles, complex software accreditation, and vulnerability to advanced electronic warfare and cyber-attacks act as notable restraints for defense contractors operating in this space.
Emerging trends and growth patterns in the Autonomous Military Vehicle Market
The sector is witnessing a rapid shift toward artificial intelligence at the tactical edge, enabling platforms to operate effectively in GPS-denied environments. Companies like Anduril Industries and AeroVironment Inc. are leading this wave by integrating advanced neural networks for autonomous threat detection.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain bottlenecks for rare earth elements and specialized semiconductor components, temporarily delaying prototype field testing. Nevertheless, our research confirms a robust post-pandemic recovery, as defense ministries accelerated unmanned procurement to bolster resilience against future biological and conventional disruptions.
Competitive Benchmarking
The market features intense competition among prime contractors like Lockheed Martin Corporation, BAE Systems plc, and General Dynamics Land Systems. Market concentration is moderate to high, with major players aggressively acquiring specialized autonomy firms like Kodiak Robotics Inc. to secure proprietary machine learning algorithms.
Executive Summary of Autonomous Military Vehicle Market insights
Driven by a robust CAGR of 13.21%, the market is projected to reach $33.56 Billion by 2033 from its 2026 baseline. This massive expansion underscores an irreversible doctrinal shift toward unmanned systems across global armed forces, prioritizing cognitive autonomy and survivability.
Long-Term Market Forecast (2027 to 2033)
From 2027 to 2033, the market will experience accelerated deployment, expanding from its 2026 valuation of $14.08 Billion to $33.56 Billion by the end of the forecast period. This growth is underpinned by sustained defense budget allocations for robotic combat vehicles and loyal wingman drone programs.
Segmentation Analysis of platforms, hardware, software, and services
The market breaks down by platform into UAVs, UGVs, UUVs, and USVs, while operational capabilities span hardware, software, and specialized maintenance services. Autonomy and navigation software together with AI-driven processing units represent the highest-margin segments within this classification structure.
Geographic Distribution and Regional Performance
North America dominates the landscape due to massive Department of Defense modernization initiatives, followed closely by the Asia-Pacific region, where territorial disputes fuel rapid procurement of maritime and aerial autonomous assets. Europe represents a fast-growing market driven by NATO interoperability standards.
In-Depth Regional Review
In the Asia-Pacific, nations like South Korea—bolstered by firms such as Hyundai Rotem Company and Hanwha Aerospace—are pioneering ground robotics to counter demographic shifts and border challenges. Meanwhile, European markets focus heavily on counter-UAS and subterranean UUV technologies for Baltic Sea security.
Company Profiles and Strategic Positioning
Industry leaders leverage distinct competitive moats: KNDS N.V. and Rheinmetall AG focus on heavy armored autonomy, while agile innovators like Forterra Inc. and Teledyne FLIR LLC specialize in perception software and thermal imaging payloads that enhance operational efficacy.
Porter's Five Forces analysis of the defense robotics sector
Supplier power remains moderate, constrained by specialized microchip and sensor requirements. Conversely, buyer power is concentrated among sovereign defense agencies, while threat of substitution is low given the proprietary nature of military-grade cybersecurity and encryption software.
SWOT Analysis of the Autonomous Military Vehicle Market
Key strengths include superior operational endurance and precision ISR capabilities. Weaknesses involve high lifecycle maintenance costs. Opportunities lie in dual-use commercial logistics adaptations, while threats emanate from asymmetric electronic warfare and unregulated autonomous lethality debates at the United Nations.
Value Chain Analysis
The value chain flows from raw material extraction of titanium and rare earths, through component fabrication by firms like Kongsberg Gruppen ASA and ASELSAN A.Ş., to system integration by primes, culminating in deployment and operational support services for end-user armies, navies, and air forces.
Investment Insights and High-Potential Areas
Investors should target developers of resilient autonomy and navigation software capable of functioning without satellite connectivity. Companies providing robust simulation and training services also present high upside as military organizations scale up virtualized operator readiness programs.
Conclusion and Key Takeaways
The Autonomous Military Vehicle Market industry trends point toward undisputed dominance of unmanned systems in future warfare. With a projected valuation of $33.56 Billion by 2033, early investments in edge AI and secure data links will dictate long-term market leadership.
Research Methodology
Our baseline estimates are rigorously triangulated by combining defense trade registry data, primary stakeholder interviews with procurement officers from organizations like the U.S. DoD and European Defence Agency, and secondary macroeconomic indicators regarding national defense spending allocations.
Scope of the Report
This report covers the global Autonomous Military Vehicle Market across four main platform types and six distinct application verticals, analyzing hardware, software, and service segments from 2026 to 2033, while explicitly excluding purely commercial autonomous automotive logistics.
Recent Developments and Strategic Moves
Recent milestones include major contract awards for robotic combat vehicle prototypes involving Oshkosh Corporation and joint-venture partnerships between traditional primes and software specialists like Kodiak Robotics Inc. to upgrade legacy armored fleets with advanced driverless capabilities.