Market overview of the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market
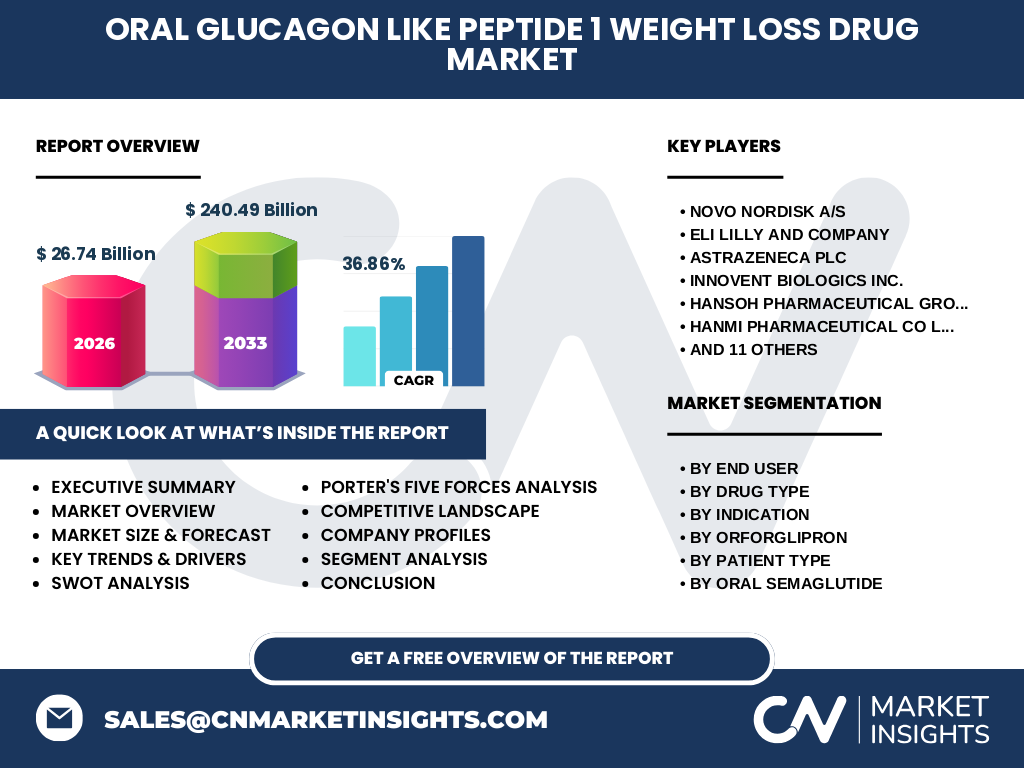
Our proprietary analysis defines the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market market size at $26.74 Billion for 2026. This sector encompasses small molecule and peptide-based oral therapies designed to replace burdensome subcutaneous injections. Industry significance centers on scaling patient compliance for chronic weight management and type 2 diabetes indications globally.
Structural Growth Drivers and Restraints
The Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market industry trends are heavily propelled by patient preference for needle-free administration. However, stringent manufacturing hurdles regarding oral peptide bioavailability and supply chain constraints for raw chemical synthesis act as notable market restraints.
Emerging Innovation Patterns and Technological Shifts
The shift toward non-peptide oral therapies and combination metabolic treatments is redefining the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market analysis. Innovators are prioritizing once-daily oral formulations to enhance pharmacokinetic profiles and expand accessibility across retail pharmacies.
COVID-19 Impact and Recovery Trajectory
Pandemic disruptions initially delayed clinical trials for oral metabolic treatments, yet they ultimately accelerated digital healthcare adoption. The post-COVID recovery trajectory for the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market market size showcases robust rebound effects, driven by heightened global focus on obesity comorbidities.
Competitive Benchmarking and Market Concentration
The competitive landscape features fierce rivalry among pioneers like Novo Nordisk A/S and Eli Lilly and Company, alongside agile challengers such as Viking Therapeutics Inc. and Structure Therapeutics Inc. Market concentration remains moderately high, favoring firms with established cold-chain distribution networks.
Executive Summary of Core Research Findings
Our research indicates explosive expansion, projecting the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market to surge from $26.74 Billion in 2026 to $240.49 Billion by 2033 at a staggering CAGR of 36.86%. Strategic investments in specialty metabolic centers will dictate market leadership.
Long-Term Market Forecast through 2033
Driven by rising obesity prevalence and commercialization of next-generation oral therapeutics, the forecast projects unprecedented valuation trajectories. The Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market industry trends confirm that 2027 to 2033 will represent a golden era of commercialization.
Comprehensive Segmentation Breakdown
Our Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market analysis segments the industry meticulously:
- By End User: Hospitals, Obesity Clinics, Homecare Or Self Administered Users, Specialty Metabolic Centers.
- By Drug Type: Orforglipron, Oral Semaglutide, Next Generation Oral Glucagon Like Peptide One.
- By Indication: Obesity Management, Overweight With Comorbidities, Type Two Diabetes With Obesity, Cardiovascular Risk Reduction, Weight Maintenance.
- By Patient Type: Non Diabetic Patients, Diabetic Patients, Adult Population, Adolescent Population, Elderly Population.
- By Distribution Channel: Retail Pharmacy, Direct To Consumer, Hospital Pharmacy.
Geographic Distribution and Regional Performance
North America dominates the adoption curve due to high obesity rates and favorable reimbursement policies. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, supported by aggressive clinical trial expansions from regional innovators like Jiangsu Hengrui Pharmaceuticals Co Ltd. and Hansoh Pharmaceutical Group.
In-Depth Regional Review and Localized Constraints
Regional performance varies based on regulatory approvals by agencies such as the FDA and EMA. Pricing pressures in European markets contrast sharply with high out-of-pocket spending in emerging Asian economies, shaping customized commercial strategies for market players.
Strategic Company Profiles and Market Positioning
Industry titans like AstraZeneca PLC, Amgen, and Innovent Biologics Inc. are leveraging strategic acquisitions and licensing agreements. Emerging players like Sciwind Biosciences Co. Ltd. and Eccogene Inc. focus on differentiated dual and triple agonist oral pipelines.
Porter's Five Forces Competitive Assessment
Bargaining power of buyers is moderate due to strict insurance formularies, while threat of new entrants is mitigated by high R&D costs and complex peptide synthesis. Rivalry among established pharmaceutical giants remains intensely high within the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market.
SWOT Analysis of the Oral Therapeutics Sector
Strengths include high patient compliance and robust clinical efficacy. Weaknesses involve complex manufacturing chemistry. Opportunities lie in pediatric and adolescent markets, while threats include generic patent challenges and potential gastrointestinal side-effect profiles.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with specialty chemical synthesis of small molecules and peptide precursors. It flows through advanced formulation facilities, passes via major logistics hubs to hospital and retail pharmacies, and ultimately reaches self-administered homecare users.
Strategic Investment Insights and High-Potential Areas
Investors should target developers of extended-release oral therapies and precision metabolic platforms. Companies partnering with contract development and manufacturing organizations (CDMOs) to solve scale-up bottlenecks present exceptional risk-adjusted return opportunities.
Conclusion and Definitive Takeaways
Reaching $240.49 Billion by 2033 at a 36.86% CAGR, the Oral Glucagon-Like Peptide (GLP)-1 Weight Loss Drug Market represents one of the most lucrative frontiers in modern pharmacotherapy. Strategic alignment with oral delivery innovation is non-negotiable for future market share.
Methodological Framework and Triangulation Process
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, pharmaceutical trade registry data, and primary stakeholder interviews with key opinion leaders, endocrinologists, and supply chain executives across global markets.
Scope of the Research Report and Analytical Parameters
This report covers global revenue projections from 2027 to 2033, historical data for 2026 at $26.74 Billion, and granular segment analysis. Limitations include unforeseen macroeconomic shifts, regulatory delays, and evolving healthcare policy reforms across target regions.
Recent Industry Developments and Strategic Moves
Recent milestones include active clinical trial readouts from Viking Therapeutics Inc. and Structure Therapeutics Inc., alongside co-development partnerships by Kailera Therapeutics Inc. and D And D Pharmatech Inc., significantly accelerating the delivery of next-generation oral metabolic therapies.