Market overview and structural scope of the Radiofrequency (RF) Anti-Aging Instrument Market
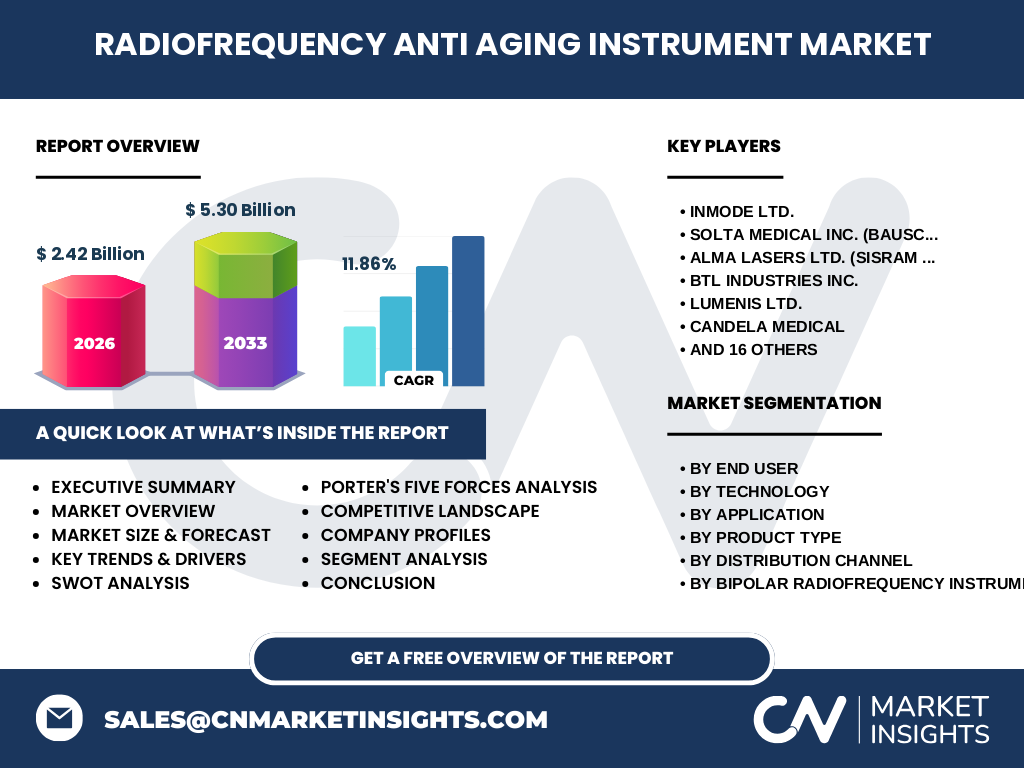
Our analysis indicates that the Radiofrequency (RF) Anti-Aging Instrument Market reached a valuation of $2.42 Billion by 2026. This sector encompasses professional and home-use energy-based devices utilizing thermal electromagnetic radiation to induce dermal neocollagenesis. Industry significance stems from shifting consumer demographics favoring non-invasive aesthetic procedures governed by strict medical device clearances from agencies such as the US FDA and European CE MDR.
What core factors represent structural growth drivers, restraints, and opportunities in the industry?
The market is propelled by a rising aging demographic seeking non-surgical dermatological solutions. Primary restraints involve stringent regulatory compliance hurdles and high initial device acquisition costs for independent practices. However, lucrative opportunities emerge within portable home-care configurations and advanced multi-technology platform integrations engineered by key innovators.
Emerging tech trends and growth patterns shaping the Radiofrequency (RF) Anti-Aging Instrument Market
Based on our research, the industry is witnessing an accelerated shift toward fractional and microneedling delivery mechanisms that maximize dermal heating while minimizing epidermal downtime. Technological convergence pairing bipolar and monopolar frequencies into single chassis platforms represents a major inflection point, driving higher adoption rates across urban dermatology clinics.
How did the COVID-19 pandemic disrupt operations and shape the recovery trajectory?
The pandemic caused severe supply chain bottlenecks for electronic components and forced temporary elective clinic closures globally. Nevertheless, our data suggests a robust post-pandemic rebound fueled by the 'Zoom effect'—an unprecedented surge in virtual meeting engagement that heightened consumer focus on facial aesthetics and accelerated home-care device utilization.
Competitive benchmarking and strategic dynamics among industry leaders
The competitive landscape features a balanced mix of consolidated med-tech enterprises and agile aesthetic developers. Companies like InMode Ltd., Solta Medical Inc. (Bausch Health), and Alma Lasers Ltd. (Sisram Medical Ltd) maintain strong market concentration via aggressive intellectual property portfolios, localized clinical training programs, and comprehensive consumable revenue models.
Executive summary of key findings in the Radiofrequency (RF) Anti-Aging Instrument Market
Our comprehensive evaluation confirms that the market is primed for exceptional expansion, driven by robust clinical validation and broadening consumer acceptance. With a projected market size scaling to $5.30 Billion by 2033, stakeholders must align capital allocation with high-margin segments like fractional systems and direct-to-consumer distribution models.
Long-term market forecast and trajectory from 2027 to 2033
The data demonstrates sustained compounding momentum, forecasting the market to surge from its 2026 baseline to reach $5.30 Billion by 2033. This trajectory represents a robust CAGR of 11.86%, underpinned by expanding disposable incomes in developing economies and continuous technological refinements in epidermal cooling safeguards.
Detailed segmentation analysis across applications, technologies, and end users
Segmentation is categorized by end-user (Dermatology Clinics, Medical Spas, Beauty Centers, Hospitals, Home Care Settings), technology (Invasive, Non-Invasive, Minimally Invasive), application (Skin Tightening, Wrinkle Reduction, Facial Rejuvenation, Body Contouring, Cellulite Reduction), and product type (Monopolar, Bipolar, Multipolar, Fractional, RF Microneedling). Non-invasive applications and dermatology clinics currently command the largest revenue shares.
Geographic distribution and regional performance in the global landscape
Regional performance highlights North America as the dominant revenue contributor, sustained by high consumer spending on aesthetic procedures and established reimbursement frameworks. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, propelled by surging disposable incomes and the rising prominence of domestic aesthetic manufacturing hubs in South Korea and China.
In-depth regional review of regulatory compliance and consumer adoption trends
Regulatory stringency heavily dictates regional go-to-market strategies. While the US FDA mandates rigorous 510(k) clearances for monopolar and fractional devices, European markets operate under stringent CE-MDR directives. Consumer adoption in APAC increasingly favors advanced microneedling modalities, pushing regional distributors to secure rapid local regulatory approvals.
Strategic positioning of leading companies in the sector
Industry leaders deploy distinct positioning strategies to defend market share. Established players like BTL Industries Inc. and Lumenis Ltd. focus on high-powered clinical devices for hospitals and large clinics, while consumer-facing innovators such as NuFace (Carol Cole Co.) and CurrentBody Skin Limited capture high-margin retail segments through targeted digital marketing.
Porter's Five Forces analysis of competitive intensity
Our analysis indicates moderate-to-high rivalry driven by frequent product launches and proprietary patent litigation. Supplier power remains moderate regarding specialized medical-grade gold and titanium micro-needles, whereas buyer power is elevated due to the abundance of alternative non-surgical anti-aging modalities available to aesthetic practitioners.
SWOT evaluation of internal capabilities and external market dynamics
Key strengths include high technological efficacy and strong recurring consumable sales. Weaknesses involve prohibitive upfront capital expenditures for smaller clinics. Opportunities lie in emerging male grooming markets, while threats stem from unverified counterfeit devices circulating through unregulated online retail channels.
Value chain analysis mapping industry structure from raw materials to end-users
The value chain originates with raw material procurement involving specialty silicon wafers, titanium alloys, and medical-grade polymers. Component manufacturers supply sub-assemblies to Tier-1 OEMs like Cutera Inc. and Candela Medical, who distribute via specialized medical aesthetic stores, direct clinic sales, and online retail platforms to end-users.
Strategic investment insights and high-potential areas for capital deployment
Investors should direct capital toward companies specializing in adjustable-depth microneedling systems and home-care anti-aging instruments. Strategic partnerships with regional medical distributors in Latin America and Southeast Asia offer high-yield expansion vectors for mid-tier manufacturers seeking untapped geographic corridors.
Conclusion and primary takeaways for industry stakeholders
The Radiofrequency (RF) Anti-Aging Instrument Market offers exceptional growth visibility anchored by an 11.86% CAGR through 2033. Success requires balancing clinical efficacy in professional dermatology settings with intuitive ergonomic designs for burgeoning home-care distribution channels.
Rigorous research methodology combining trade registry data and primary interviews
Our baseline estimates are triangulated using a rigorous mixed-methods approach. This combines import-export customs data from major manufacturing ports, primary stakeholder interviews with key opinion leaders in dermatology, and secondary macroeconomic indicators tracking global aesthetic clinic expansion rates.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing and forecasts from 2027 to 2033, analyzing five major product categories, five application types, and five distinct end-user segments. Limitations include restricted transparency on private-label manufacturing revenue in emerging economies and unmonitored gray-market device distribution.
Recent developments, corporate announcements, and strategic alliances
Recent market activity is characterized by aggressive M&A strategies and strategic cross-border partnerships. Firms like Classys Inc. and Jeisys Medical Inc. have expanded their global footprint via localized distribution agreements, while innovators such as EndyMed Medical Ltd. rolled out next-generation multi-source phase-controlled RF arrays to enhance procedural safety.