What is the scope and industry significance within the Sewing Thread Market?
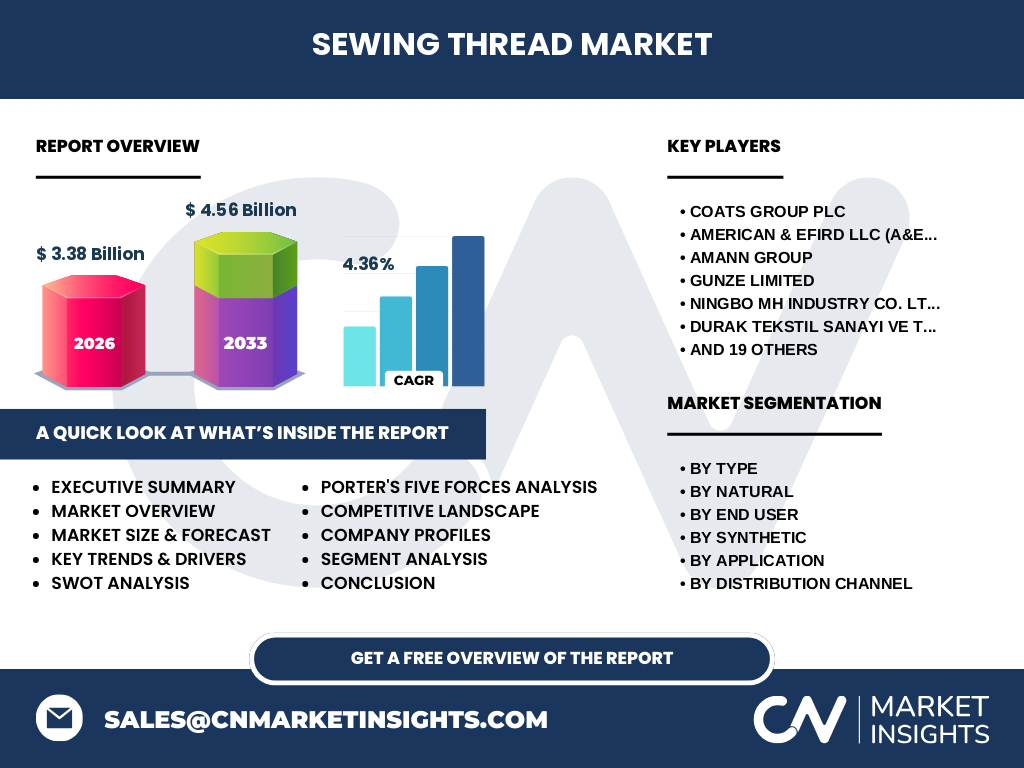
The Sewing Thread Market is valued at 3.38 Billion in 2026, serving as the foundational binding agent for global textile assembly. Our analysis indicates that advanced engineered filaments and traditional fibers dictate the structural integrity of apparel, footwear, and home furnishings across complex supply chains.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising automation in garment manufacturing and stringent ISO durability requirements. Conversely, volatility in petrochemical feedstocks for synthetic variants like polyester and nylon creates margin pressures. Logistical hurdles in primary sourcing hubs further challenge uninterrupted supply continuity for industrial users worldwide.
Emerging Trends in the Sewing Thread Market
The industry is pivoting aggressively toward circularity, with eco-friendly alternatives gaining traction. Biodegradable spun yarns and recycled PET filaments are replacing conventional petroleum-based products. This shift favors firms investing in sustainable chemistry to satisfy tightening environmental compliance mandates from major retail brands.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted supply chains and retail demand, causing steep contractions in garment manufacturing. Recovery has been driven by pent-up consumer demand and aggressive digital transformation in B2B distribution channels. Supply chain resilience has now become a core strategic focus for top-tier industry participants.
Competitive Landscape and Strategic Dynamics
The market features high consolidation among multinational leaders such as Coats Group plc and American & Efird LLC (A&E), alongside regional specialists like AMANN Group and Durak Tekstil. These firms leverage proprietary coating technologies and global distribution networks to maintain pricing power and outpace smaller independent thread spinners.
Executive Summary of the Sewing Thread Market
Our comprehensive research projects the Sewing Thread Market to expand from 3.38 Billion in 2026 to 4.56 Billion by 2033, registering a robust CAGR of 4.36%. Strategic investments in sustainable polymers and automated industrial sewing solutions remain vital for capturing future market share.
Market Forecast from 2027 to 2033
Driven by industrialization in emerging economies and steady demand for technical textiles, the sector will achieve a steady 4.36% CAGR, culminating in a market valuation of 4.56 Billion by 2033. Expanded manufacturing capacities in South Asia and Latin America will anchor this upward trajectory.
Segmentation Analysis: Types and Applications
The market splits by type into Synthetic (polyester, nylon, rayon, acrylic, polypropylene, elastic, blended) and Natural (cotton, silk, wool, linen, hemp, bamboo). End users span garment manufacturers, footwear producers, home textile makers, and industrial users, with applications ranging from apparel and bedding to heavy-duty technical footwear.
Regional Market Analysis and Geographic Distribution
Geographically, Asia-Pacific dominates due to extensive textile manufacturing clusters in China, India, and Bangladesh. North America and Europe follow, prioritizing high-performance technical threads for automotive and specialized protective wear. Regulatory standards in Western markets strongly dictate the adoption of flame-retardant and eco-certified thread solutions.
In-Depth Regional Review of Production Hubs
In South Asia, firms like Vardhman Yarns & Threads capitalize on abundant raw cotton and competitive labor costs. Meanwhile, European markets focus on specialized applications, where innovators like Madeira and AURIFIL S.r.l. command high-margin segments through precision embroidery and premium natural fiber offerings.
Company Profiles and Market Positioning
Industry giants like Coats Group plc and A&E maintain global footprints through localized manufacturing and rapid fulfillment. Specialized players such as Sarla Performance Fibers and Gunze Limited carve out niches in high-tenacity industrial yarns and advanced functional filaments tailored for demanding engineering specifications.
Porter's Five Forces Analysis
Competitive rivalry is intense among established multinational thread manufacturers. Supplier power remains moderate, tightly linked to raw material fluctuations in crude oil and raw cotton. Threat of substitution is low for high-performance applications, though competitive pricing pressure from unbranded local spinners challenges mid-tier operators.
SWOT Analysis of the Sewing Thread Industry
Strengths lie in established global supply networks and advanced tensile strength technologies. Weaknesses include vulnerability to raw material cost swings. Opportunities abound in sustainable bamboo and hemp threads, while threats stem from geopolitical trade tensions affecting cross-border textile machinery and filament exports.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with petrochemical refiners and agricultural producers supplying polyester chips and natural fibers. Intermediate spinners and dyers process these into finished threads, which move through distributors and wholesalers or direct sales channels to reach garment manufacturers and industrial end-users.
Investment Insights and High-Potential Areas
Investors should target companies developing bio-based synthetic threads and automated digital color-matching technologies. High-potential returns are concentrated in emerging manufacturing corridors in Southeast Asia where textile automation investments are accelerating rapidly to offset rising local labor costs.
Conclusion and Key Takeaways
The Sewing Thread Market offers steady expansion driven by a projected 4.36% CAGR reaching 4.56 Billion by 2033. Sustainability and technical innovation are the primary differentiators separating market leaders from commodity suppliers in an increasingly regulated global textile economy.
Research Methodology and Triangulation
Our proprietary baselines are established by triangulating customs and trade registry data, primary stakeholder interviews with executives at firms like Ningbo MH Industry and Durak Tekstil, and secondary macroeconomic indicators tracking global apparel production and textile machinery shipments.
Scope of the Report and Coverage Parameters
This report covers global market sizing and forecasts from 2027 to 2033, segmented by material type, end-user industry, application, and distribution channel. Limitations include macroeconomic unpredictability regarding currency exchange rates and sudden trade policy shifts in major textile-exporting nations.
Recent Developments and Strategic Moves
Recent industry activity highlights major sustainability initiatives, such as A&E expanding its recycled thread portfolio and Coats Group launching advanced carbon-neutral manufacturing lines. Strategic partnerships between thread producers and fashion brands underscore a collective industry push toward fully traceable, eco-compliant supply chains.