What is the scope and definition of the Military Communication Encryption Market?
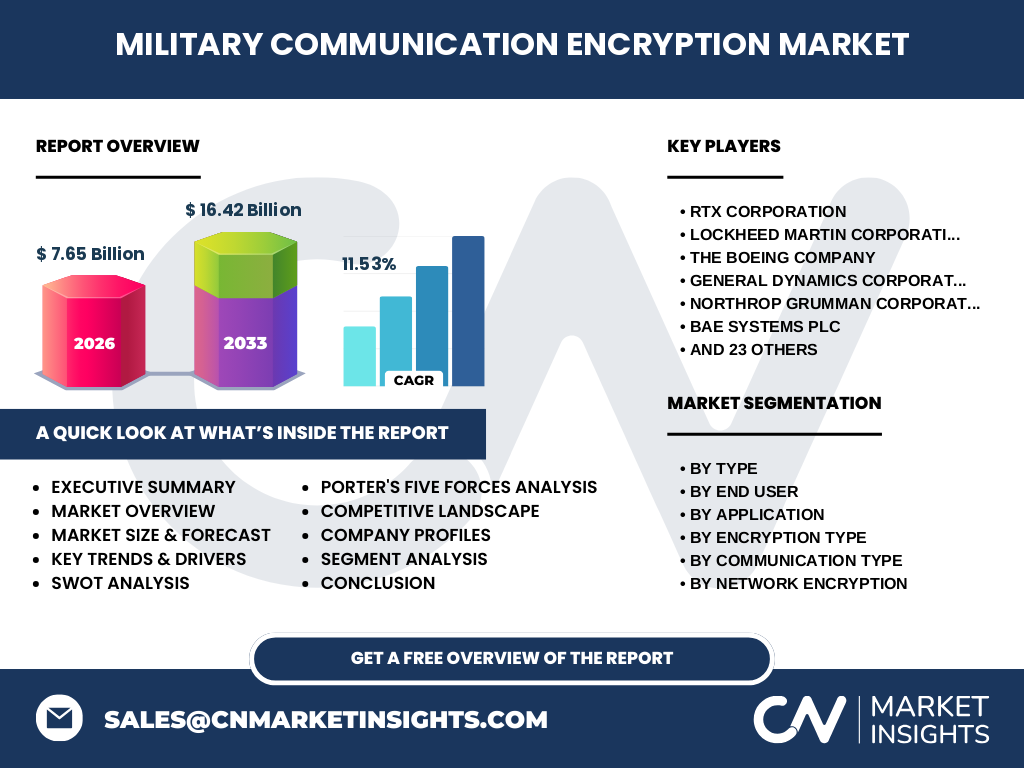
Our analysis indicates that the Military Communication Encryption Market encompasses advanced cryptographic software, hardware, and network security solutions designed to protect classified defense data. Valued at 7.65 Billion in 2026, this sector is critical for safeguarding tactical intelligence against cyber warfare and signal interception by hostile state actors.
Structural Growth Drivers and Restraints
The market is propelled by escalating geopolitical tensions and the rapid transition to software-defined tactical radios. Based on our research, prime growth drivers include modernization initiatives by the U.S. Department of Defense and European ministries. Conversely, strict export controls under ITAR regulations and complex semiconductor supply chain bottlenecks act as primary market restraints.
Emerging trends and growth patterns in Military Communication Encryption Market
The industry is witnessing a profound shift toward quantum-resistant cryptography and zero-trust network architectures to counter sophisticated electronic warfare. Industry trends highlight the integration of AI-driven anomaly detection within tactical edges, favoring agile innovators over legacy hardware suppliers.
How did the COVID-19 pandemic impact the Military Communication Encryption Market?
The pandemic caused severe supply chain disruptions for rare earth materials and specialized encryption chips used in Trusted Platform Modules. However, the subsequent recovery trajectory accelerated defense digitization budgets, driving robust demand for secure remote command systems across allied forces.
Competitive Benchmarking and Market Concentration
The competitive landscape features high market concentration among defense primes like RTX Corporation, Lockheed Martin, and Northrop Grumman. These conglomerates dominate through prime-contractor relationships, while specialized players like Viasat and TrellisWare Technologies carve out niches in resilient satellite and waveform communications.
Executive Summary of the Military Communication Encryption Market
Our comprehensive assessment projects the Military Communication Encryption Market to surge from 7.65 Billion in 2026 to reach 16.42 Billion by 2033, expanding at a robust 11.53% CAGR. This explosive growth reflects an unprecedented imperative for impenetrable battlefield connectivity.
Market Forecast and Trajectory (2027 to 2033)
Driven by multi-domain battle network upgrades, the market trajectory charts an aggressive upward path. The forecast period from 2027 to 2033 will yield a cumulative revenue expansion, scaling the market from its 2026 baseline to the projected 16.42 Billion milestone.
Segmentation Analysis of the Military Communication Encryption Market
Market segmentation spans across By Type (Software, Hardware, Network), End User (Army, Navy, Air Force, Special Forces), and Application (Secure Voice, Data, Command Systems, SatCom, Intelligence). Additional splits cover Encryption Type, Communication Type, and specific network or hardware sub-categories, aligning solutions directly with distinct branch requirements.
Geographic Distribution and Regional Market Analysis
Geographic performance is heavily skewed toward North America due to outsized Pentagon procurement budgets. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, propelled by escalating defense outlays in nations like India, supported by local manufacturers like Bharat Electronics Limited.
In-Depth Regional Review
North America anchors global demand, leveraging advanced defense ecosystems involving General Dynamics and L3Harris. Concurrently, European markets under the European Defence Agency mandate interoperable cryptographic standards, directly benefiting regional leaders such as Thales S.A., Leonardo S.p.A., and Rheinmetall AG.
Strategic Positioning of Leading Companies
Industry leaders employ aggressive mergers, acquisitions, and cross-border partnerships to secure technological superiority. Companies like BAE Systems, Elbit Systems, and Saab AB focus on modular encryption integration, ensuring seamless cross-domain operability for international defense clients.
Porter's Five Forces Analysis
The bargaining power of buyers is moderate to high, driven by stringent government procurement criteria. Threat of substitutes remains low due to specialized military-grade certifications, whereas competitive rivalry is intense among established contractors vying for lucrative multi-year defense contracts.
SWOT Analysis of the Industry
Key strengths include proprietary cryptographic algorithms and deep institutional relationships with defense ministries. Weaknesses involve long sales cycles and high R&D costs. Opportunities lie in space-based communication security, while threats include sophisticated state-sponsored quantum decryption attacks.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw semiconductor materials and cryptographic code development, flowing through hardware security module manufacturers like Mercury Systems and Curtiss-Wright, culminating in integration by prime defense contractors for end-users across Army, Navy, and Air Force branches.
High-Potential Investment Insights and Strategic Recommendations
Investors should target early-stage innovators specializing in Post-Quantum Cryptography and decentralized end-to-end software encryption. Companies possessing scalable firmware architecture are best positioned to capture outsized market share as legacy systems face forced obsolescence.
Conclusion and Key Takeaways
The Military Communication Encryption Market industry trends underscore a non-negotiable shift toward resilient, quantum-safe defense architectures. With a projected 11.53% CAGR reaching 16.42 Billion by 2033, early strategic investments in hardware-software integration will dictate long-term market dominance.
Research Methodology and Baseline Triangulation
Our research methodology triangulates data by combining exhaustive trade registry analytics, primary stakeholder interviews with defense procurement officers, and secondary macroeconomic indicators from global defense spending databases to construct accurate baseline estimates.
Scope of the Report and Coverage Parameters
This report covers global deployment dynamics of military encryption across hardware, software, and network domains from 2026 to 2033. Limitations include restricted access to classified black-budget military projects, focusing primarily on publicly disclosed defense acquisitions and commercialized military tech.
Recent Developments in Military Communication Encryption
Recent strategic moves feature major contract awards to companies like Viasat and Kratos Defense for resilient satellite security, alongside joint ventures by European defense firms to develop interoperable tactical networks complying with evolving NATO cryptographic mandates.