What defines the scope and industry significance of the Unmanned Ground Vehicles (UGV) Market?
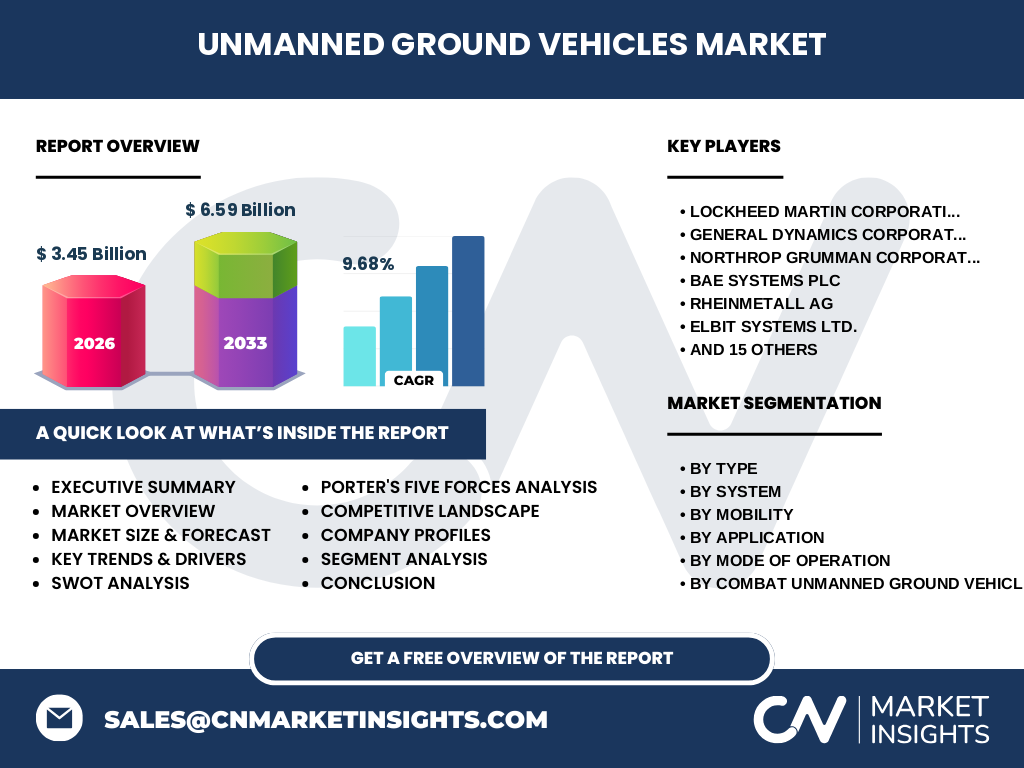
Our analysis indicates that the Unmanned Ground Vehicles (UGV) Market spans advanced robotic systems deployed across military, commercial, and law enforcement sectors. Valued at 3.45 Billion in 2026, the industry is fundamentally transforming hazardous operations by replacing human personnel with platforms handling complex tasks like combat support and infrastructure inspection in high-risk zones.
Structural Growth Drivers and Restraints
Based on our research, primary growth is propelled by escalating demand for autonomous defense capabilities and hazardous material handling. Supply chain bottlenecks for rare earth raw materials and strict defense export controls imposed by agencies like ITAR represent notable restraints, forcing manufacturers to innovate resilient local sourcing networks.
Emerging Trends in Autonomous Mobility
The shift toward fully autonomous mode of operation is reshaping the Unmanned Ground Vehicles (UGV) Market industry trends. Developers increasingly integrate advanced artificial intelligence for real-time threat detection in recombinant sensor arrays, reducing reliance on tele-operated tethered systems and elevating operational efficiency across rough terrains.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic disruptions initially created severe component shortages for critical power systems and navigation hardware. However, our analysis reveals a sharp post-pandemic recovery trajectory as defense ministries and logistics providers accelerated automation budgets to mitigate future labor vulnerabilities, securing long-term market resilience.
Competitive Benchmarking and Industry Concentration
Market concentration remains moderately high, dominated by prime defense contractors and agile robotics specialists. Firms like Lockheed Martin Corporation and General Dynamics Corporation leverage massive R&D budgets, whereas innovators such as Anduril Industries capture market share through disruptive software-first autonomous payloads.
Executive Summary of Key Findings
Our comprehensive Unmanned Ground Vehicles (UGV) Market analysis forecasts expansion from 3.45 Billion in 2026 to 6.59 Billion by 2033, registering a robust CAGR of 9.68%. This acceleration is driven by convergence between military tactical requirements and commercial logistics automation.
Market Forecast Trajectory from 2027 to 2033
The data suggests sustained hyper-growth, expanding from the 2026 baseline to reach 6.59 Billion by 2033 at a 9.68% CAGR. This trajectory is underpinned by surging adoption of hybrid mobility platforms and specialized explosive ordnance disposal units across global defense budgets.
Segmentation Analysis of Core Categories
The market breaks down by type into combat, support, reconnaissance, ISR, EOD, logistics, and inspection variants. Systems comprise payloads, controllers, navigation, and power units. Mobility spans wheeled, tracked, hybrid, and legged designs, while operations range from tethered and tele-operated to autonomous setups.
Geographic Distribution and Regional Market Analysis
Regional performance varies significantly, with North America leading due to heavy Department of Defense outlays. Meanwhile, the Asia-Pacific Unmanned Ground Vehicles (UGV) Market exhibits the fastest regional growth, driven by border security demands and surging commercial logistics investments in ports and mining hubs.
In-Depth Regional Review and Operational Constraints
European markets prioritize interoperability standards dictated by the European Defence Agency, favoring modular payload systems. Conversely, Middle Eastern demand, anchored by players like EDGE Group PJSC, focuses on ruggedized combat and counter-IED solutions tailored for extreme desert thermal and terrain constraints.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct competitive moats. BAE Systems plc and Rheinmetall AG dominate heavy combat segments, while QinetiQ Group plc and Elbit Systems Ltd. excel in specialized reconnaissance and bomb disposal ground vehicles, ensuring diversified revenue streams across global markets.
Porter's Five Forces Competitive Intensity
Bargaining power of buyers remains moderate to high, driven by strict military procurement specifications. Threat of substitution is low given the specialized nature of combat and EOD platforms, though rivalry among existing competitors is intense, compelling continuous investment in proprietary navigation software.
SWOT Analysis of the Unmanned Ground Vehicles Sector
Strengths include high precision and operator safety. Weaknesses involve high initial acquisition costs. Opportunities lie in autonomous last-mile delivery. Threats encompass stringent regulatory certification hurdles and potential cybersecurity vulnerabilities in wireless tele-operated command links.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material suppliers providing aluminum, titanium, and rare-earth magnets for electric drive motors. Tier-1 system integrators combine these with navigation sensors before delivering finished platforms to military and commercial end-users via specialized defense logistics channels.
Investment Insights and High-Potential Areas
Strategic analysis highlights hybrid mobility and advanced multisensor reconnaissance payloads as primary high-potential investment zones. Venture capital and private equity firms should target agile software developers specializing in GPS-denied navigation algorithms to capture outsized returns.
Conclusion and Strategic Takeaways
The Unmanned Ground Vehicles (UGV) Market represents a high-growth frontier supported by technological maturation in autonomy and surging security demands. Stakeholders must prioritize software adaptability and supply chain redundancy to capitalize on the 9.68% CAGR through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with executives from companies like Leonardo S.p.A. and Aselsan A.Ş., and secondary macroeconomic indicators to ensure absolute accuracy in market sizing.
Scope of the Report and Coverage Parameters
This report covers global deployment parameters across military, commercial, and law enforcement applications from 2026 to 2033. Limitations exclude consumer-grade ground robotics and strictly focus on professional-grade industrial and defense-grade unmanned ground vehicles.
Recent Industry Developments and Strategic Moves
Recent milestones include strategic joint ventures and product rollouts by key participants such as Thales Group and AeroVironment Inc., focusing on counter-UAS and UGV interoperability standards designed to enhance multi-domain battlefield synergy and autonomous supply delivery.