What is the market overview and industry significance of the Port-To-Door Container Journey Orchestration Platforms Market?
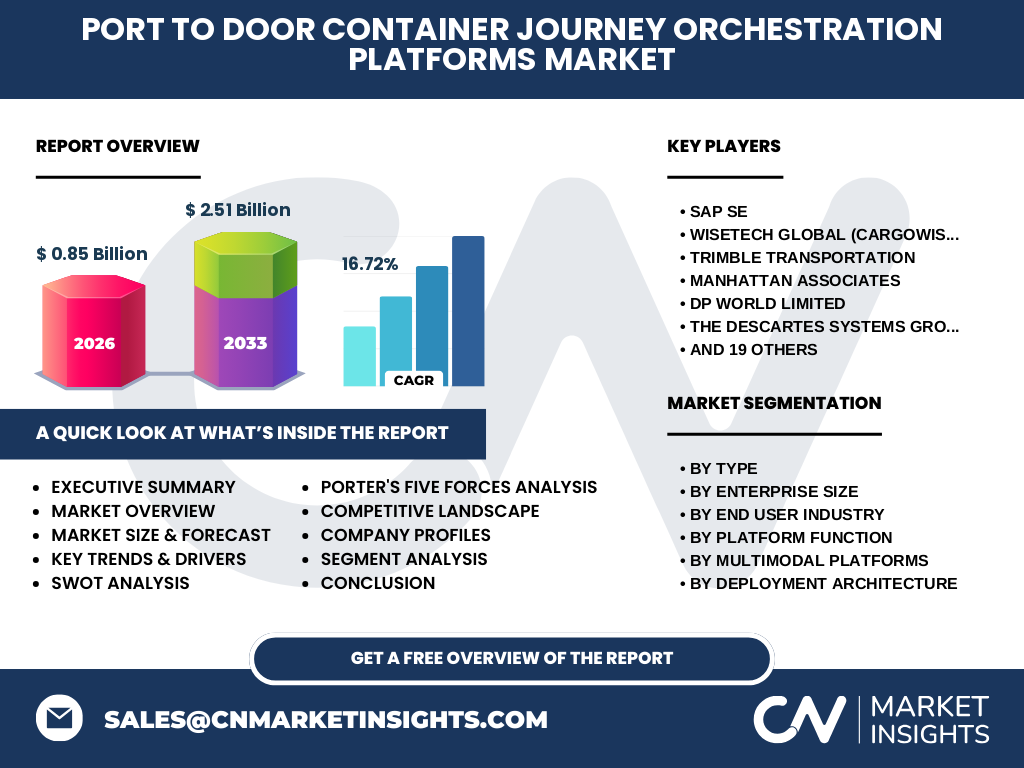
Our analysis indicates that the Port-To-Door Container Journey Orchestration Platforms Market commands a 0.85 Billion valuation in 2026. These platforms unify ocean freight, rail corridors, and final-mile trucking, dissolving traditional data silos between maritime terminals, rail ramps, and warehouse management systems to eliminate costly demurrage fees.
Structural Growth Drivers and Market Restraints
The market is propelled by severe port congestion at major gateways like LA/Long Beach and Rotterdam, alongside strict environmental mandates from the International Maritime Organization. However, prohibitive legacy IT integration costs and proprietary data hoarding by ocean carriers serve as prominent structural restraints slowing adoption.
Emerging Trends and Digital Transformation Patterns
Logistics operators are rapidly abandoning fragmented visibility tools in favor of unified orchestration suites. End-to-end operational visibility powered by real-time API integrations with carriers and terminal operating systems allows beneficial cargo owners to proactively reroute shipments before bottlenecks materialize.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic exposed severe vulnerabilities in global supply chains, triggering erratic vessel schedules and unprecedented container detention charges. This crisis catalyzed permanent demand for resilient Port-To-Door Container Journey Orchestration Platforms Market solutions, shifting executive priorities from cost-minimization to continuous supply chain orchestration.
Competitive Landscape and Strategic Market Dynamics
The market features a mix of established maritime tech vendors and agile disruptors. Industry heavyweights like WiseTech Global (CargoWise) and SAP SE provide deeply embedded enterprise integrations, while specialists like project44 Inc. and FourKites Inc. dominate real-time visibility and predictive analytics.
Executive Summary of Key Findings
The Port-To-Door Container Journey Orchestration Platforms Market industry trends point toward hyper-growth, driven by the absolute necessity of automated exception handling and real-time container tracking across complex multimodal transport legs involving ocean, rail, and drayage carriers.
Market Forecast and Long-Term Growth Trajectory
Driven by accelerating digital transformation across global supply chains, our research projects the market will expand from 2027 to 2033 to reach 2.51 Billion by 2033, expanding at a robust 16.72% CAGR over the forecast period.
Segmentation Analysis Across Technology and Enterprise Vectors
The market bifurcates across deployment models and end-user requirements. Key classifications include Artificial Intelligence Powered Platforms, Blockchain Enabled Platforms, and Multimodal Platforms, serving both large multinational enterprises and agile small and medium-sized shippers.
Regional Market Analysis and Geographic Distribution
North America and Europe currently dominate adoption due to high concentrations of advanced 3PLs and stringent customs compliance frameworks. Meanwhile, Asia-Pacific represents the fastest-growing frontier, propelled by massive container throughput at manufacturing hubs across China, Southeast Asia, and India.
In-Depth Regional Review of Trade Corridors
Trans-Pacific and Asia-Europe trade lanes generate the highest volumes of container exceptions, making them primary deployment zones for advanced orchestration platforms. Shippers operating within these corridors rely heavily on localized drayage integrations to bypass recurring terminal labor disputes.
Company Profiles and Strategic Positioning
Market leaders utilize distinct competitive moats. Flexport Inc. leverages a digital-forward forwarding model, Altana Technologies Inc. specializes in secure supply chain mapping, and Descartes Systems Group Inc. anchors its value proposition in robust global customs compliance and carrier networks.
Porter's Five Forces Analysis of the Orchestration Ecosystem
Bargaining power of buyers is moderated by high switching costs once enterprise systems are deployed. Threat of new entrants remains low due to complex API integrations required with ocean carriers, port community systems, and legacy enterprise resource planning software.
SWOT Analysis of the Orchestration Sector
Core strengths include deep multimodal visibility and automated demurrage mitigation. Significant weaknesses involve dependency on third-party carrier data feeds. Opportunities lie in automated customs clearance, while threats stem from potential cybersecurity vulnerabilities in decentralized shipping networks.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material sourcing and factory gate stuffed containers, flowing through ocean terminal gates, intermodal rail yards, and final-mile drayage networks before reaching the end-user distribution center. Orchestration platforms monetize every handoff point by reducing friction and administrative overhead.
Investment Insights and High-Potential Growth Areas
Venture capital and private equity investors are prioritizing platforms featuring predictive AI capabilities and automated demurrage reduction modules. Software vendors offering seamless pre-built integrations with legacy SAP or Oracle enterprise systems command premium valuations.
Conclusion and Strategic Takeaways
The Port-To-Door Container Journey Orchestration Platforms Market analysis confirms that real-time visibility is no longer a luxury but an operational prerequisite. Enterprises failing to adopt automated orchestration risk severe margin erosion from unchecked detention and demurrage penalties.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived by triangulating data from global maritime trade registries, primary stakeholder interviews with logistics directors at Fortune 500 shippers, and secondary macroeconomic indicators tracking worldwide container throughput and drayage volume fluctuations.
Scope of the Report and Coverage Parameters
This report covers global software deployments facilitating container tracking, booking orchestration, and exception management from origin port terminal gates to final inland consignee doors, excluding domestic bulk liquid and break-bulk non-containerized cargo logistics.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum highlights aggressive merger and acquisition activity alongside strategic API integrations between visibility providers like project44 and ocean carriers like Maersk, aimed at providing uncompromised, real-time container milestone updates directly within shipper workflows.