What defines the scope and industry significance of the Saildrone Voyager Unmanned Surface Vehicle (USV) Market?
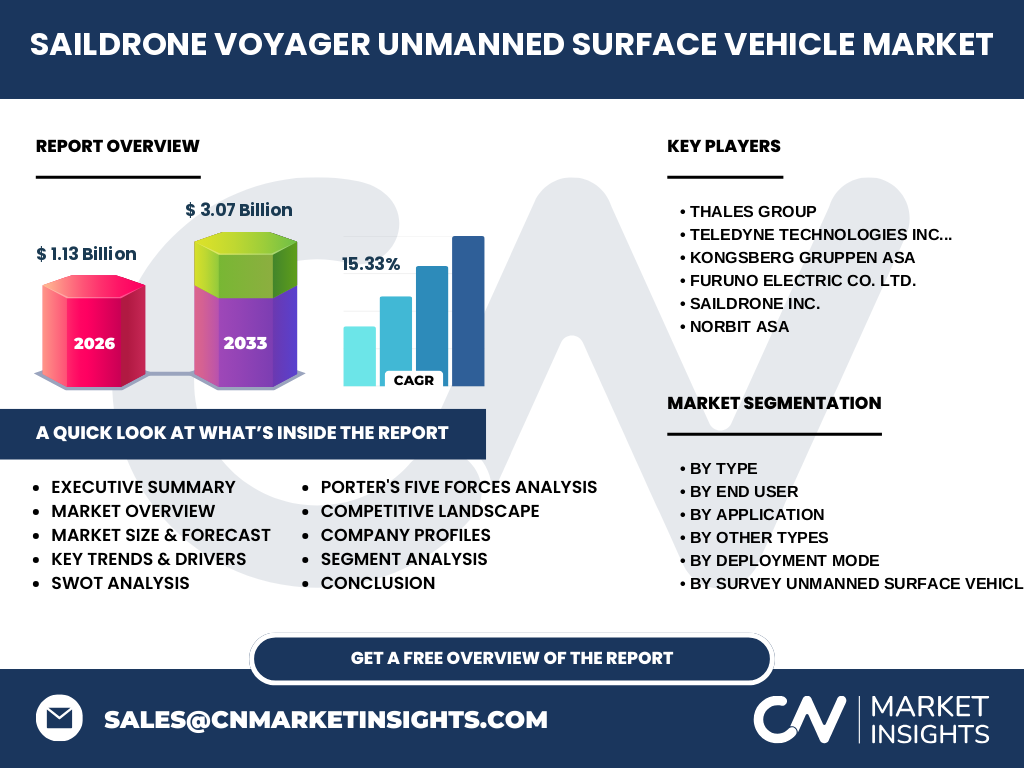
The Saildrone Voyager Unmanned Surface Vehicle (USV) Market represents a transformative shift in maritime operations, valued at $1.13 Billion in 2026. This sector encompasses autonomous and wind-powered surface platforms utilized for oceanographic research, defense, and environmental monitoring, replacing costly crewed vessels with persistent data collection capabilities.
Structural Growth Drivers and Market Restraints
Our analysis indicates that surging demand for real-time ocean data and reduced carbon emissions are primary growth drivers. Conversely, strict international maritime collision regulations and complex satellite communication bandwidth limitations act as notable restraints, challenging fleet operators navigating congested shipping lanes.
Emerging Trends Shaping the Saildrone Voyager Unmanned Surface Vehicle (USV) Market
The industry is witnessing an aggressive pivot toward hybrid propulsion systems and edge-computing payloads. Based on our research, these advancements allow platforms like those from Saildrone Inc. to process synthetic aperture radar and acoustic telemetry locally before satellite transmission, optimizing offshore operational efficiency.
COVID-19 Impact Analysis and Market Recovery
The pandemic severely disrupted global supply chains for specialized marine sensors and radar components. However, the crisis ultimately accelerated the Saildrone Voyager Unmanned Surface Vehicle (USV) Market recovery as remote-operating operators realized the necessity of un-crewed platforms during quarantine protocols.
Competitive Benchmarking and Strategic Dynamics
The market features intense consolidation among defense primes and specialized autonomous innovators. Key participants like Thales Group, Teledyne Technologies, and Kongsberg Gruppen ASA leverage extensive sonar portfolios, while Saildrone Inc. dominates wind-powered persistent endurance niches.
Executive Summary of Key Findings
The Saildrone Voyager Unmanned Surface Vehicle (USV) Market is poised for unprecedented expansion, driven by defense modernization and climate tracking initiatives. Decision-makers must note the projected valuation surge, highlighting immense commercial and governmental willingness to adopt autonomous maritime intelligence.
Market Forecast and Valuation Trajectory (2027 to 2033)
Projections show the market expanding from $1.13 Billion in 2026 to reach $3.07 Billion by 2033. This explosive growth reflects a robust compound annual growth rate (CAGR) of 15.33%, fueled by escalating offshore wind farm developments and naval surveillance needs.
Comprehensive Segmentation Breakdown
The market fragments across multiple critical vectors: By Type (Survey, Surveillance, Research), By End User (Government, Commercial, Research Institutes), and By Deployment Mode (Autonomous, Remotely Operated, Hybrid). Specialized sub-segments include hydrographic survey USVs, seabed mapping tools, and maritime security platforms.
Geographic Distribution and Regional Performance
North America leads the global landscape due to robust defense budgets and NOAA research initiatives, followed closely by Europe where stringent North Sea environmental regulations mandate continuous offshore inspection. The Asia-Pacific region demonstrates the fastest-growing adoption rate for border patrol.
In-Depth Regional Review of Key Markets
European waters, particularly the Baltic and North Seas, present unique deployment hurdles due to heavy commercial traffic and harsh weather, driving demand for Norbit ASA acoustic systems. Meanwhile, U.S. coastal waters prioritize defense-support and intelligence-gathering autonomous surface vessels.
Strategic Positioning of Leading Companies
Industry leaders carve distinct competitive moats: Furuno Electric Co. Ltd. integrates advanced radar navigation, Norbit ASA excels in ultra-high-resolution seabed mapping sonars, and Saildrone Inc. maintains a distinct operational advantage via wind-powered long-duration oceanographic tracking.
Porter's Five Forces Industry Assessment
Bargaining power of suppliers remains moderate due to specialized military-grade sensor dependencies. Conversely, threat of new entrants is low given the prohibitive capital requirements, harsh marine engineering constraints, and intellectual property barriers protecting autonomous navigation software algorithms.
SWOT Analysis of the Industry Landscape
Strengths include zero-emission propulsion and multi-month endurance. Weaknesses involve vulnerability to severe rogue sea states and biofouling. Opportunities lie in offshore energy infrastructure inspection, while threats stem from evolving maritime cybersecurity vulnerabilities and localized geopolitical piracy.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw rare-earth materials for sensor magnets, advancing to hardware manufacturing by firms like Teledyne Technologies, software integration by USV developers, and finally delivering actionable oceanographic data to end-user agencies like oil majors and naval commands.
High-Potential Investment Insights
Investors should target developers of hybrid communication relay USVs and edge-AI collision avoidance software. Our analysis indicates that companies solving satellite bandwidth constraints during mid-ocean deployments will capture disproportionate market share through reduced operational overhead.
Conclusion and Strategic Takeaways
The Saildrone Voyager Unmanned Surface Vehicle (USV) Market transitions from experimental deployments to core maritime infrastructure. Stakeholders must prioritize modular payload designs and robust cybersecurity frameworks to capitalize on the 15.33% CAGR trajectory through 2033.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by cross-referencing international maritime trade registries, primary stakeholder interviews with naval architects and oceanographers, and secondary macroeconomic indicators regarding defense spending and offshore renewable energy investments.
Scope of the Report and Coverage Parameters
This report covers global deployment metrics, technological readiness levels, and competitive benchmarking across commercial, governmental, and academic sectors. Limitations include restricted disclosure on classified military autonomous surface vessel contracts operating within restricted jurisdictional waters.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum highlights strategic joint ventures between sensor manufacturers and autonomous hull developers. Companies are aggressively launching multi-mission USVs equipped with enhanced acoustic telemetry to satisfy tightening environmental monitoring mandates imposed by international regulatory bodies.