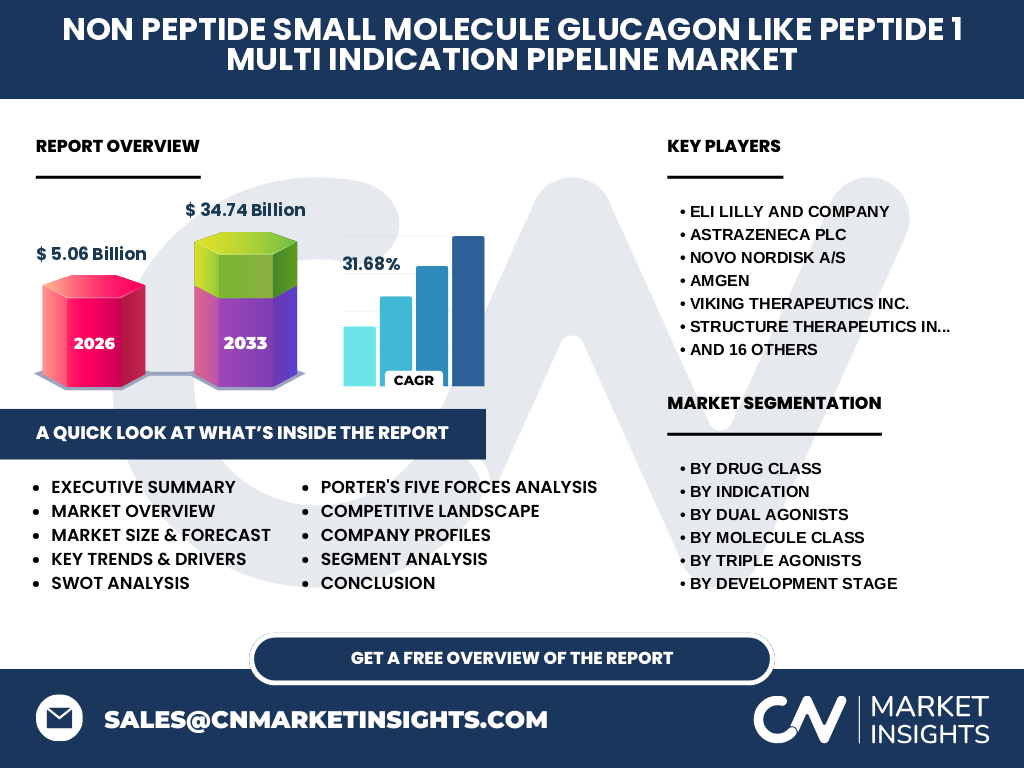
What is the market overview and scope of the Non-Peptide Small Molecule Glucagon-Like Peptide (GLP)-1 Multi-Indication Pipeline Market?
Our analysis indicates the Non-Peptide Small Molecule Glucagon-Like Peptide (GLP)-1 Multi-Indication Pipeline Market anchors a paradigm shift in metabolic therapeutics. Valued at 5.06 Billion in 2026, this sector encompasses oral and small-molecule alternatives designed to bypass peptide-related cold-chain logistics and subcutaneous delivery hurdles across chronic indications.
Structural Growth Drivers and Restraints in the Non-Peptide Small Molecule Glucagon-Like Peptide (GLP)-1 Multi-Indication Pipeline Market
Based on our research, structural drivers include rising global metabolic disease prevalence and patient preference for oral administration over injectables. However, strict FDA and EMA regulatory hurdles and complex chemical synthesis pathways for non-peptide small molecules act as persistent commercial restraints.
Emerging Trends and Growth Patterns in the Industry
The data suggests a major pivot toward multi-receptor engagement, particularly oral dual and triple agonists. Companies are prioritizing assets that address both glycemic control and systemic inflammation, unlocking pipeline value well beyond traditional type 2 diabetes management.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced supply chain disruptions temporarily stalled early-phase clinical trials for novel chemical entities. Nevertheless, the accelerated shift toward decentralized clinical trials and digital biomarker tracking has firmly positioned the industry on a robust post-pandemic recovery trajectory.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is defined by aggressive asset acquisition and licensing deals between big pharma and nimble biotech innovators. Industry leaders like Eli Lilly and Company and Novo Nordisk A/S compete fiercely with emerging players like Viking Therapeutics Inc. and Structure Therapeutics Inc.
Executive Summary of the Non-Peptide Small Molecule Glucagon-Like Peptide (GLP)-1 Multi-Indication Pipeline Market
Our comprehensive executive synthesis highlights explosive expansion, projecting the market to surge from 5.06 Billion in 2026 to 34.74 Billion by 2033. This phenomenal trajectory reflects an exceptional CAGR of 31.68% driven by expanding multi-indication clinical applications.
Long-Term Market Forecast from 2027 to 2033
The forecast models an unprecedented growth phase, vaulting from 2027 baseline evaluations toward the 34.74 Billion valuation by 2033. This sustained momentum stems from late-stage Phase 3 pipeline readouts transitioning into commercialized oral small molecules and multi-agonist therapies.
Segmentation Analysis of Drug Classes and Indications
Market segmentation spans drug classes like Pure GLP-1, Dual Agonists, Triple Agonists, and Combination Therapies. Indications cover Type Two Diabetes, Obstructive Sleep Apnea, Cardiovascular Disease, Osteoarthritis, and Hypertension, with development stages ranging from Phase One through FDA Approved.
Geographic Distribution and Regional Market Analysis
North America maintains dominant market share due to established clinical trial infrastructure and high metabolic disease burdens. Meanwhile, Asia-Pacific emerges as a high-growth frontier supported by active pipelines from regional innovators like Jiangsu Hengrui Pharmaceuticals Co Ltd. and Hansoh Pharmaceutical Group.
In-Depth Regional Review and Localized Market Constraints
Regional performance highlights stringent European pricing negotiations contrasting with reimbursement-driven adoption curves across North American markets. Logistical optimization for ambient-stable oral small molecules gives domestic developers a distinct advantage over cold-chain-dependent peptide analogues.
Company Profiles and Strategic Positioning
Leading entities leverage specialized portfolios; for instance, AstraZeneca PLC and Pfizer Inc. scale robust clinical pipelines, while specialized firms like Sciwind Biosciences Co. Ltd. and Eccogene Inc. focus on novel oral small-molecule formulations to capture niche market segments.
Porter's Five Forces Competitive Intensity Assessment
Threat of new entrants remains moderate due to steep R&D expenditures and complex chemistry manufacturing controls. However, intense rivalry among established incumbents drives aggressive patent filings around non-peptide core scaffolds.
SWOT Analysis of the Industry Ecosystem
Strengths include superior patient compliance via oral administration; weaknesses involve unpredictable pharmacokinetic profiles in early-phase molecules. Opportunities lie in underserved non-alcoholic steatohepatitis and osteoarthritis indications, while threats encompass aggressive intellectual property litigation.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from advanced chemical intermediate sourcing and heterocyclic synthesis through contract development and manufacturing organizations (CDMOs) to global pharmaceutical distribution networks and institutional end-users.
Investment Insights and High-Potential Areas
Venture capital and strategic acquirers should prioritize Phase 2 assets featuring central and peripheral metabolic dual agonists and oral small-molecule platforms capable of addressing obesity-linked cardiovascular comorbidities.
Conclusion and Strategic Takeaways
The Non-Peptide Small Molecule Glucagon-Like Peptide (GLP)-1 Multi-Indication Pipeline Market represents a generational commercial opportunity. Stakeholders must embrace oral delivery innovation and multi-indication clinical strategies to capture value within this rapidly scaling ecosystem.
Research Methodology and Baseline Triangulation
Our proprietary methodology combines primary qualitative interviews with key opinion leaders, secondary clinical trial registries, and macroeconomic trade data, triangulated through econometric modeling to validate baseline estimates and growth forecasts.
Scope of the Report and Coverage Parameters
This report evaluates global pipeline assets, commercialized small molecules, combination therapies, and regional adoption dynamics through 2033, excluding legacy injectable peptide monopolies except where used as direct clinical comparators.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is characterized by high-profile licensing agreements, strategic acquisitions of early-stage assets by giants like Roche Holding AG and Boehringer Ingelheim International GmbH, and rapid clinical advancements by specialized players like Metsera and Regor Therapeutics Group Ltd.