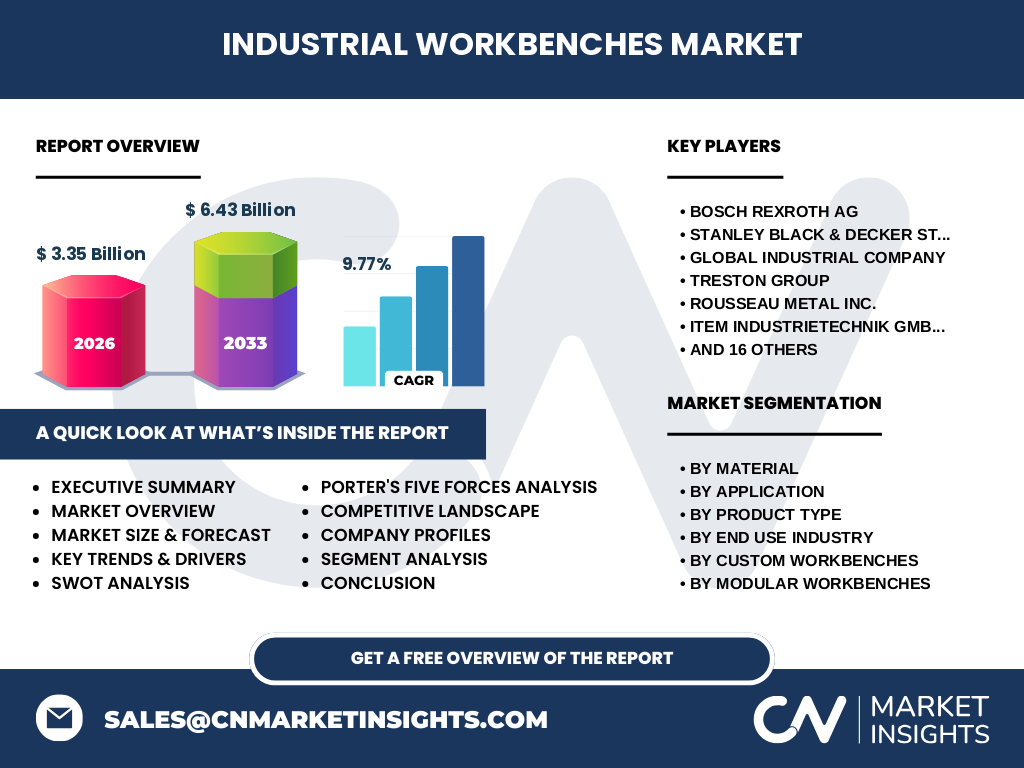
Market overview and structural scope of the Industrial Workbenches Market
The Industrial Workbenches Market represents a foundational pillar of manufacturing infrastructure, valued at 3.35 Billion in 2026. Our research indicates this sector encompasses robust surfaces, modular stations, and specialized assembly units engineered to withstand rigorous industrial environments governed by OSHA and ISO standards.
Structural Growth Drivers and Market Restraints
Growth is propelled by strict ergonomic compliance mandates and factory automation, though offset by volatile raw material costs for cold-rolled steel and seasoned lumber. Industry participants like Bosch Rexroth AG and Treston Group actively navigate these supply chain bottlenecks through localized manufacturing.
The Shift Toward Ergonomic Customization
Industry trends reveal a pronounced migration toward height-adjustable and application-specific custom workbenches. Based on our analysis, manufacturing facilities prioritize operator well-being to mitigate musculoskeletal disorders, directly benefiting innovators like Formaspace LP and Ergosource Inc. in high-precision assembly zones.
COVID-19 Impact Analysis and Post-Pandemic Recovery
Pandemic-induced supply chain disruptions severely constrained component delivery across primary distribution channels. However, the post-pandemic recovery trajectory accelerated digital procurement and automated production, stabilizing the market on its path toward a robust 6.43 Billion valuation by 2033.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features intense rivalry among key players such as Stanley Black & Decker Storage Solutions, Rousseau Metal Inc., and Global Industrial Company. Market concentration is moderate to high, with leaders leveraging extensive distributor networks and proprietary locking mechanisms to secure enterprise contracts.
Executive Summary of Industrial Workbenches Market Findings
Our comprehensive audit projects the Industrial Workbenches Market to expand at a formidable CAGR of 9.77% from 2027 to 2033. This expansion is underpinned by technological integration in electronics assembly and stringent safety requirements across heavy automotive and aerospace maintenance facilities.
Long-Term Market Forecast Through 2033
The data projects consistent scaling from the 2026 baseline of 3.35 Billion to reach 6.43 Billion by 2033. This trajectory reflects sustained capital expenditure in smart factories and automated logistics hubs requiring heavy-duty static load-bearing structures.
Comprehensive Segmentation Breakdown
The market is segmented by material (Steel, Wood, Aluminum, Stainless Steel), product type (Heavy Duty, Modular, Portable, Custom), application (Assembly Lines, Quality Control, Repair), and end-use sectors including automotive, aerospace, and healthcare, ensuring tailored solutions for every industrial workflow.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading due to early adoption of automated smart manufacturing. Meanwhile, Asia-Pacific exhibits the fastest growth velocity, fueled by rapidly expanding automotive and electronics manufacturing hubs in Southeast Asia and China.
In-Depth Regional Review
North American demand is heavily anchored by stringent ANSI/BIFMA standards and aerospace manufacturing clusters. In contrast, European markets emphasize eco-friendly materials and strict ergonomic compliance, creating specialized opportunities for regional operators like Item Industrietechnik GmbH.
Strategic Company Profiles
Leading entities like Kewaunee Scientific Corporation focus on laboratory-grade chemical-resistant surfaces, whereas Penco Products Inc. and Borroughs Corporation dominate heavy-duty steel configurations. Their strategic positioning relies on continuous product innovation and localized distribution partnerships.
Porter's Five Forces Industry Assessment
Bargaining power of suppliers remains moderate due to steel commodity fluctuations, while buyer power is heightened by numerous well-established catalog distributors. Threat of substitutes is remarkably low given the specialized load capacities required by industrial end-users.
SWOT Analysis of the Industrial Workbenches Sector
Key strengths lie in high product durability and modular flexibility. Weaknesses involve high shipping logistics costs for heavy freight. Opportunities emerge in integrated ESD-safe electronics benches, while severe market threats stem from counterfeit structural components violating ISO load thresholds.
Value Chain Analysis and Logistics Flow
The value chain initiates with primary raw material extraction (iron ore, timber, aluminum bauxite), moving through stamping and powder-coating processing plants, and terminating via direct sales, industrial distributors, and digital online retail platforms to end-users.
Strategic Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in integrated technology custom workbenches and ESD-grounded electronics stations. These segments command higher profit margins and align directly with the technological modernization initiatives of major industrial clients.
Conclusion and Strategic Takeaways
The Industrial Workbenches Market presents a lucrative investment horizon driven by a 9.77% CAGR. Stakeholders must prioritize modular adaptability and ergonomic compliance to capture market share in high-growth electronics and aerospace segments.
Proprietary Research Methodology
Baseline market estimates are triangulated by cross-referencing customs trade registries, primary stakeholder interviews with C-level executives at firms like Vestil Manufacturing Corporation and IAC Industries, and secondary macroeconomic indicators tracking global industrial capital expenditure.
Scope of the Report and Operational Parameters
This report covers global revenue performance for industrial workbenches from 2026 to 2033. Excluded from this scope are residential garage furniture and commercial office desks, maintaining strict focus on heavy industrial, laboratory, and manufacturing applications.
Recent Industry Developments and Strategic Moves
Recent developments feature Shure Manufacturing Corporation and Pro-Line Manufacturing Company Inc. launching IoT-enabled height-adjustable smart benches. These product launches highlight an industry-wide pivot toward connected, data-driven manufacturing environments.