Market Overview of the Chronic Disease Management Platforms Market
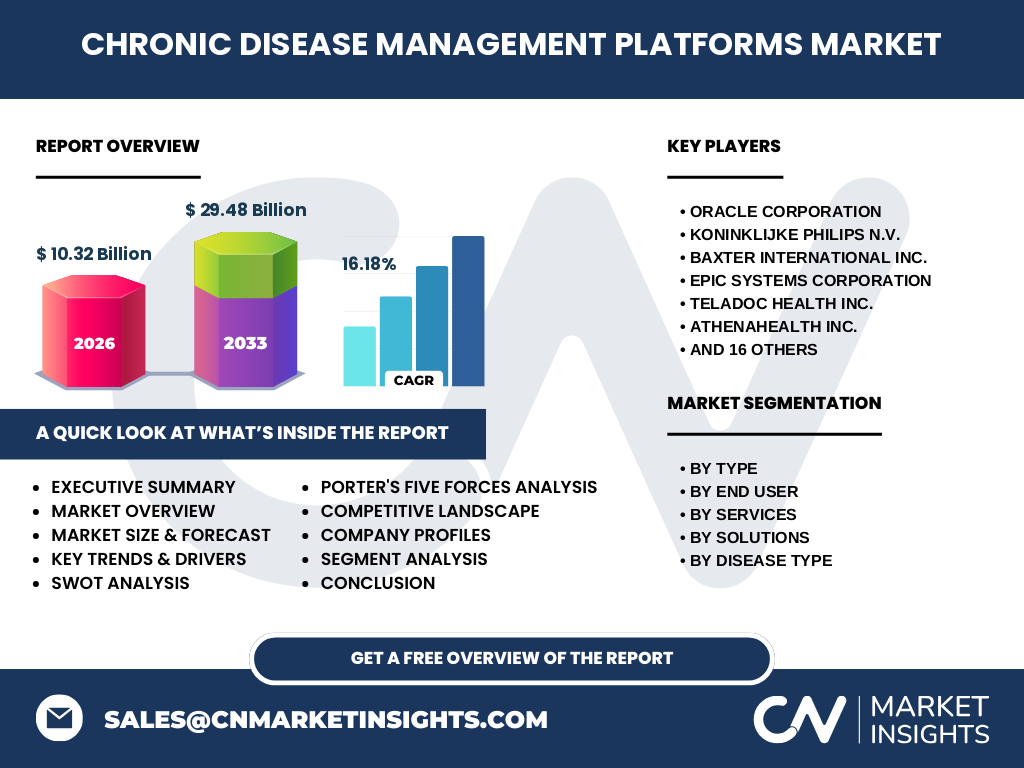
Our analysis indicates that the Chronic Disease Management Platforms Market is valued at $10.32 Billion in 2026. This sector encompasses digital health infrastructure designed to streamline care delivery for chronic illnesses, bridging clinical workflows and patient portals to ensure regulatory compliance with HIPAA and ONC interoperability standards.
Structural Growth Drivers and Restraints in the Industry
The market is driven by the surging prevalence of comorbidities such as diabetes and cardiovascular conditions. However, severe data privacy bottlenecks and complex integration hurdles with legacy electronic health record systems act as prominent restraints, slowing down enterprise-wide adoption among risk-bearing provider groups.
Emerging Industry Trends and Digital Transformation
The shift toward proactive, value-based care models is accelerating. Innovators like Innovaccer Inc. and Arcadia Solutions LLC are leveraging advanced predictive analytics to minimize hospital readmissions, directly impacting reimbursement models tied to quality-of-care metrics.
Pandemic Impact and Post-Crisis Recovery Trajectory
COVID-19 fundamentally altered the sector by forcing emergency regulatory waivers for telehealth. This catalyzed widespread adoption of remote monitoring solutions, propelling post-pandemic recovery as healthcare systems permanently integrate virtual care layers into their chronic care operational frameworks.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of tech giants and specialized startups. Companies like Oracle Corporation and Epic Systems Corporation dominate enterprise acute settings, whereas specialized platforms such as Omada Health Inc. and DarioHealth Corp. capture niche digital therapeutics segments.
Executive Summary of Strategic Findings
Our research confirms a robust expansion trajectory, driven by surging telehealth demand and payer-provider convergence. Stakeholders must prioritize interoperability and artificial intelligence integration to capture high-margin opportunities across both solutions and services portfolios.
Market Forecast for the Chronic Disease Management Platforms Market
The data projects the market to expand from $10.32 Billion in 2026 to reach $29.48 Billion by 2033, expanding at a notable CAGR of 16.18%. This trajectory reflects increasing institutional investments in automated population health infrastructure.
Segmentation Analysis by Solution, Service, and Disease Type
The market is segmented by type into solutions and services. Solutions encompass population health, telehealth, and remote patient monitoring, while Services cover consulting, implementation, and managed offerings tailored for conditions like cardiovascular diseases, diabetes, and respiratory ailments.
Regional Market Analysis and Geographic Distribution
North America retains the dominant revenue share due to favorable federal reimbursement codes and high venture capital activity. Meanwhile, the Asia-Pacific region exhibits the fastest-growing adoption rate, propelled by government-backed digital health modernization initiatives across urban healthcare hubs.
In-Depth Regional Review of Adoption Barriers
Regional performance hinges on reimbursement parity laws. While US markets leverage Medicare Advantage incentives for remote monitoring, European markets navigate stringent CE-MDR medical device regulations, shaping distinct go-to-market strategies for international software vendors.
Company Profiles and Strategic Positioning
Market leaders utilize distinct strategic plays. Koninklijke Philips N.V. focuses on hospital-to-home monitoring continuity, Teladoc Health Inc. leverages direct-to-consumer virtual care scale, and specialized players like HealthSnap Inc. and Optimize Health Inc. target turnkey chronic care management billing workflows for primary care practices.
Porter's Five Forces Analysis of Competitive Intensity
Industry rivalry is intense due to low switching costs among point solutions, yet high enterprise switching costs protect legacy electronic health record vendors. Supplier power remains moderate, countered by the heavy bargaining leverage of large integrated delivery networks and national payers.
SWOT Analysis of the Industry Ecosystem
Key strengths include scalable recurring revenue models and proven clinical outcomes. Weaknesses involve data fragmentation. Opportunities lie in artificial intelligence-driven diagnostics, whereas threats stem from cybersecurity vulnerabilities and tightening data localization compliance laws.
Value Chain Analysis from Infrastructure to End-Users
The value chain flows from cloud infrastructure providers and data standards organizations to platform developers, ultimately delivering clinical decision support tools to healthcare providers and payers managing high-risk patient cohorts.
Investment Insights and High-Potential Opportunities
Investors should target platforms integrating conversational artificial intelligence and automated billing capabilities. Companies like Murphi AI Inc. and TimeDoc Health LLC exemplify high-potential targets addressing administrative burnout among clinical care coordinators.
Conclusion and Strategic Takeaways for Industry Leaders
Achieving market leadership requires shifting from passive record-keeping to active, predictive intervention. Platforms embedding behavioral analytics and frictionless provider workflows will capture disproportionate share through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with chief medical officers, health-system trade registry databases, and secondary macroeconomic indicators regarding healthcare expenditure growth.
Scope of the Report and Coverage Parameters
This report evaluates global software deployments, associated implementation services, and recurring subscription revenues across provider and payer segments. Excluded from this scope are consumer wellness wearable devices lacking clinical-grade data transmission capabilities.
Recent Developments and Strategic Industry Moves
Recent strategic moves emphasize ecosystem consolidation through acquisitions. Partnerships between digital therapeutics providers like Vida Health Inc. and major health plans highlight an industry-wide push toward integrated, risk-shared chronic disease management delivery models.