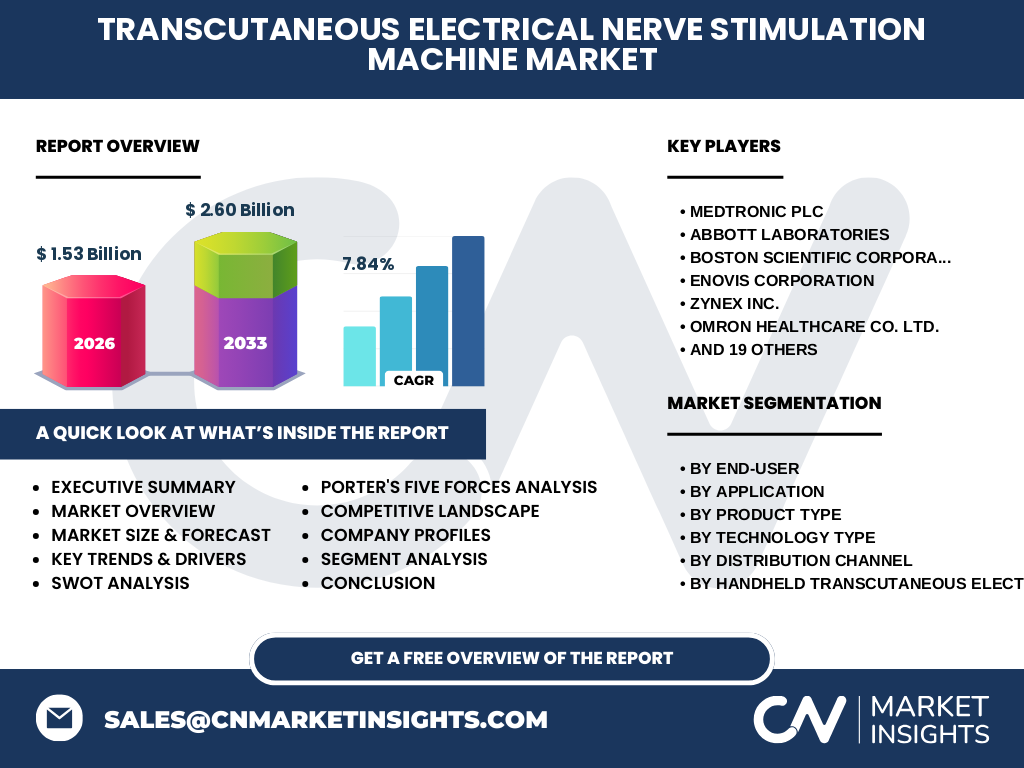
What is the market overview of the Transcutaneous Electrical Nerve Stimulation (TENS) Machine Market?
Our analysis indicates the Transcutaneous Electrical Nerve Stimulation (TENS) Machine Market represents a vital segment of non-pharmacological pain management. Valued at $1.53 Billion in 2026, the industry centers on bioelectric medical devices utilizing electrodes to deliver electrical impulses across nerve pathways, significantly reducing pharmaceutical dependency for chronic conditions.
Structural Growth Drivers and Restraints
Based on our research, market expansion is heavily propelled by rising incidences of musculoskeletal disorders and an aging global demographic. However, stringent compliance frameworks enforced by regulatory bodies like the US FDA and CE marking protocols present substantial market entry barriers and prolonged product approval cycles for manufacturers.
Emerging Industry Trends in Transcutaneous Electrical Nerve Stimulation
The data suggests a profound shift toward miniaturization, notably through Smart Application Connected Devices and patch-based wearables. Innovators like Omron Healthcare and Zynex Inc. are capitalizing on this by integrating Bluetooth telemetry, empowering patients with real-time biofeedback and clinician-monitored pain therapy regimens.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially paralyzed elective physiotherapy clinics and disrupted global supply chains for specialized microcontrollers and conductive hydrogels. Yet, our analysis reveals this catalyzed an unprecedented surge in Home Care Settings adoption, driving robust long-term post-pandemic recovery across consumer-facing electrotherapy channels.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately fragmented, featuring heavyweights like Medtronic, Abbott Laboratories, and specialized players such as TensCare Ltd. and Enovis Corporation. Competitive advantage hinges on aggressive R&D spending for wireless integration and direct-to-consumer digital marketing strategies to capture retail segments.
Executive Summary of the Global Industry Report
Our comprehensive review highlights a burgeoning medical device sector projected to expand from $1.53 Billion in 2026 to $2.60 Billion by 2033 at a robust 7.84% CAGR. Growth is anchored by technological convergence, demographic shifts, and rising consumer preference for drug-free pain management solutions.
Long-Term Market Forecast from 2027 to 2033
The data projects consistent upward momentum, pushing industry valuations from the 2026 baseline toward the $2.60 Billion mark by 2033. This 7.84% CAGR trajectory reflects accelerating adoption across emerging economies and continuous hardware innovation in rechargeable and multi-channel portable units.
Segmentation Analysis of Applications and End-Users
Our research segments demand by end-user into Hospitals, Clinics, and Home Care Settings, while applications span Pain Management, Rehabilitation, and Physiotherapy. Technology types further diversify the landscape, incorporating Conventional TENS, Interferential Current, Microcurrent Electrical Therapy, and High Voltage Pulsed Current therapy.
Geographic Distribution and Regional Market Performance
North America commands the largest market share due to advanced healthcare infrastructure and high chronic pain prevalence. Meanwhile, the Asia-Pacific region demonstrates the fastest growth velocity, driven by expanding healthcare expenditure, rising disposable incomes, and the proliferation of local manufacturing hubs in countries like China and Japan.
In-Depth Regional Review and Localized Constraints
European markets exhibit steady growth underpinned by stringent medical device regulations (MDR) that favor established compliance leaders like Beurer GmbH and axion GmbH. Conversely, North American adoption is heavily influenced by reimbursement policies from major insurers and Medicare coverage frameworks for durable medical equipment.
Company Profiles and Strategic Positioning
Industry leaders like Boston Scientific Corporation and Zimmer Biomet focus on advanced neurostimulation, while consumer-focused entities like Drive DeVilbiss Healthcare and Compass Health Brands dominate retail distribution. Companies increasingly utilize strategic mergers and FDA 510(k) clearances to expand their electrotherapy portfolios.
Porter's Five Forces Analysis of the Sector
Our analysis indicates moderate-to-high competitive rivalry driven by numerous low-cost Asian manufacturers. Supplier power remains low regarding raw silver-chloride electrodes and ABS plastics, whereas buyer power is substantial due to intense e-commerce price transparency across online retail and specialty pharmacy stores.
SWOT Analysis of the Industry Landscape
Strengths include high consumer acceptance of non-invasive therapies and strong technological pipelines. Weaknesses involve reimbursement uncertainties. Opportunities lie in AI-driven personalized pain therapy algorithms, while threats encompass intense generic competition and stringent regulatory compliance hurdles across global jurisdictions.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing silicon chips, lithium-ion batteries, and conductive hydrogels. Original Equipment Manufacturers (OEMs) assemble these components into wearable or handheld units before passing them through medical distributors, pharmacies, and specialty online stores to reach patients.
Investment Insights and High-Potential Growth Areas
Strategic analysis highlights Smart Application Connected Devices and wireless wearable patches as primary investment hotspots. Venture capital and corporate M&A are targeting digital health startups that integrate biofeedback telemetry with traditional TENS hardware to improve patient adherence and clinical outcomes.
Conclusion and Key Takeaways for Industry Stakeholders
The market is poised for exceptional expansion, driven by technological evolution and surging consumer demand for drug-free alternatives. Stakeholders must prioritize software integration, regulatory navigation, and robust e-commerce distribution strategies to capture significant value as the market scales toward $2.60 Billion by 2033.
Research Methodology and Baseline Triangulation
Our research methodology employs rigorous data triangulation, combining primary stakeholder interviews with key executives at firms like Nevro Corp. and BioMedical Life Systems Inc., alongside secondary macroeconomic indicators, national trade registry data, and proprietary econometric modeling to ensure baseline accuracy.
Scope of the Report and Coverage Parameters
This report covers the global landscape across product types, technologies, applications, distribution channels, and geographic regions. Limitations include the exclusion of experimental bioelectric therapies outside standard clinical definitions and localized black-market medical device sales lacking official regulatory clearance.
Recent Industry Developments and Strategic Moves
Recent developments feature Shenzhen XFT Medical Limited and HealthmateForever LLC launching advanced dual-channel rechargeable units with FDA clearances. Furthermore, strategic partnerships between consumer tech brands and traditional medical device manufacturers are accelerating the commercialization of app-connected, travel-friendly lightweight units.