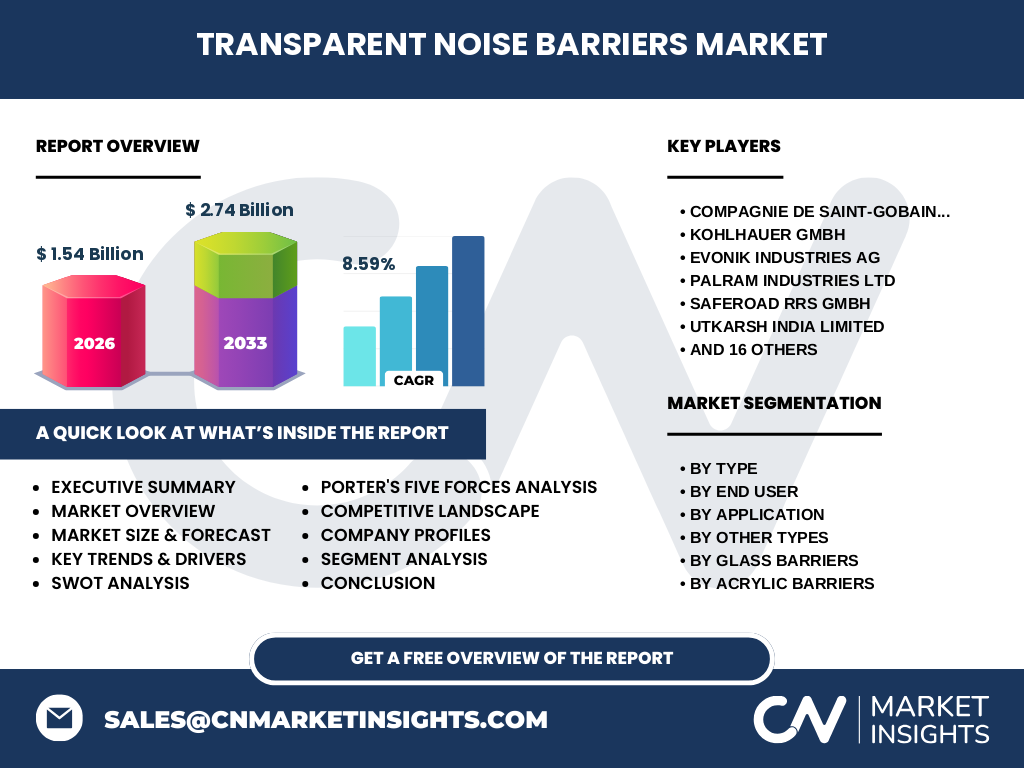
Market overview of the Transparent Noise Barriers Market
Our analysis indicates the Transparent Noise Barriers Market is valued at $1.54 Billion in 2026. This sector encompasses advanced acoustic mitigation infrastructure utilizing high-clarity materials like acrylic and glass to preserve urban aesthetics while reducing highway and railway noise pollution.
Structural Growth Drivers and Restraints
The market is propelled by strict acoustic regulations enforced by bodies like the FHWA and European Union directives. However, high raw material volatility for resins and stringent structural load requirements for wind resistance act as key growth restraints.
Emerging industry trends in Transparent Noise Barriers Market
Industry trends highlight a rapid shift toward hybrid acrylic glass barriers and integrated solar photovoltaic panels. Companies are heavily investing in anti-reflective and UV-resistant coatings to extend panel lifespans along busy transportation corridors.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain bottlenecks for raw polymethyl methacrylate (PMMA) and delayed municipal infrastructure spending. Recovery has been robustly steered by government stimulus packages targeting green transportation and public transit upgrades.
Competitive landscape and strategic market dynamics
The market features moderate concentration, with heavyweights like Compagnie de Saint-Gobain SA and Evonik Industries AG dominating through proprietary chemical formulations. Regional players compete fiercely on customized installation and localized distribution networks.
Executive summary of key findings
Our research projects the Transparent Noise Barriers Market to expand to $2.74 Billion by 2033, exhibiting a CAGR of 8.59% from 2027. Urbanization and railway expansion remain the primary catalysts for this accelerated valuation trajectory.
Transparent Noise Barriers Market forecast from 2027 to 2033
Driven by rising infrastructure investments across developing economies, the market will scale from its 2026 baseline to reach $2.74 Billion by 2033. Accelerated highway electrification and high-speed rail projects will consistently fuel demand throughout this forecast window.
Segmentation analysis across types, applications, and end-users
Segmentation is categorized by type (Acrylic, Polycarbonate, Glass), application (Highways, Railways, Airports), and end-user (Government Agencies, Construction Firms). Acrylic barriers maintain dominance due to high impact resistance and superior optical clarity in weathering conditions.
Regional market analysis and geographic distribution
Geographic performance shows Europe leading in regulatory compliance adoption, while Asia-Pacific registers the fastest growth due to massive highway and high-speed rail network expansions managed by regional transit authorities.
In-depth regional review of key markets
North American growth is underpinned by Department of Transportation mandates for noise abatement along interstate expansions. Meanwhile, European markets prioritize aesthetic integration in dense urban rail corridors utilizing specialized tempered glass solutions.
Strategic positioning of leading companies
Firms such as Palram Industries Ltd and Plaskolite LLC leverage advanced extrusion technologies to capture market share. Strategic partnerships with engineering EPC contractors allow these firms to secure long-term municipal supply contracts.
Porter's Five Forces analysis of the sector
Supplier power remains moderate due to specialized chemical inputs, while buyer power is high among municipal procurement agencies. Threat of substitutes is low, as traditional concrete walls lack the aesthetic transparency required by modern urban planners.
SWOT analysis of the industry
Strengths include high aesthetic appeal and proven acoustic performance. Weaknesses involve high installation costs. Opportunities lie in emerging smart cities, while threats stem from polycarbonate supply chain disruptions and raw material price fluctuations.
Value chain analysis from raw materials to end-users
The value chain initiates with chemical refiners supplying PMMA and polycarbonate resins, progressing to specialized panel extruders like Donchamp Acrylic Co Ltd, and culminating in installation by civil engineering contractors for municipal agencies.
Investment insights and strategic recommendations
High-potential areas include manufacturing scratch-resistant polycarbonate barriers and composite panels for high-speed rail networks. Investors should target regional fabricators possessing direct framework agreements with government transport departments.
Conclusion and key takeaways for stakeholders
The Transparent Noise Barriers Market offers robust growth to $2.74 Billion by 2033. Stakeholders must focus on UV-stabilized material innovations and sustainable manufacturing practices to capture high-margin municipal tenders globally.
Research methodology for baseline estimates
Our analysis triangulates data by synthesizing customs trade registries, primary interviews with chief technology officers at firms like Ecotone Systems Ltd, and secondary macroeconomic indicators regarding global transportation infrastructure budgets.
Scope of the report and coverage parameters
This report covers global revenue projections from 2027 to 2033, evaluating acoustic performance metrics, regulatory compliances, and pricing models across ground-mounted and structure-mounted installations, excluding private residential soundproofing interiors.
Recent developments and strategic moves in the industry
Recent market activities feature Saferoad RRS GmbH launching modular, recycled-content acoustic panels, and KOHLHAUER GmbH expanding its European production footprint to meet stringent EU railway noise abatement directives.