Market overview and structural scope of the Artificial Intelligence (AI)-Enhanced Antenatal Remote Monitoring Market
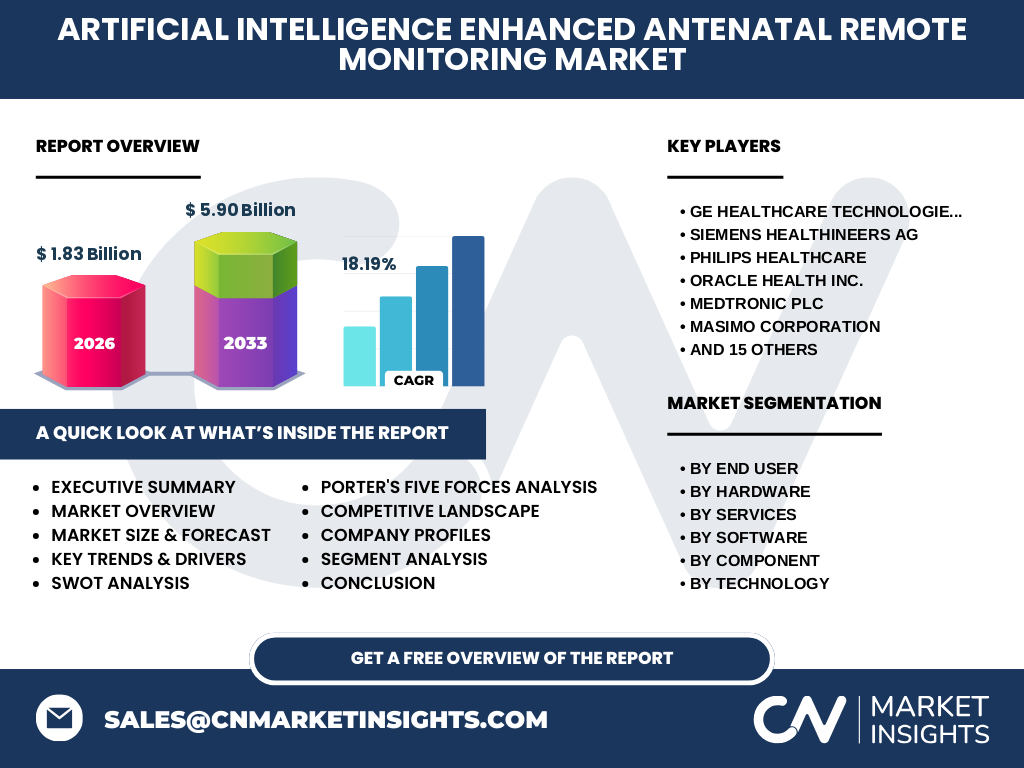
Our analysis indicates that the Artificial Intelligence (AI)-Enhanced Antenatal Remote Monitoring Market is valued at 1.83 Billion in 2026. This burgeoning sector integrates advanced machine learning algorithms with connected medical hardware to transform maternal-fetal healthcare. Regulatory frameworks overseen by bodies like the FDA and EMA heavily govern these diagnostic tools, which rely on precision sensors and cloud platforms to mitigate obstetric risks outside traditional clinical settings.
What are the core market drivers, restraints, challenges, and opportunities in this space?
Growth is propelled by rising maternal ages and a shortage of obstetricians, counterbalanced by stringent HIPAA data compliance and reimbursement hurdles. Opportunities abound in low-resource settings where IoT-enabled monitoring bridges healthcare deserts. Key logistical challenges involve ensuring stable cellular connectivity for real-time fetal heart rate telemetry in rural zones.
Emerging trends and growth patterns shaping the industry landscape
The sector is witnessing a rapid shift toward predictive analytics and decentralized maternity care. Mobile health applications combined with wearable sensor arrays are enabling continuous, passive data collection. This trend favors agile innovators capable of turning raw physiological data into actionable clinical insights without requiring patient friction.
How did the COVID-19 pandemic alter the trajectory of antenatal remote monitoring?
The pandemic served as an unprecedented catalyst, forcing healthcare providers to rapidly adopt virtual care models to minimize viral exposure in hospitals. Regulatory flexibilities accelerated emergency clearances for remote solutions. Our research shows this disruption permanently altered consumer expectations, embedding remote monitoring into standard prenatal pathways.
Competitive Benchmarking: Major players and strategic dynamics
The market features a mix of established medtech giants and agile disruptors. Firms like GE HealthCare Technologies Inc., Siemens Healthineers AG, and Philips Healthcare leverage vast distribution networks, while specialized players such as Nuvo Group Ltd. and Babyscripts Inc. drive software-led innovation, creating a dynamic landscape of strategic acquisitions and proprietary ecosystem lock-ins.
Executive summary of key findings and valuation metrics
Our comprehensive evaluation confirms that the Artificial Intelligence (AI)-Enhanced Antenatal Remote Monitoring Market is poised for explosive expansion, reaching 5.90 Billion by 2033 at a robust CAGR of 18.19%. Stakeholders must prioritize cloud-native interoperability and secure data pipelines to capture market share across high-risk pregnancy and routine care segments.
Market forecast trajectory from 2027 to 2033
Driven by accelerating digital health adoption and clinical validation of AI algorithms, the market will scale aggressively from its 2026 baseline of 1.83 Billion to achieve the 5.90 Billion milestone by 2033. This trajectory represents a stellar 18.19% CAGR, outperforming traditional medical device sectors significantly.
Segmentation analysis across hardware, software, services, and end-users
The market breaks down by component into software, hardware, and services. Hardware includes wearable monitoring devices and sensor units, while software encompasses clinical decision support systems and data analytics platforms. End-users span hospitals, clinics, and homecare settings, with high-risk pregnancy management driving primary adoption.
Geographic distribution and regional performance dynamics
Regional performance varies based on reimbursement policies, broadband penetration, and maternal healthcare infrastructure. North America currently leads due to high venture capital infusion and early enterprise adoption, whereas Asia-Pacific represents the fastest-growing frontier driven by expanding digital health initiatives in densely populated urban centers.
In-depth regional review of high-growth territories
North America benefits from mature telehealth billing codes, whereas European markets experience rigorous oversight from national health agencies like the UK's NICE. Meanwhile, developing pockets in Asia-Pacific rely heavily on mobile-first deployments by localized innovators such as Janitri Innovations Private Limited and CareNX Innovations Private Limited.
Strategic company profiling of industry leaders and innovators
Industry participants employ distinct strategic moats. Medtronic plc and Oracle Health Inc. focus on enterprise EHR integration, whereas specialized startups like Bloomlife Inc., Marani Health, and HeraMED Limited target direct-to-consumer and provider-backed remote diagnostics, optimizing clinical workflows through proprietary machine learning models.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to standardized microchip and sensor raw materials. However, buyer power is high among large hospital networks negotiating enterprise contracts. Threat of substitution is low given the specialized regulatory hurdles of clinical-grade maternal monitoring, while competitive rivalry among AI software vendors is exceptionally fierce.
SWOT analysis of the Artificial Intelligence (AI)-Enhanced Antenatal Remote Monitoring Market
Strengths include high diagnostic accuracy and reduced hospital readmissions. Weaknesses involve data privacy vulnerabilities and integration friction with legacy hospital IT. Opportunities lie in emerging market expansion, while threats stem from potential algorithmic bias and stringent FDA post-market surveillance requirements.
Value chain analysis from raw materials to end-users
The value chain originates with semiconductor and biocompatible polymer suppliers, feeding into original equipment manufacturers of wearable and portable devices. Cloud infrastructure providers and AI developers then process the telemetry, culminating in clinical interpretation by obstetric teams within hospitals, clinics, or homecare settings.
Investment insights and strategic deployment recommendations
Investors should target platforms offering seamless EHR interoperability and FDA-cleared predictive analytics. Companies focusing on cloud-based deployment models and remote patient monitoring services present the highest upside, particularly those partnering with major payers to secure recurring reimbursement streams.
Conclusion and critical industry takeaways
The Artificial Intelligence (AI)-Enhanced Antenatal Remote Monitoring Market is transitioning from a nascent novelty to an essential pillar of modern obstetrics. With a projected valuation of 5.90 Billion by 2033, success hinges on rigorous clinical validation, data security compliance, and user-centric software design that minimizes clinician burnout.
Methodological framework used in triangulating baseline estimates
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, trade registry data from medical device imports, and primary qualitative interviews with Chief Medical Officers, obstetricians, and regulatory affairs experts across key global markets to ensure absolute data integrity.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue streams from 2026 to 2033 across specified hardware, software, service, and end-user segments. Limitations include unforeseen shifts in international reimbursement policies and rapid regulatory updates governing SaMD (Software as a Medical Device) classifications across various global jurisdictions.
Recent developments, strategic partnerships, and product launches
Recent industry momentum features pivotal moves by players like Pulsenmore Ltd., PeriGen Inc., and Validic Inc., launching enhanced remote ultrasound and AI-driven early warning systems. Strategic collaborations between tech innovators and insurance providers continue to validate the commercial viability of home-based maternal care models.