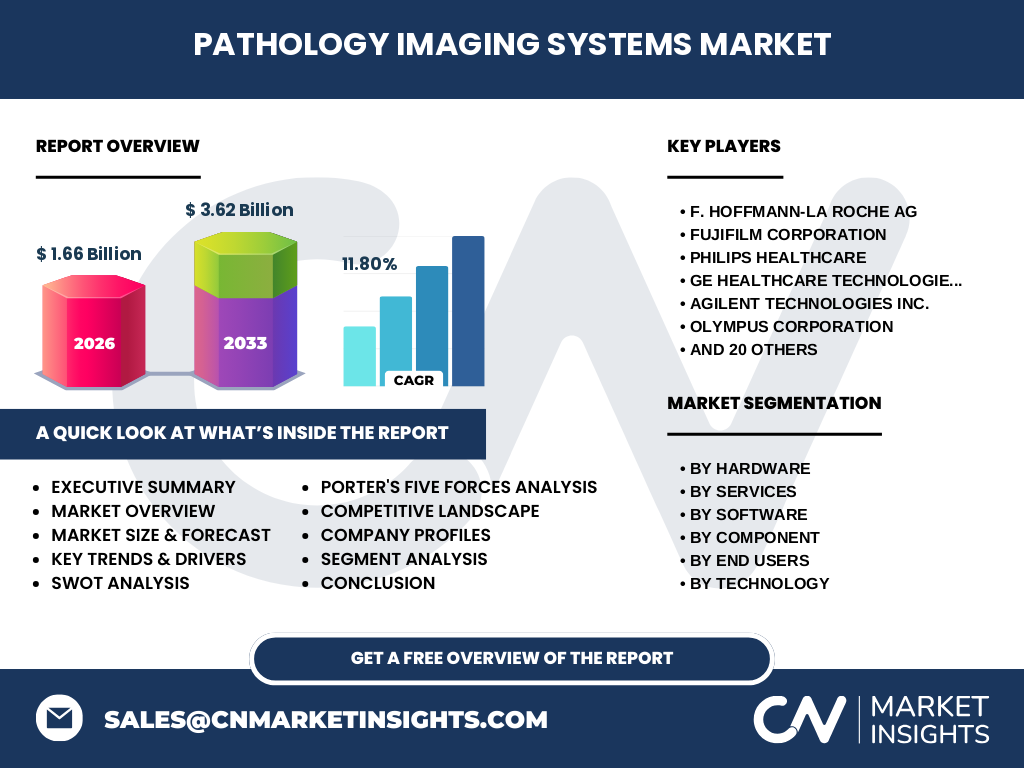
Market Overview of the Pathology Imaging Systems Market
Our analysis indicates that the Pathology Imaging Systems Market is valued at 1.66 Billion in 2026, representing a critical shift in digital pathology. This sector encompasses advanced hardware like microscopes and scanners, alongside diagnostic software and installation services, transforming traditional glass slide workflows into high-resolution digital ecosystems for hospitals and research organizations.
What are the core drivers, restraints, and opportunities in the Pathology Imaging Systems Market?
The Pathology Imaging Systems Market industry trends highlight rising chronic disease prevalence and the demand for automated diagnostic tools as primary drivers. High capital costs for ultra-fast scanning systems and stringent FDA regulatory clearances act as major restraints, while expanding remote pathology consultations present lucrative opportunities.
Emerging Growth Patterns and Technological Shifts
The Pathology Imaging Systems Market analysis reveals a profound migration toward cloud-based visualization platforms and AI-driven diagnostic software. Companies like Paige.ai and PathAI are leading this transition, enabling laboratories to process complex whole-slide images without heavy investments in on-premise server infrastructure.
COVID-19 Impact Analysis and Market Recovery
The pandemic severely disrupted global supply chains for optical glass and specialized sensors, delaying hospital procurement cycles. However, the crisis ultimately accelerated adoption in the Pathology Imaging Systems Market as remote sign-outs became essential, driving a robust post-pandemic recovery centered on resilient, decentralized digital workflows.
Competitive Benchmarking and Industry Concentration
Our research shows a moderately consolidated Pathology Imaging Systems Market dominated by heavyweights like F. Hoffmann-La Roche AG, Philips Healthcare, and Leica Biosystems. These market leaders leverage extensive global distribution networks and proprietary scanner-software integration to maintain high entry barriers against emerging diagnostic software startups.
Executive Summary of the Pathology Imaging Systems Market
Our proprietary research demonstrates that the Pathology Imaging Systems Market is poised for explosive expansion, scaling from 1.66 Billion in 2026 to 3.62 Billion by 2033 at a robust CAGR of 11.80%. Accelerated by artificial intelligence integration and cloud deployment, this growth reshapes global clinical diagnostics.
Pathology Imaging Systems Market Forecast (2027 to 2033)
Driven by compounding clinical demand, the Pathology Imaging Systems Market size will surge from 2027 to 2033 to reach 3.62 Billion by the end of the forecast period. This trajectory reflects an exceptional 11.80% CAGR, fueled by widespread digital pathology reimbursement approvals across key international healthcare jurisdictions.
Comprehensive Segmentation Analysis
The Pathology Imaging Systems Market spans multiple categories: Hardware (scanning systems, microscopes, digital cameras), Software (image analysis, diagnostic software), and Services (maintenance, consulting). End users comprise hospitals, diagnostic laboratories, and research organizations, utilizing both on-premise and cloud-based deployments powered by AI and conventional digital imaging.
Geographic Distribution and Regional Performance
Regional performance in the Pathology Imaging Systems Market varies significantly based on local reimbursement policies and healthcare IT infrastructure. North America commands the largest share due to early digital adoption in major hospital networks, while Asia-Pacific represents the fastest-growing frontier driven by expanding diagnostic laboratory investments.
In-Depth Regional Review and Local Constraints
Our analysis indicates that Europe represents a highly mature landscape within the Pathology Imaging Systems Market, strictly regulated by the In Vitro Diagnostic Regulation (IVDR). Meanwhile, Latin America and the Middle East face localized logistical hurdles regarding high-speed internet connectivity necessary for cloud-based whole-slide image streaming.
Strategic Positioning of Leading Companies
Industry participants occupy distinct niches within the Pathology Imaging Systems Market. Hamamatsu Photonics K.K. and 3DHistech excel in high-speed scanning hardware, whereas Visiopharm A/S and Indica Labs focus on advanced image analysis software. F. Hoffmann-La Roche AG and Philips Healthcare provide comprehensive end-to-end enterprise solutions for large hospital systems.
Porter's Five Forces Assessment
Competitive rivalry in the Pathology Imaging Systems Market remains intense among established scanner manufacturers. Supplier power is moderate due to specialized optical components, while the threat of substitution is low given the clinical necessity of digital pathology over traditional microscopy for AI workflows.
SWOT Analysis of the Industry
Key strengths of the Pathology Imaging Systems Market include high diagnostic accuracy and workflow efficiency. Weaknesses involve steep initial hardware expenses. Opportunities lie in emerging oncology diagnostics, while threats stem from cybersecurity vulnerabilities associated with cloud-stored patient whole-slide imaging data.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with optical glass and semiconductor sensor manufacturers supplying raw inputs to scanning hardware developers. Software providers then integrate AI algorithms before distributors deliver these integrated platforms to hospitals and diagnostic laboratories, maximizing clinical throughput.
Strategic Investment Insights and High-Potential Areas
Investors should target early-stage developers of machine learning-enabled diagnostic software and cloud infrastructure providers within the Pathology Imaging Systems Market. These segments offer superior scalability and recurring revenue models compared to traditional capital-intensive hardware manufacturing.
Conclusion and Strategic Takeaways
The Pathology Imaging Systems Market offers exceptional growth potential, anchored by an 11.80% CAGR through 2033. Stakeholders must prioritize AI integration and software-as-a-service delivery models to capture high-margin opportunities across clinical diagnostic laboratories worldwide.
Research Methodology and Baseline Estimation
Our baseline estimates for the Pathology Imaging Systems Market are triangulated by combining trade registry data, primary stakeholder interviews with chief pathologists, and secondary macroeconomic healthcare indicators to ensure absolute quantitative accuracy and market intelligence reliability.
Scope of the Report and Coverage Parameters
This report covers global revenue performance for the Pathology Imaging Systems Market from 2026 to 2033, analyzing hardware, software, services, and end-user segments across North America, Europe, Asia-Pacific, and Rest of World, while excluding non-medical microscopy applications.
Recent Developments and Strategic Industry Moves
Recent strategic moves in the Pathology Imaging Systems Market feature major partnerships between scanner manufacturers and AI pure-plays like Paige.ai and Ibex Medical Analytics. These collaborations focus on securing regulatory clearances for automated cancer detection algorithms embedded directly into digital pathology viewing platforms.