What is the market overview and industry significance of the Precision Filter Infusion Sets Market?
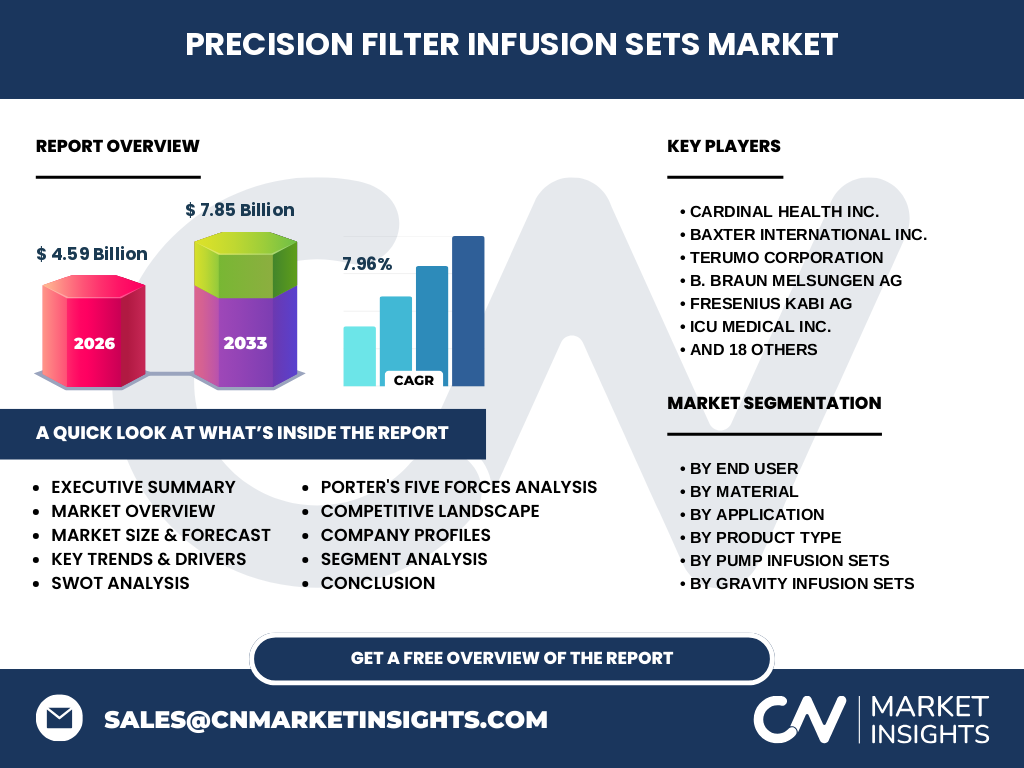
Our analysis indicates that the Precision Filter Infusion Sets Market represents a critical segment in modern clinical care, valued at $4.59 Billion in 2026. These devices prevent particulate debris and microbubbles from entering the bloodstream during intravenous therapy. Regulatory compliance with bodies like the US FDA and EMA makes medical-grade polymers essential for manufacturers.
Key market drivers, restraints, challenges, and opportunities shaping Precision Filter Infusion Sets Market
Growth is driven by surging global oncology therapies and stringent safety mandates requiring advanced filtration. However, raw material price volatility for medical-grade Polyvinyl Chloride and Silicone creates supply chain friction. Opportunities lie in developing specialized Vented Precision Filter Infusion Sets to reduce medication errors in critical care units.
Emerging trends and growth patterns in Precision Filter Infusion Sets Market
The shift toward ambulatory and home care settings has accelerated demand for lightweight Ambulatory Pump Infusion Sets. Manufacturers are increasingly adopting eco-friendly, DEHP-free thermoplastic elastomers. This transition helps healthcare facilities meet stringent environmental standards while safeguarding vulnerable patient populations from chemical leaching.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted the Precision Filter Infusion Sets Market due to elective surgery cancellations and logistical bottlenecks at major global shipping hubs. Post-pandemic recovery has been robust, fueled by government-backed healthcare infrastructure investments and localized reshoring of manufacturing lines by heavyweights like B. Braun Melsungen AG and Baxter International Inc.
Competitive landscape and strategic dynamics
The market features high consolidation among tier-one multinational enterprises alongside agile regional players like Shandong Weigao Group and Poly Medicure Limited. Major competitors leverage aggressive merger and acquisition strategies, strategic distribution partnerships, and proprietary anti-adhesion coating technologies to capture market share across emerging economies.
Executive summary of key findings
Our comprehensive research confirms a projected expansion to $7.85 Billion by 2033, expanding at a robust CAGR of 7.96%. Hospital procurement departments are prioritizing closed-system Pump Infusion Sets to reduce needlestick injuries and infusion-related complications, reshaping industry revenue streams significantly.
Market forecast from 2027 to 2033
Driven by rising chronic disease prevalence and expanded health insurance coverage across developing regions, the market will scale rapidly from 2027 through 2033. Increased adoption of specialized Chemotherapy delivery systems will serve as the primary revenue catalyst during this forecast horizon.
Segmentation analysis across material, application, product, and end-user categories
Segmentation spans Polyethylene, Polyurethane, and Silicone material types. End users encompass Hospitals, Clinics, and Home Care Settings. Applications range from Diabetes management to Gastroenterology. Product lines are bifurcated into Gravity Infusion Sets and Pump Infusion Sets, each tailored for specific clinical workflows.
Regional market analysis and geographic performance distribution
North America dominates global consumption due to advanced hospital infrastructure and high reimbursement rates for safety-engineered devices. Meanwhile, the Asia-Pacific region exhibits the fastest growth trajectory, propelled by expanding healthcare access in China and India, alongside heavy investments by domestic innovators like Terumo Corporation.
In-depth regional review of key markets
In Europe, stringent medical device regulations under the European Union Medical Device Regulation (EU MDR) require rigorous clinical evaluations for Non Vented Precision Filter Infusion Sets. Conversely, Latin American and Middle Eastern markets focus on cost-effective Standard Gravity Infusion Sets, balancing budgetary constraints with clinical safety demands.
Strategic positioning of leading company profiles
Industry leaders like Cardinal Health Inc., Fresenius Kabi AG, and ICU Medical Inc. focus on vertical integration and direct hospital supply contracts. Meanwhile, specialized players such as Vygon SAS and Codan Medizinische Geräte emphasize high-precision filtration engineering for oncology and neonatal care.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized resin requirements, while buyer power is high among large hospital group purchasing organizations. Threat of substitution is low given strict clinical validation protocols, though intense rivalry among established multinationals keeps profit margins tightly contested.
SWOT analysis of the Precision Filter Infusion Sets Market
Strengths include established distribution networks and high device reliability. Weaknesses involve susceptibility to raw material price shocks. Opportunities center on emerging market expansion and home healthcare tech integration. Threats include stringent regulatory approval delays by bodies like the PMDA and US FDA.
Value chain analysis from raw materials to end-users
The value chain initiates with petrochemical refiners supplying medical-grade polymers, followed by precision injection molding and membrane assembly by tier-one manufacturers. Distributors and group purchasing organizations then facilitate logistics to end-users in Ambulatory Surgical Centers and major hospital networks.
Investment insights and strategic recommendations
Stakeholders should direct capital toward automated manufacturing lines for Volumetric Pump Infusion Sets to reduce labor overhead. Partnerships with regional distribution hubs in Southeast Asia represent high-potential avenues for capturing untapped ambulatory care market share.
Conclusion and key takeaways for industry stakeholders
The Precision Filter Infusion Sets Market presents compelling long-term value, underpinned by a 7.96% CAGR reaching $7.85 Billion by 2033. Success hinges on regulatory compliance, material innovation, and strategic alignment with the global shift toward home-based infusion therapies.
Research methodology for baseline estimation and data triangulation
Our methodology triangulates trade registry data, customs import-export logs, secondary macroeconomic indicators, and primary interviews with C-level executives across major firms like Moog Inc. and Nipro Corporation. Bottom-up sizing models validate top-down macroeconomic projections for high accuracy.
Scope of the report and coverage parameters
This report covers global consumption, production, and regulatory landscapes for precision filter infusion sets from 2026 to 2033. Excluded from this scope are standard non-filtered intravenous administration sets and veterinary-specific infusion devices, ensuring laser focus on human clinical applications.
Recent developments, product launches, and strategic partnerships
Recent industry momentum highlights strategic joint ventures and FDA clearances for smart infusion pumps integrated with advanced microfiltration. Companies like Romsons Scientific & Surgical and JMS Co. Ltd. continue expanding production footprints to meet surging demand for specialized oncology delivery systems.