What is the valuation scope of the Ethylene Oxide Derivatives Market?
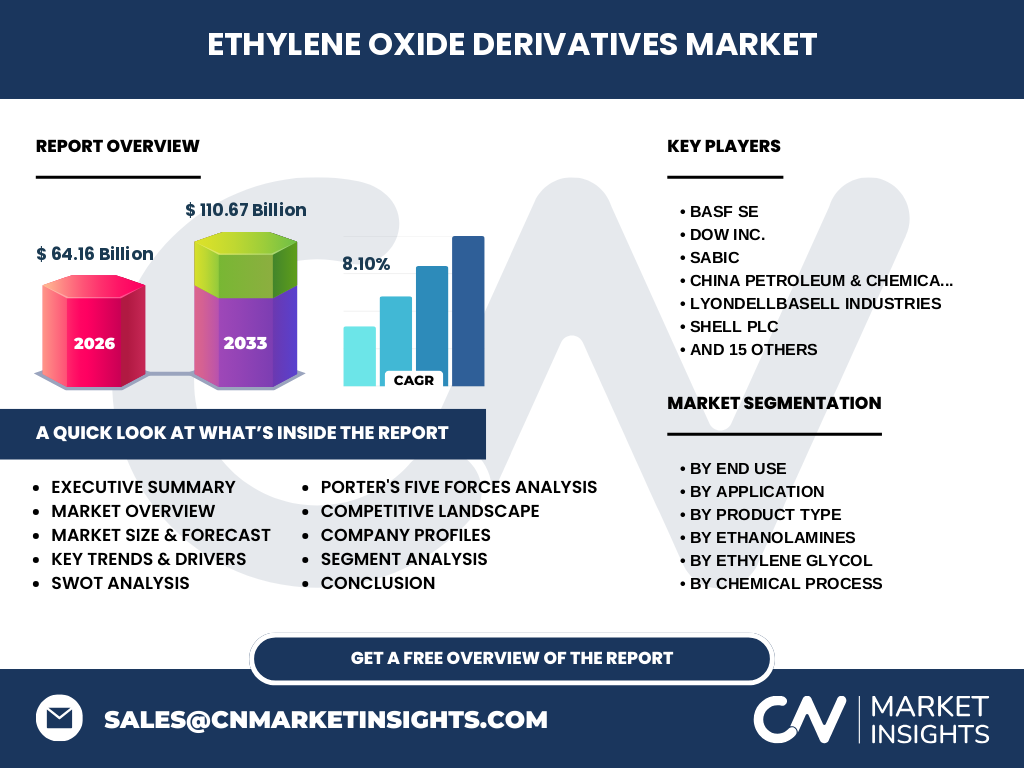
Our analysis indicates that the Ethylene Oxide Derivatives Market is valued at $64.16 Billion in 2026. This foundational chemical sector underpins critical industrial value chains, converting high-purity ethylene oxide into high-performance surfactants, glycols, and ethanolamines that drive manufacturing globally.
Structural Growth Drivers and Market Restraints
The Ethylene Oxide Derivatives Market industry trends point to strong demand from the automotive and construction sectors acting as primary catalysts. However, severe supply chain bottlenecks regarding maritime transport of hazardous ethylene oxide derivatives and stringent environmental regulations imposed by agencies like the EPA act as notable restraints.
Emerging Trends in the Ethylene Oxide Derivatives Market
A definitive shift toward bio-based feedstocks and sustainable ethoxylation processes is reshaping the Ethylene Oxide Derivatives Market market size trajectory. Major producers are investing heavily in low-carbon mono ethylene glycol to meet tightening corporate sustainability targets across personal care and textile applications.
COVID-19 Impact and Post-Pandemic Recovery
The pandemic caused severe supply disruptions across key chemical hubs, yet the Ethylene Oxide Derivatives Market demonstrated resilience driven by surging demand for sanitization surfactants and medical-grade polyethers. Recovery has accelerated robustly, anchoring the trajectory toward our 2033 targets.
Competitive Benchmarking and Market Concentration
Market concentration in the Ethylene Oxide Derivatives Market analysis is high, dominated by integrated petrochemical giants. Leaders like BASF SE, Dow Inc., and SABIC leverage integrated feedstock pipelines from steam crackers to maintain insurmountable cost advantages over merchant-market competitors.
Executive Summary of the Ethylene Oxide Derivatives Market
Driven by robust downstream adoption, the Ethylene Oxide Derivatives Market stands at a critical juncture. Valued at $64.16 Billion in 2026, the sector is positioned for exceptional expansion, offering high-margin opportunities for technologically agile chemical producers.
Long-Term Market Forecast through 2033
Based on our research, the Ethylene Oxide Derivatives Market is projected to surge to $110.67 Billion by 2033, expanding at a remarkable 8.10% CAGR. This sustained acceleration reflects deep-seated integration across emerging industrial applications.
Segmentation Analysis of Applications and Products
The Ethylene Oxide Derivatives Market segmentation is anchored by product types including Ethylene Glycol, Diethylene Glycol, Triethylene Glycol, and Ethanolamines. End-use verticals span Textiles, Automotive, Construction, Food And Beverage, and Personal Care, with chemical processes utilizing Hydration, Ethoxylation, and Polymerization.
Geographic Distribution and Regional Performance
Regional performance in the Ethylene Oxide Derivatives Market varies significantly, with Asia-Pacific dominating production and consumption volume due to rapid industrialization. North America and Europe follow closely, maintaining strict regulatory compliance while driving high-value specialty ethanolamine and surfactant demand.
In-Depth Regional Review and Localized Constraints
Analyzing key regional markets reveals that strict emissions mandates in Europe challenge traditional oxidation processes, forcing firms to upgrade facilities. Meanwhile, capacity expansions in the Middle East by players like SABIC leverage cheap feedstock availability to disrupt global pricing structures.
Strategic Positioning of Leading Companies
Industry titans such as China Petroleum & Chemical Corporation (Sinopec), LyondellBasell Industries, and Shell plc dominate the landscape through mega-scale production. Specialty players like Croda International Plc. and Clariant AG focus on high-margin downstream surfactants and niche personal care applications.
Porter's Five Forces Analysis
The Ethylene Oxide Derivatives Market exhibits moderate-to-high supplier power due to specialized feedstock dependencies, while buyer power remains constrained by the critical technical specifications required for automotive and polymer-grade ethylene glycol. Threat of substitution is mitigated by high switching costs.
SWOT Analysis of the Global Sector
Strengths include extensive downstream versatility across glycols and surfactants. Weaknesses involve high capital expenditure and hazardous material transport hurdles. Opportunities lie in green ethoxylation technologies, while threats stem from volatile ethylene feedstock pricing and stringent environmental compliance.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with steam cracking of naphtha or ethane to produce ethylene, which is subsequently oxidized into ethylene oxide. Downstream converters then process this intermediate into specialized ethanolamines, polyethers, and glycols for end-use markets like textiles and automotive.
Strategic Investment Insights and High-Potential Areas
Investors should target greenfield projects focusing on polymer-grade mono ethylene glycol and high-purity specialty ethanolamines. Companies possessing proprietary low-emission ethoxylation technology present superior valuation upside as regulatory scrutiny intensifies worldwide.
Conclusion and Strategic Takeaways
The Ethylene Oxide Derivatives Market offers compelling growth backed by a robust 8.10% CAGR leading to $110.67 Billion by 2033. Strategic alignment with sustainability trends and supply chain vertical integration will dictate future market leadership.
Proprietary Research Methodology
Our baseline estimates are triangulated by combining global trade registry data, primary executive interviews with key stakeholders at firms like INEOS Group and ExxonMobil Chemical Company, and secondary macroeconomic indicators tracking industrial chemical output across key ports.
Scope of the Report and Coverage Parameters
This comprehensive market research report covers global and regional production metrics, pricing trends, and technological processes across 2026 to 2033. Limitations include inherent macroeconomic volatilities and geopolitical shifts affecting chemical feedstock availability.
Recent Industry Developments and Strategic Moves
Recent developments highlight strategic capacity expansions by Indorama Ventures Public Company Limited and green partnerships by Nouryon and AkzoNobel N.V. These maneuvers aim to secure sustainable feedstock loops and optimize logistical footprints amid evolving global trade dynamics.