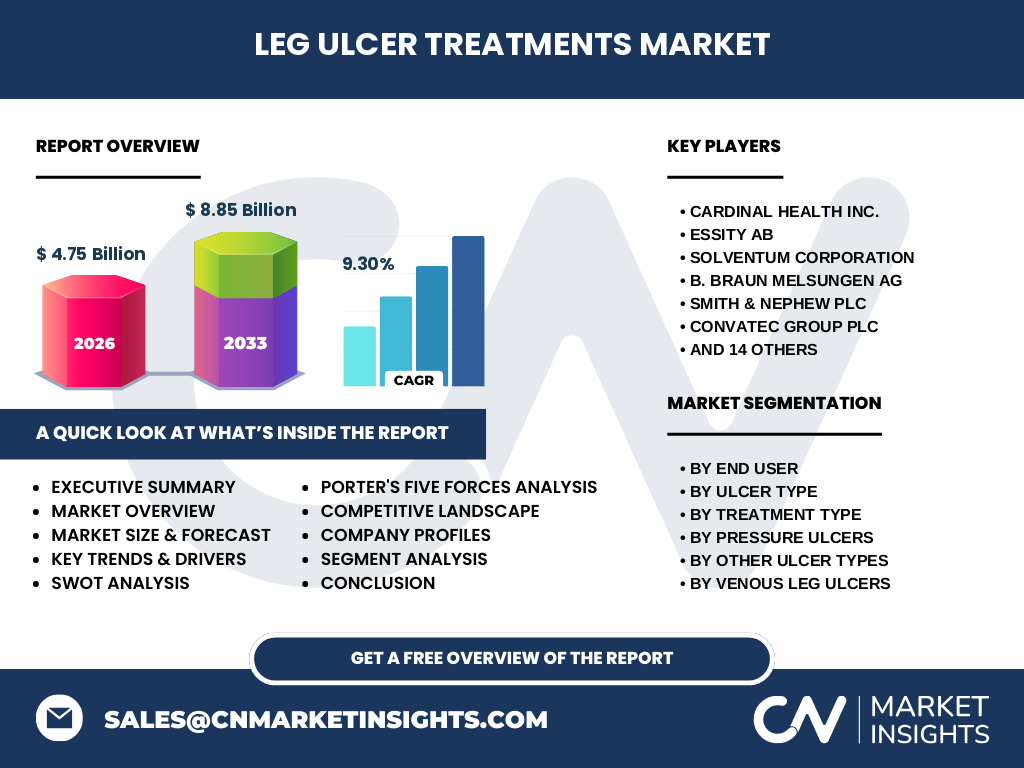
Market overview of the Leg Ulcer Treatments Market
Our analysis indicates that the Leg Ulcer Treatments Market is valued at 4.75 Billion in 2026, driven by an aging global demographic and rising diabetes prevalence. This sector encompasses advanced therapies and traditional care managed under strict FDA and EMA frameworks, involving critical raw materials like purified alginates and specialized collagen matrices.
What are the primary drivers and restraints shaping the Leg Ulcer Treatments Market?
The market is propelled by a surge in chronic venous insufficiency and diabetic foot complications. However, growth is restrained by high acquisition costs for advanced dressings and stringent reimbursement hurdles enforced by regional payers like CMS, creating logistical friction for market entrants.
Emerging trends and growth patterns in the Leg Ulcer Treatments Market
A definitive shift toward bioengineered skin substitutes and single-use negative pressure wound therapy dominates current pipelines. Industry innovators are prioritizing homecare-friendly devices to reduce hospital-acquired infection risks, aligning with modern outpatient care models.
How did COVID-19 impact the Leg Ulcer Treatments Market recovery trajectory?
Pandemic-era elective procedure deferrals caused temporary volume contractions, yet catalyzed the rapid adoption of telehealth-guided wound monitoring. Supply chain bottlenecks involving medical-grade polymers have since given way to resilient localized manufacturing networks.
Competitive Benchmarking in the Leg Ulcer Treatments Market
Market concentration is high, led by giants like Smith & Nephew plc, Essity AB, and Coloplast A/S. These enterprises leverage extensive distribution networks and robust R&D pipelines in advanced wound care to maintain competitive moats against agile regional competitors.
Executive Summary of the Leg Ulcer Treatments Market report
Our comprehensive research demonstrates that the Leg Ulcer Treatments Market is poised for expansion, reaching 8.85 Billion by 2033 at a 9.30% CAGR. Strategic investments in regenerative medicine and ambulatory delivery models represent the highest-yield opportunities for stakeholders.
Market Forecast from 2027 to 2033
The market exhibits robust momentum, scaling from its 2026 baseline to 8.85 Billion by 2033. This trajectory is underpinned by a robust 9.30% CAGR, heavily influenced by escalating venous and diabetic ulcer incidence rates globally.
Segmentation Analysis of the Leg Ulcer Treatments Market
Segmentation is categorized by end user, ulcer type, and treatment type. Key divisions include Hospitals and Clinics, Homecare Settings, and Ambulatory Surgical Centers. Ulcer types span Venous, Arterial, Diabetic, and Pressure Ulcers, treated via Advanced Wound Care Therapy, Traditional Care, and Surgical Interventions.
Geographic Distribution and Regional Performance
North America commands the largest revenue share due to high healthcare expenditure and advanced reimbursement structures, followed closely by Europe. Meanwhile, Asia-Pacific emerges as the fastest-growing region, fueled by expanding healthcare infrastructure in urban centers.
In-depth Regional Review of High-Growth Territories
Regional performance is anchored by stringent regulatory approvals from bodies like the FDA in North America and the European Medicines Agency in Europe. Asia-Pacific countries demonstrate rising adoption of advanced biologics, albeit tempered by out-of-pocket expenditure constraints.
Strategic Positioning of Leading Companies
Industry leaders such as Mölnlycke Health Care AB, Organogenesis Holdings Inc., and Solventum Corporation deploy differentiated portfolios. Their strategies center on proprietary silicone foam dressings, cellular matrices, and strategic acquisitions to capture high-margin segments.
Porter's Five Forces Analysis of Competitive Dynamics
Bargaining power of suppliers is moderate due to specialized raw material requirements like medical-grade silicone. Competitive rivalry is intense among top-tier firms, while the threat of new entrants remains constrained by high regulatory hurdles and intellectual property moats.
SWOT Analysis of the Leg Ulcer Treatments Market
Strengths include advanced bioengineered solutions and strong clinical evidence. Weaknesses involve high treatment costs. Opportunities lie in emerging homecare diagnostics, while threats stem from stringent compliance audits and pricing pressures from institutional group purchasing organizations.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with chemical and biological raw material suppliers, moving through sterile manufacturing facilities and major logistics hubs. Distribution flows via specialized medical distributors to end-users in hospitals, ambulatory centers, and direct-to-home channels.
Investment Insights and High-Potential Areas
Investors should target early-stage innovators specializing in smart dressings and non-invasive diagnostic sensors. Companies focusing on homecare-compatible venous and diabetic ulcer therapies offer superior risk-adjusted return profiles over the forecast horizon.
Conclusion and Key Takeaways
The Leg Ulcer Treatments Market presents compelling commercial prospects, anchored by a projected valuation of 8.85 Billion by 2033. Success requires aligning product portfolios with the shift toward outpatient and homecare delivery channels.
Research Methodology and Baseline Estimation
Our baseline estimates are triangulated by combining customs trade registries, primary stakeholder interviews with clinical specialists, and secondary macroeconomic indicators from global health organizations to ensure econometric accuracy and market validity.
Scope of the Report and Coverage Parameters
This report evaluates the global Leg Ulcer Treatments Market across major geographic zones, treatment modalities, and end-user verticals from 2026 through 2033, explicitly excluding aesthetic dermatology and general wound care outside ulcer indications.
Recent Developments in the Industry
Recent strategic moves feature FDA clearances for advanced cellular products by firms like MiMedX Group Inc. and distribution partnerships forged by Urgo Medical SAS. These announcements highlight active portfolio expansion aimed at capturing ambulatory care share.